
Market Overview
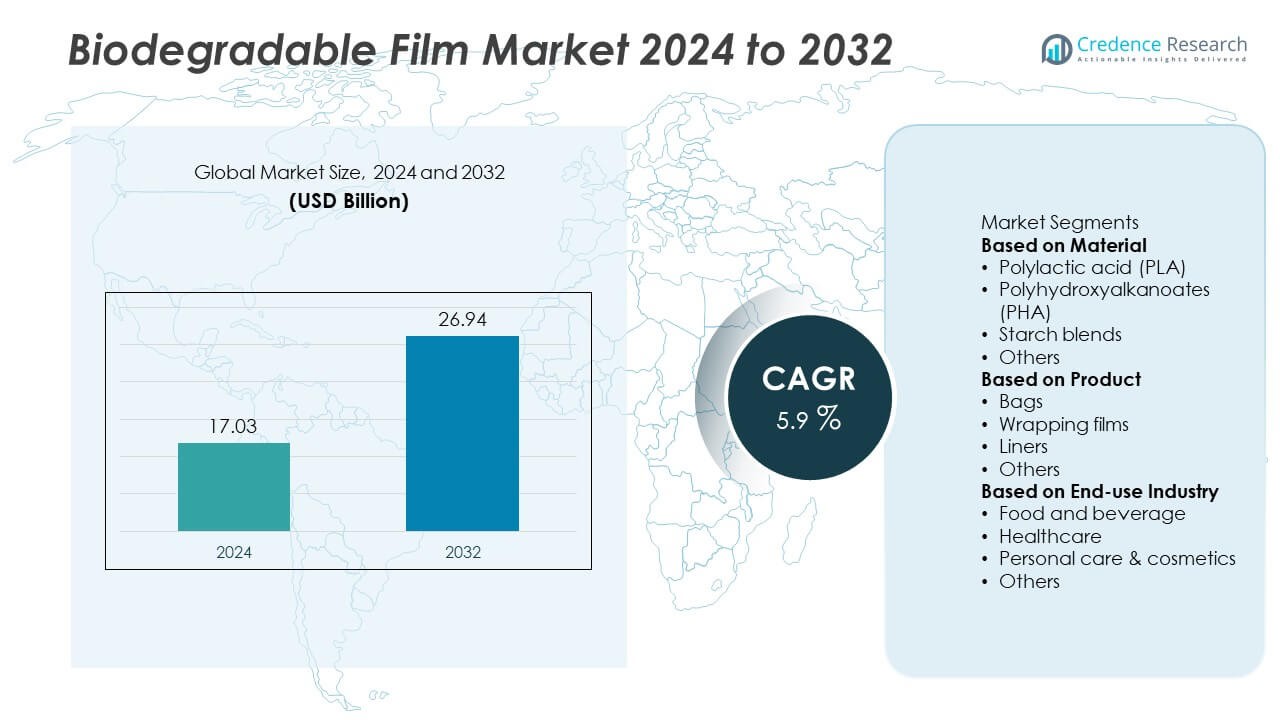
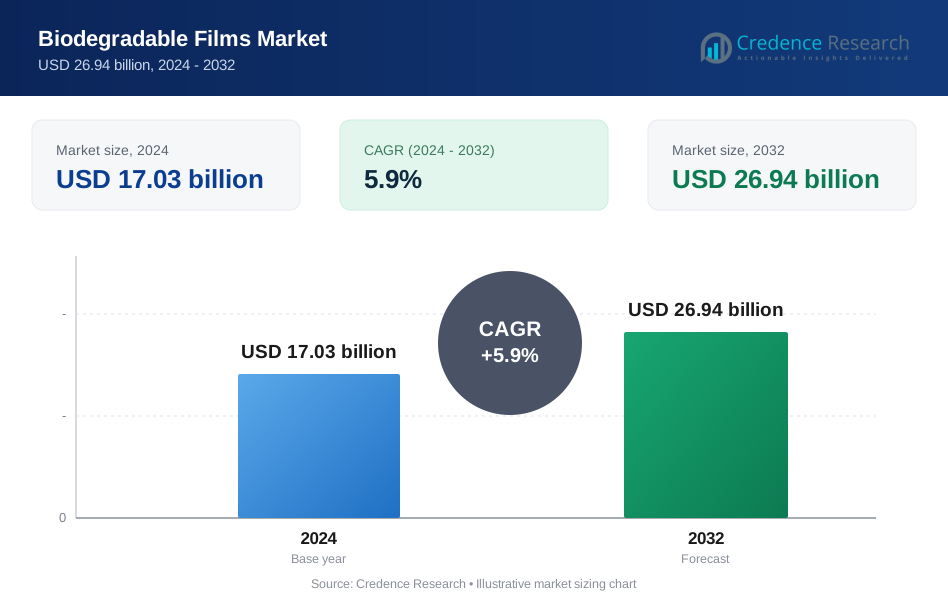
The Biodegradable Film Market was valued at USD 17.03 billion in 2024 and is projected to reach USD 26.94 billion by 2032, growing at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biodegradable Film Market Size 2024 | USD 17.03 Billion |
| Biodegradable Film Market, CAGR | 5.9% |
| Biodegradable Film Market Size 2032 | USD 26.94 Billion |
The Biodegradable Film market is led by key players such as Mondi, DS Smith, Biome Bioplastics, Opackgroup, Futamura, Barbier, Kuber Polyfilms, Cortec, Bleher Folientechnik, and Nufab Green. These companies dominate through innovations in compostable and bio-based polymer films, focusing on performance, sustainability, and regulatory compliance. Continuous advancements in PLA, PHA, and starch-based materials are strengthening their market competitiveness. North America leads the global market with a 36.8% share, driven by strong environmental regulations and high adoption in food packaging, followed by Europe with a 31.2% share, supported by circular economy initiatives and advanced biodegradable film technologies.
Market Insights
- The Biodegradable Film market was valued at USD 17.03 billion in 2024 and is expected to reach USD 26.94 billion by 2032, growing at a CAGR of 5.9% during the forecast period.
- Rising environmental concerns and government bans on single-use plastics are driving strong demand for biodegradable film across packaging and agriculture sectors.
- Rapid advancements in biopolymer technologies such as PLA and PHA, along with a growing shift toward compostable and recyclable materials, are shaping market trends.
- The market is moderately competitive, with key players including Mondi, DS Smith, Biome Bioplastics, and Futamura focusing on R&D and sustainable product innovation.
- North America leads with a 36.8% share, followed by Europe at 31.2% and Asia-Pacific at 24.6%, while the starch-based biodegradable film segment dominates with a 41.2% share, supported by its cost-effectiveness and high biodegradability.
Market Segmentation Analysis:
By Type
The starch-based biodegradable film segment dominated the Biodegradable Film market in 2024, holding a 41.2% share. Its dominance is attributed to cost-effectiveness, wide availability of raw materials, and strong biodegradability under natural conditions. Starch-based films are widely used in food packaging, agriculture, and disposable products due to their flexibility and compostable nature. The growing preference for renewable and sustainable materials among consumers and industries supports its demand. Continuous innovation in polymer blending and film strength enhancement is further expanding its application across commercial and industrial packaging sectors.
- For instance, Biome Bioplastics produces potato-starch and corn-starch based film grades, some of which are blended with other biopolyesters, that are certified industrially compostable and approved for food contact.
By Application
The food packaging segment accounted for the largest 49.6% share of the Biodegradable Film market in 2024. Rising awareness of plastic waste and strict environmental regulations are driving adoption of biodegradable alternatives in the packaging of fruits, vegetables, snacks, and bakery products. These films provide effective moisture barriers and compostability, maintaining food freshness and reducing environmental impact. Growing demand for sustainable packaging from global food retailers and quick-service chains has accelerated usage. Additionally, innovation in transparent and high-performance films continues to strengthen their adoption in the food industry.
- For instance, Futamura’s NatureFlex cellulose-based films deliver an oxygen transmission rate below 1.0 cm³/m²/day and water vapor transmission of 38 g/m²/day, offering high barrier protection for dry foods and bakery packaging under certified compostable standards.
By Material
The polylactic acid (PLA) segment held a 33.8% share of the Biodegradable Film market in 2024. PLA films are favored for their clarity, strength, and compostability, making them suitable for packaging, agriculture, and labeling applications. Derived from renewable sources like corn starch and sugarcane, PLA aligns with global sustainability goals and circular economy initiatives. Growing R&D in enhancing PLA film heat resistance and mechanical properties is broadening its commercial viability. The increasing use of PLA in consumer goods and industrial packaging is further propelling the segment’s steady market expansion worldwide.
Key Growth Drivers
Rising Environmental Awareness and Regulatory Support
Increasing global concern over plastic pollution is a major growth driver for the biodegradable film market. Governments worldwide are enforcing bans and restrictions on single-use plastics, encouraging industries to adopt eco-friendly alternatives. Regulatory frameworks such as the EU’s Green Deal and various national sustainability targets are pushing manufacturers toward biodegradable solutions. Consumers are also shifting preferences toward compostable and renewable packaging. This growing awareness, combined with supportive policies, is driving investment in biodegradable film production and innovation across multiple industries.
- For instance, DS Smith introduced fully recyclable and biodegradable film coatings capable of decomposing within 180 days under controlled composting conditions, reducing plastic waste across its packaging network covering over 200 production facilities.
Expansion of Sustainable Packaging in Food and Beverage Industry
The growing demand for eco-friendly packaging from the food and beverage sector significantly boosts the biodegradable film market. Companies are replacing conventional plastics with compostable films to enhance brand sustainability and meet consumer expectations. These films offer excellent moisture and gas barrier properties, maintaining product freshness while reducing environmental impact. The rise in online food delivery and packaged snacks further increases adoption. Partnerships between packaging producers and food manufacturers are accelerating large-scale implementation of biodegradable materials globally.
- For instance, Mondi offers a range of paper-based barrier solutions, including its PerFORMing Monoloop, which enables sustainable food trays that meet major European retailer specifications for chilled foods, and its FunctionalBarrier Paper Ultimate, a high-performance paper providing a water vapor transmission rate of below 0.5 g/m²/day.
Advancements in Biopolymer Technology
Continuous innovation in biopolymer formulations has improved the strength, flexibility, and degradability of biodegradable films. Research in polylactic acid (PLA), polyhydroxyalkanoates (PHA), and starch blends has expanded their performance range and cost competitiveness. Enhanced film properties now allow broader application in agriculture, packaging, and medical uses. Investment in bio-refinery infrastructure and scalable production methods is also reducing material costs. These advancements are enabling manufacturers to meet regulatory standards while maintaining performance and aesthetics, strengthening the overall market potential.
Key Trends & Opportunities
Shift Toward Compostable and Recyclable Solutions
A major trend in the market is the shift toward fully compostable and recyclable biodegradable films. Manufacturers are developing products that decompose in industrial composting facilities without leaving harmful residues. The growing focus on circular economy practices and zero-waste packaging is creating new opportunities. Innovations such as water-soluble and marine-degradable films are addressing disposal challenges in diverse environments. This trend aligns with global sustainability initiatives, making biodegradable films a key part of long-term waste management strategies.
- For instance, Cortec Corporation launched its Eco Works 100 film which achieved 100 % USDA-certified biobased content and is certified industrially compostable by TÜV Austria
Rising Adoption in Agricultural Applications
The use of biodegradable films in agriculture, particularly as mulch films, is gaining momentum. These films help maintain soil temperature, reduce weed growth, and eliminate the need for plastic removal after harvest. Governments in several regions are promoting their use through subsidies and eco-friendly farming policies. The shift from traditional polyethylene films to biodegradable alternatives is reducing soil contamination and improving crop yields. Expanding organic farming practices and environmental certification programs continue to drive this adoption globally.
- For instance, a field study found that the use of biodegradable mulch films led to crop yield increases of over 13 % compared to non-mulched controls in onion cultivation.
Key Challenges
High Production Costs and Limited Scalability
The cost of producing biodegradable films remains a major barrier to widespread adoption. Raw materials like PLA and PHA are more expensive than petroleum-based polymers, and production requires specialized infrastructure. Limited manufacturing capacity and complex processing methods further raise costs. Small and medium manufacturers face challenges in scaling production to meet growing demand. Addressing these cost barriers through improved economies of scale and raw material sourcing will be crucial for long-term market growth.
Performance Limitations Compared to Conventional Plastics
While biodegradable films are eco-friendly, they often lag behind conventional plastics in terms of durability, heat resistance, and shelf life. These limitations restrict their use in high-performance applications such as heavy-duty packaging and industrial products. Environmental conditions also affect biodegradation rates, posing challenges in product consistency. Manufacturers are investing in R&D to enhance mechanical properties and barrier performance. Overcoming these limitations is essential to expand market penetration and ensure long-term competitiveness against traditional materials.
Regional Analysis
North America
North America dominated the Biodegradable Film market in 2024 with a 36.8% share. The region’s growth is driven by strong environmental policies, corporate sustainability initiatives, and consumer preference for eco-friendly packaging. The United States leads with widespread adoption of compostable films in food packaging, agriculture, and retail sectors. Technological advancements in biopolymer manufacturing and collaboration between material suppliers and packaging producers support innovation. Government incentives for sustainable materials and bans on single-use plastics further accelerate market expansion, positioning North America as a leader in biodegradable film development and commercialization.
Europe
Europe held a 31.2% share of the Biodegradable Film market in 2024, supported by strict environmental regulations and advanced recycling infrastructure. The European Union’s Green Deal and circular economy targets have spurred adoption of compostable and bio-based packaging. Countries such as Germany, France, and the Netherlands lead in biodegradable film production and usage across food and agriculture sectors. Growing consumer awareness and retailer-led sustainability commitments are fueling continuous demand. Innovation in PLA and starch-based film technology further enhances Europe’s leadership, ensuring steady growth driven by regulatory compliance and environmental responsibility.
Asia-Pacific
Asia-Pacific accounted for a 24.6% share of the Biodegradable Film market in 2024, driven by rapid industrialization and increasing awareness of plastic pollution. Countries such as China, Japan, and India are investing heavily in bioplastic production facilities and R&D. Rising demand for sustainable packaging in food and consumer goods sectors supports strong market growth. Government policies promoting green materials and restrictions on plastic use are stimulating domestic production. Expanding urban populations and evolving retail structures continue to boost biodegradable film adoption, making Asia-Pacific a key growth engine in the global market.
Middle East & Africa
The Middle East and Africa region captured a 4.2% share of the Biodegradable Film market in 2024. Growing environmental awareness and government initiatives aimed at reducing plastic waste are driving adoption. The United Arab Emirates and Saudi Arabia are leading regional efforts with sustainability-focused regulations and investments in eco-friendly materials. Demand for biodegradable films in agriculture and food packaging is gradually increasing. However, limited production infrastructure and high costs constrain market penetration. Continuous regulatory support and regional collaborations with international firms are expected to strengthen market presence over the coming years.
Latin America
Latin America held a 3.2% share of the Biodegradable Film market in 2024. Growth is primarily fueled by rising sustainability initiatives in Brazil, Mexico, and Chile, where industries are transitioning toward compostable and recyclable materials. Expanding agricultural production and growing packaged food sectors are creating strong opportunities for biodegradable film applications. Government efforts to reduce plastic waste and encourage green innovation are supporting this shift. Despite infrastructure challenges, regional demand is increasing steadily as both consumers and manufacturers embrace eco-friendly packaging alternatives to meet environmental goals.
Market Segmentations:
By Material
- Polylactic acid (PLA)
- Polyhydroxyalkanoates (PHA)
- Starch blends
- Others
By Product
- Bags
- Wrapping films
- Liners
- Others
By End-use Industry
- Food and beverage
- Healthcare
- Personal care & cosmetics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Biodegradable Film market features key players such as Mondi, DS Smith, Biome Bioplastics, Opackgroup, Futamura, Barbier, Kuber Polyfilms, Cortec, Bleher Folientechnik, and Nufab Green. These companies focus on expanding their product portfolios through innovation in bio-based polymers, compostable materials, and high-performance film technologies. Strategic collaborations, acquisitions, and investments in R&D are helping them enhance film strength, moisture resistance, and heat stability. Manufacturers are increasingly adopting PLA, PHA, and starch-based materials to meet global sustainability standards and regulatory mandates. The competition is further intensified by the growing demand for recyclable and compostable films across packaging, agriculture, and consumer goods sectors. Leading players are also integrating circular economy principles and scaling production capacities to reduce costs, improve efficiency, and maintain a strong position in the evolving biodegradable film market.
Key Player Analysis
- Mondi
- DS Smith
- Biome Bioplastics
- Opackgroup
- Futamura
- Barbier
- Kuber Polyfilms
- Cortec
- Bleher Folientechnik
- Nufab Green
Recent Developments
- In July 2025, Cortec Corporation introduced its “Eco Works 100” film, certified industrially compostable and made from 100% USDA-certified biobased content.
- In May 2025, Futamura Group launched a fully compostable sachet laminate structure using its “NatureFlex” cellulose film technology for flexible packaging applications.
- In January 2025, OPACKGROUP announced new biodegradable grow bags via its subsidiary Oerlemans Plastics which leverage biodegradable film for the horticulture sector.
- In February 2023, Toppan Speciality Films and Polymateria launched a new ‘biotransformed’ packaging solution that breaks down and returns to nature harmlessly within just 176 days, leaving no microplastics or toxins behind.
Report Coverage
The research report offers an in-depth analysis based on Material, Product, End-use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for eco-friendly and compostable packaging will continue to accelerate across industries.
- Advancements in biopolymer technology will improve film strength, flexibility, and durability.
- Expansion of food packaging and agriculture applications will remain key growth drivers.
- Regulatory policies banning single-use plastics will encourage faster market adoption.
- Investment in large-scale bioplastic production facilities will reduce manufacturing costs.
- Partnerships between packaging firms and biopolymer producers will enhance innovation.
- Consumer awareness of sustainability will boost demand for biodegradable alternatives.
- Asia-Pacific will emerge as a major production hub supported by policy incentives.
- Development of recyclable and marine-degradable films will open new opportunities.
- Integration of circular economy models will shape the long-term growth of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Biodegradable Film market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Biodegradable Film market projected to grow between 2025 and 2032?
Which Biodegradable Film market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Biodegradable Film market?
Who are the leading companies in the Biodegradable Film market?
Which region commanded the largest share of the Biodegradable Film market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Biodegradable Films Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Biodegradable Films Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17.03 billion → 2032: USD 26.94 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Biodegradable Films Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Biodegradable Films Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Biodegradable Films Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Biodegradable Films Market Drivers
- 3.3 Biodegradable Films Market Restraints & Challenges
- 3.4 Biodegradable Films Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Biodegradable Films Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Biodegradable Films Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Biodegradable Films category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Biodegradable Films Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Biodegradable Films Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Biodegradable Films. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Biodegradable Films Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Biodegradable Films Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Biodegradable Films Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Biodegradable Films (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Biodegradable Films
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Biodegradable Films Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Biodegradable Films Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Biodegradable Films Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Biodegradable Films Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Biodegradable Films Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Biodegradable Films Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Biodegradable Films Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Biodegradable Films Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
