
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Biodegradable Plastics Market Size 2024 | USD 3,910 Million |
| Biodegradable Plastics Market, CAGR | 8.8% |
| Biodegradable Plastics Market Size 2032 | USD 7,677.28 Million |
Market Overview:
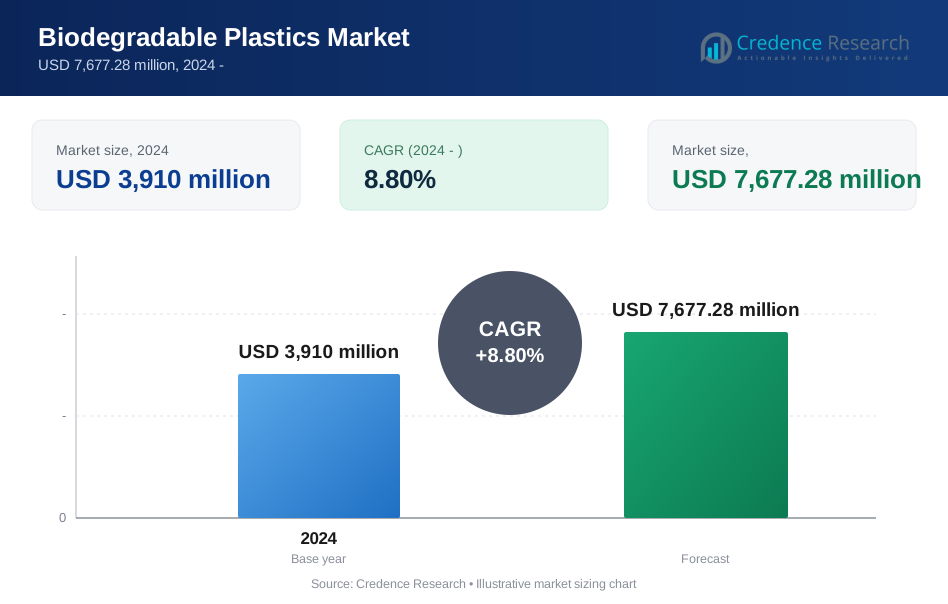
The global Biodegradable Plastics Market is projected to grow from USD 3,910 million in 2024 to USD 7,677.28 million by 2032, with a compound annual growth rate (CAGR) of 8.8%. Biodegradable plastics, derived from renewable raw materials such as corn starch, sugarcane, and cellulose, decompose more rapidly than traditional plastics, addressing environmental concerns related to plastic waste. These materials are widely adopted in packaging, agriculture, and consumer goods due to their reduced environmental footprint. Governmental bans on single-use plastics and rising consumer awareness about environmental impacts further drive demand, positioning the biodegradable plastics market for robust growth over the forecast period.
Several key drivers contribute to the market’s expansion, including stringent environmental regulations and growing support for sustainable alternatives in both developed and emerging economies. For instance, the European Union has enacted policies such as the Single-Use Plastics Directive to limit plastic waste, creating strong demand for biodegradable solutions. Additionally, industries like packaging and agriculture are increasingly adopting biodegradable plastics to meet sustainability goals and appeal to eco-conscious consumers. Innovations in biodegradable polymer technologies, including polylactic acid (PLA) and polybutylene adipate terephthalate (PBAT), further support the market, as these materials offer improved performance for a range of applications.
Regionally, Europe leads the market with a significant share, driven by its strict environmental regulations, ambitious waste reduction targets, and high adoption rates of sustainable materials. Germany, France, and Italy are key contributors, supported by governmental incentives for biodegradable packaging. North America follows closely, with demand spurred by environmental initiatives and growing awareness of plastic waste issues. The Asia-Pacific region is expected to witness the fastest growth, primarily in countries like China, Japan, and South Korea, where governments are implementing policies to combat plastic pollution and reduce dependency on petroleum-based plastics. This regional diversification underscores the global shift toward sustainable materials and highlights biodegradable plastics as a viable solution for mitigating plastic waste worldwide.
Market Drivers:
Stringent Environmental Regulations:
Stringent environmental regulations and policies targeting plastic waste are major drivers of the biodegradable plastics market. Many governments worldwide have implemented restrictions or outright bans on single-use plastics to reduce environmental impact. For instance, the European Union's Single-Use Plastics Directive mandates member states to limit plastic consumption and increase the use of sustainable alternatives. Similarly, Canada announced a nationwide ban on single-use plastics by 2023, prompting industries to adopt biodegradable plastics. These regulations encourage manufacturers to develop eco-friendly alternatives that comply with government standards, thereby fueling demand for biodegradable plastics.
Rising Consumer Awareness and Demand for Sustainable Products:
Increasing consumer awareness of the environmental impact of traditional plastics drives demand for biodegradable alternatives. Consumers are now more eco-conscious and prefer products with a smaller environmental footprint, especially in packaging and disposable items. According to a 2022 survey by the National Retail Federation, 75% of consumers in North America consider sustainability a factor in their purchasing decisions. This shift has prompted businesses to integrate biodegradable plastics into their products to align with consumer preferences and build brand loyalty among eco-conscious consumers.
Innovation in Biodegradable Polymer Technologies:
Advancements in biodegradable polymer technologies have significantly improved the quality and versatility of biodegradable plastics, expanding their applications. Innovations in polymers such as polylactic acid (PLA) and polyhydroxyalkanoates (PHA) have enhanced material properties, making them suitable for packaging, agriculture, and automotive applications. For example, BASF has developed ecoflex®, a biodegradable polymer that decomposes under industrial composting conditions, meeting European composting standards. These technological advancements allow manufacturers to offer high-performance biodegradable plastics that meet both environmental and industry-specific requirements.
Corporate and Government Initiatives Promoting Sustainability:
Corporate and government initiatives promoting sustainability and reducing reliance on fossil fuels are also accelerating the shift toward biodegradable plastics. Many companies, particularly in the packaging and consumer goods sectors, have committed to reducing their carbon footprint by transitioning to biodegradable materials. Coca-Cola, for instance, has launched a fully biodegradable bottle prototype, part of its global strategy to reduce plastic waste. Additionally, government incentives, such as tax credits and subsidies, support the development and adoption of biodegradable alternatives, creating a favorable market environment for biodegradable plastics to thrive.
Market Trends:
Growth of Biodegradable Packaging in Consumer Goods:
Biodegradable plastics are increasingly being used in the packaging sector, particularly for consumer goods, as companies aim to meet sustainability goals and reduce their environmental impact. Packaging companies are developing biodegradable plastic solutions that decompose more rapidly under natural conditions. For instance, Nestlé has committed to making 100% of its packaging recyclable or biodegradable by 2025, with significant investments in compostable materials. The rise in biodegradable packaging solutions reflects a shift in consumer expectations and industry standards, with companies aiming to reduce their reliance on traditional plastics.
Expansion of Biodegradable Plastics in Agriculture:
The agriculture sector is adopting biodegradable plastics for applications such as mulch films and plant pots, reducing soil contamination and plastic waste. Traditional plastic films used in farming can lead to soil pollution when left in fields; however, biodegradable alternatives decompose naturally and reduce plastic buildup. For example, BASF’s ecovio® mulch film is fully biodegradable and leaves no plastic residues, aligning with environmental sustainability initiatives in agriculture. This shift allows farmers to use environmentally friendly materials without compromising productivity, addressing both sustainability and agricultural needs.
Advancements in Bioplastics for Foodservice Applications:
Biodegradable plastics are gaining traction in the foodservice industry as sustainable options for cutlery, plates, and cups. Companies like McDonald’s and Starbucks have begun phasing out traditional plastic utensils in favor of biodegradable alternatives, especially in regions with stringent plastic bans. In response to a recent regulation from the European Union banning single-use plastics, Starbucks has introduced fully compostable lids and straws. These innovations in foodservice packaging align with environmental regulations and meet growing consumer demand for sustainable dining options, driving the market for biodegradable plastics in this sector.
Increasing Corporate Commitments to Carbon Neutrality:
Corporate commitments to carbon neutrality and zero-waste goals are also shaping the biodegradable plastics market. Many companies are setting ambitious targets to reduce their environmental impact and are incorporating biodegradable materials to replace petroleum-based plastics. For example, Unilever has pledged to cut its use of virgin plastic by half by 2025, investing in biodegradable and recyclable materials to meet this target. This commitment is part of a larger trend, as multinational corporations incorporate biodegradable plastics into their products to fulfill sustainability goals and improve public perception. These efforts highlight the broader shift toward sustainable materials in corporate strategies.
Market Challenges Analysis:
High Production Costs and Limited Infrastructure:
High production costs present a significant restraint in the biodegradable plastics market, as biodegradable materials are generally more expensive to produce than traditional petroleum-based plastics. This cost difference arises from the use of specialized raw materials, such as corn starch or cellulose, and complex manufacturing processes. The U.S. Environmental Protection Agency (EPA) highlights that these higher costs can hinder widespread adoption, especially in price-sensitive industries like packaging. The lack of infrastructure for large-scale biodegradable plastic production further exacerbates these costs, limiting the market’s growth potential.
Inadequate Composting and Recycling Facilities:
Another challenge is the lack of adequate composting and recycling infrastructure to handle biodegradable plastics. For biodegradable plastics to decompose effectively, they often require industrial composting facilities, which are limited in many regions. The European Environment Agency (EEA) reports that the absence of such facilities restricts the disposal options for biodegradable plastics, leading them to conventional waste streams where they do not decompose as intended. This gap between biodegradable plastic production and end-of-life processing facilities limits the effectiveness of biodegradable solutions in addressing plastic waste.
Uncertain Environmental Impact and Consumer Misconceptions:
Despite their potential, biodegradable plastics face criticism regarding their environmental impact, particularly when disposed of incorrectly. If not properly composted, these plastics may release methane, a potent greenhouse gas, during degradation. The United Nations Environment Programme (UNEP) has noted that biodegradable plastics can contribute to pollution if they end up in oceans or landfills, where they do not break down fully. Consumer misconceptions also pose a challenge, as many assume biodegradable plastics can decompose naturally under all conditions, leading to improper disposal. This lack of public awareness can undermine the environmental benefits of biodegradable plastics, as improper disposal reduces their effectiveness in reducing plastic waste.
Market Segmentation Analysis:
By Type
The biodegradable plastics market is segmented by type into polylactic acid (PLA), polybutylene adipate terephthalate (PBAT), polyhydroxyalkanoates (PHA), and starch-based plastics. PLA is the most widely used due to its cost-effectiveness and suitability for packaging applications, making it popular in industries like foodservice. PBAT, known for its flexibility and durability, is commonly used in compostable bags and agricultural films. PHA, though newer and more expensive, offers excellent biodegradability, even in marine environments, and is increasingly used in applications requiring higher environmental standards. Starch-based plastics are often combined with other polymers, enhancing biodegradability while providing an affordable alternative for single-use items.
By Technology
By technology, the market includes injection molding, extrusion, and blow molding, each chosen based on the specific end-use application. Injection molding is widely used for manufacturing biodegradable plastic products like utensils and containers due to its precision and efficiency. Extrusion is favored for packaging films and bags, while blow molding, primarily used for bottles and jars, benefits from the flexibility of materials like PLA and starch-based plastics. Advances in these technologies enable manufacturers to produce high-quality biodegradable products that meet industry standards for both performance and environmental impact.
By End User
End-user segments in the biodegradable plastics market include packaging, agriculture, consumer goods, and textiles. The packaging sector dominates, driven by regulatory bans on single-use plastics and growing consumer demand for sustainable options. Agriculture is another key segment, using biodegradable films and mulch to reduce plastic waste in farming. Consumer goods and textiles are adopting biodegradable materials to meet sustainability goals, with applications ranging from compostable bags to eco-friendly apparel packaging, underscoring biodegradable plastics’ versatility across sectors seeking reduced environmental impact.
Segmentations:
Type
- PLA
- Starch Blends
- PHA
- Biodegradable Polyesters
- Others
End-Use
- Packaging & Bags
- Consumer Goods
- Agriculture & Horticulture
- Textile
- Others
Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe
Europe holds the largest share in the biodegradable plastics market, accounting for approximately 35% of global market revenue. The region’s dominance is driven by stringent environmental regulations and strong support for sustainable alternatives. The European Union’s Single-Use Plastics Directive, which bans or restricts single-use plastics, has spurred demand for biodegradable options across various industries, particularly in packaging. Germany, France, and Italy lead the region with strong regulatory frameworks and initiatives promoting compostable and biodegradable materials. Additionally, Europe’s focus on achieving a circular economy and reducing plastic waste aligns with the goals of biodegradable plastics, encouraging investments in research and development for innovative, sustainable materials.
North America
North America follows closely, holding around 30% of the global market share, driven by growing awareness of environmental issues and increasing regulatory efforts. The United States, in particular, has seen a rise in state-level bans on single-use plastics, with California, New York, and Washington implementing restrictions on plastic bags and packaging materials. These regulatory measures promote the adoption of biodegradable plastics in packaging and foodservice industries. Furthermore, many North American companies have committed to sustainability targets that include shifting toward biodegradable materials, enhancing the region’s demand. Canada has also implemented a ban on certain single-use plastics as part of its environmental strategy, further supporting market growth in North America.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth, capturing approximately 25% of the global market share, with countries like China, Japan, and South Korea leading the adoption of biodegradable plastics. Rapid industrialization, urbanization, and rising environmental concerns have driven governments and industries to explore sustainable alternatives to traditional plastics. China, the largest plastic producer globally, has introduced policies aimed at reducing plastic waste and promoting biodegradable options, particularly in urban centers. Japan and South Korea have also implemented regulatory measures to reduce plastic usage and encourage sustainable materials in packaging and agriculture. The region’s expansion is further supported by strong investments in biodegradable plastics manufacturing, particularly as demand for eco-friendly materials grows.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively account for around 10% of the biodegradable plastics market. Latin America, led by Brazil and Mexico, is gradually adopting biodegradable plastics, particularly in agriculture and foodservice, where sustainable solutions are gaining traction. Brazil’s government has introduced policies to reduce plastic waste, creating opportunities for biodegradable alternatives. The Middle East, particularly the Gulf Cooperation Council (GCC) countries, has started to focus on sustainable materials, although adoption remains limited. Africa’s biodegradable plastics market is in its early stages, but as environmental awareness and infrastructure improve, demand for sustainable solutions is anticipated to grow gradually across these regions.
Key Player Analysis:
- BASF SE
- NatureWorks LLC
- Mitsubishi Chemical Corporation
- TotalEnergies Corbion
- Danimer Scientific
- Novamont S.p.A.
- Biotech SA
- Biome Bioplastics
- Plantic Technologies Limited
- Cardia Bioplastics
Competitive Analysis:
The biodegradable plastics market is highly competitive, with several leading companies focusing on innovation, sustainable materials, and strategic partnerships to capture market share. Key players like BASF SE, NatureWorks LLC, and Mitsubishi Chemical Corporation dominate the market due to their strong portfolios in biodegradable polymers, such as polylactic acid (PLA) and polybutylene adipate terephthalate (PBAT), which cater to diverse applications in packaging, agriculture, and consumer goods. These companies invest heavily in R&D to improve product performance and meet regulatory requirements for compostability and biodegradability, particularly in regions like Europe with stringent environmental standards. Emerging players like Danimer Scientific and TotalEnergies Corbion are also gaining traction by focusing on bioplastics derived from renewable resources and collaborating with major consumer brands to replace traditional plastics. This competitive landscape is characterized by ongoing technological advancements and an increasing emphasis on eco-friendly alternatives as companies seek to address growing consumer and regulatory demand for sustainable plastic solutions.
Recent Developments:
- BASF launched a new line of biodegradable mulch films in 2024 to support sustainable agriculture. This product decomposes naturally in soil, helping farmers reduce plastic waste without compromising crop yield.
- Danimer Scientific reported significant progress in expanding its PHA biopolymer production capabilities in 2023, with plans to meet the growing demand for biodegradable alternatives in packaging and consumer goods.
- TotalEnergies Corbion introduced a PLA-based biodegradable plastic for food packaging in 2023, addressing the need for sustainable materials that meet regulatory standards in Europe and North America.
- Mitsubishi Chemical developed a new PHA blend in 2022, designed for marine biodegradability, enhancing options for single-use items that reduce plastic waste in ocean environments.
Market Concentration & Characteristics:
The biodegradable plastics market is moderately concentrated, with major players like BASF, NatureWorks, and TotalEnergies Corbion holding substantial market shares due to their established portfolios in biodegradable polymers such as PLA, PHA, and PBAT. These companies maintain competitive positions through significant R&D investments focused on enhancing product performance, reducing production costs, and expanding applications in sectors like packaging, agriculture, and consumer goods. High entry barriers, including the need for advanced technology and regulatory compliance, reinforce market concentration. Smaller players focus on niche applications and partnerships to compete, contributing to the market's dynamic landscape driven by innovation and sustainability.
Report Coverage:
The research report offers an in-depth analysis based on Type, End-Use, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for biodegradable plastics will continue to rise as governments enforce stricter regulations on traditional plastics and promote eco-friendly alternatives.
- The packaging industry will drive significant market growth, as companies increasingly seek sustainable solutions for single-use and food packaging.
- Advances in biodegradable polymer technology, such as PLA and PHA, will expand applications in agriculture, textiles, and consumer goods.
- Corporations’ commitments to carbon neutrality will increase the adoption of biodegradable plastics, especially in consumer-facing industries.
- Asia-Pacific is expected to witness the fastest growth due to rapid industrialization and favorable government initiatives supporting sustainable materials.
- Investments in biodegradable plastics production facilities will rise to meet the demand, particularly in regions with established recycling infrastructure.
- Growing awareness about marine pollution will drive demand for biodegradable solutions that decompose in natural environments.
- The foodservice industry will continue adopting biodegradable cutlery, plates, and cups as sustainable options for disposable items.
- High production costs may decrease as manufacturers scale production, making biodegradable plastics more competitive with traditional plastics.
- Partnerships between major players and consumer brands will increase, focusing on innovation and developing eco-friendly plastic alternatives for broader use.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Government bans and restrictions on single-use plastics, such as the EU's Single-Use Plastics Directive and Canada's nationwide ban, are compelling industries to adopt biodegradable plastics to comply with new standards and reduce environmental impact.
Rising Consumer Awareness and Demand for Sustainable Products
Consumers are increasingly prioritizing sustainability in their purchasing decisions, especially for packaging and disposable items, prompting companies to integrate biodegradable plastics to align with eco-conscious preferences and build brand loyalty.
Innovation in Biodegradable Polymer Technologies
Advancements in materials like PLA and PHA have improved the performance and versatility of biodegradable plastics, enabling their use in a wider range of applications and making them more attractive to industries seeking sustainable alternatives.
Corporate and Government Sustainability Initiatives
Major corporations and governments are setting ambitious sustainability and carbon neutrality targets, driving investment in biodegradable plastics as part of broader efforts to reduce reliance on fossil fuels and minimize plastic waste.
Expansion in Packaging and Agriculture Sectors
The packaging and agriculture industries are rapidly adopting biodegradable plastics to meet regulatory requirements and sustainability goals, with innovations such as compostable films and mulch products supporting market growth in these high-volume sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Biodegradable Plastics Market?
What factors are driving the growth of the Biodegradable Plastics Market?
What are some challenges faced by the Biodegradable Plastics Market?
Who are the major players in the Biodegradable Plastics Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 PLA
- 1.2.2 Starch Blends
- 1.2.3 PHA
- 1.2.4 Biodegradable Polyesters
- 1.2.5 Others
- 1.3 By End-Use
- 1.3.1 Packaging & Bags
- 1.3.2 Consumer Goods
- 1.3.3 Agriculture & Horticulture
- 1.3.4 Textile
- 1.3.5 Others
- 1.4 By Technology
- 1.4.1 Injection Molding
- 1.4.2 Extrusion
- 1.4.3 Blow Molding
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,910 million → 2032: USD 7,677.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Biodegradable Plastics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Biodegradable Plastics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Biodegradable Plastics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Biodegradable Plastics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Biodegradable Plastics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Biodegradable Plastics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Biodegradable Plastics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Biodegradable Plastics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,910 million → 2032: USD 7,677.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Biodegradable Plastics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 PLA
- 12.3.7.2 Starch Blends
- 12.3.7.3 PHA
- 12.3.7.4 Biodegradable Polyesters
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Packaging & Bags
- 12.4.7.2 Consumer Goods
- 12.4.7.3 Agriculture & Horticulture
- 12.4.7.4 Textile
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Injection Molding
- 12.5.7.2 Extrusion
- 12.5.7.3 Blow Molding
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Biodegradable Plastics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Biodegradable Plastics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Biodegradable Plastics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Biodegradable Plastics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 NatureWorks LLC
- 18.4 Mitsubishi Chemical Corporation
- 18.5 TotalEnergies Corbion
- 18.6 Danimer Scientific
- 18.7 Novamont S.p.A.
- 18.8 Biotech SA
- 18.9 Biome Bioplastics
- 18.10 Plantic Technologies Limited
- 18.11 Cardia Bioplastics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

