
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Blood Fluid Warming System Market Size 2024 | USD 1,098.30 Million |
| Blood Fluid Warming System Market, CAGR | 13.6% |
| Blood Fluid Warming System Market Size 2032 | USD 3046.12 Million |
Market Overview:
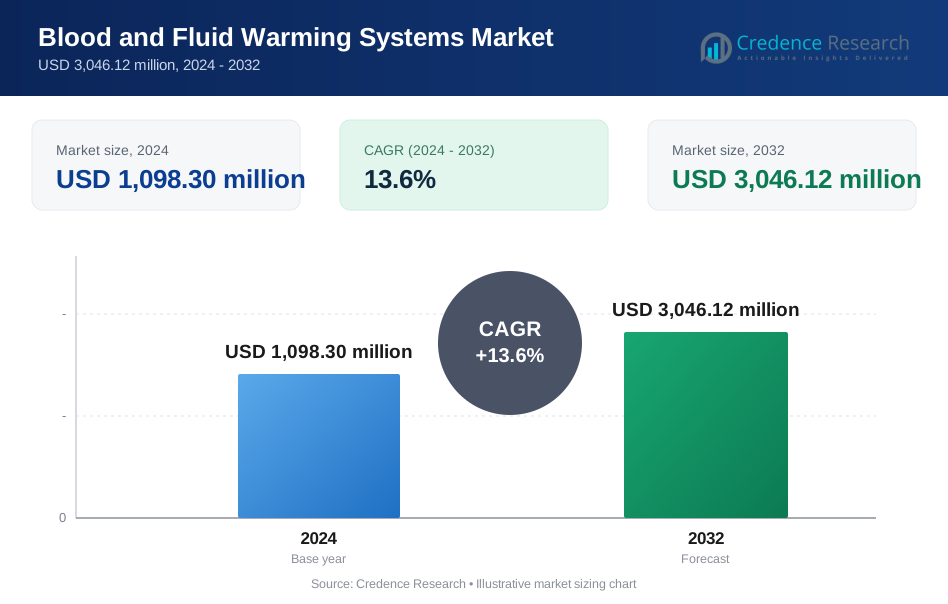
The Blood Fluid Warming System Market is projected to grow from USD 1,098.30 million in 2024 to USD 3046.12 million by 2032, at a CAGR of 13.6% from 2024 to 2032.
Key drivers of the market include the growing demand for blood transfusions in surgical procedures, emergency care, and trauma management. The rising prevalence of chronic diseases, such as cardiovascular conditions and cancer, which often require blood transfusions and fluid administration, is fueling the market growth. Moreover, the increasing number of surgeries and emergency procedures worldwide has further escalated the demand for these warming systems. Furthermore, advancements in warming technology, such as portable and efficient devices, have improved the efficiency and safety of blood and fluid warming systems, thereby driving adoption across hospitals, ambulatory surgical centers, and emergency medical services (EMS). The ongoing research and development in this field to create more cost-effective and innovative solutions are also contributing to the market’s expansion, ensuring broader accessibility.
Regionally, North America currently holds the largest share of the Blood Fluid Warming System market, driven by the presence of well-established healthcare infrastructure, a high number of surgical procedures, and strong healthcare spending. The robust regulatory framework and reimbursement policies in the region have further facilitated the growth of the market. Europe follows closely, with advancements in medical technologies and high healthcare standards, which support the adoption of new medical devices. The Asia-Pacific region is expected to exhibit the fastest growth during the forecast period, owing to the increasing healthcare investments, rising awareness about advanced medical technologies, and improving healthcare access in emerging economies like China and India. Furthermore, the growing medical tourism sector in the region is also boosting the demand for blood and fluid warming systems.
Market Insights:
- The Blood Fluid Warming System market is projected to grow from USD 1,098.30 million in 2024 to USD 3,046.12 million by 2032, driven by the growing demand for blood transfusions in surgeries and trauma care.
- Rising chronic diseases such as cardiovascular conditions and cancer are increasing the need for blood and fluid administration, which boosts the market for warming systems.
- The increasing number of surgeries and emergency procedures worldwide is significantly fueling the demand for efficient blood fluid warming solutions.
- Technological advancements, such as portable and efficient warming devices, are improving the safety and efficiency of blood fluid warming systems, enhancing their adoption.
- The expansion of healthcare infrastructure in emerging economies, like India and China, is expected to create significant growth opportunities for blood fluid warming systems.
- North America holds the largest market share, supported by strong healthcare infrastructure, high surgical volumes, and advanced medical technologies.
- The Asia-Pacific region is expected to exhibit the fastest market growth, driven by rising healthcare investments and increasing awareness of advanced medical technologies.
Market Drivers:
Increasing Surgical Procedures and Trauma Care:
The demand for blood fluid warming systems is primarily driven by the rising number of surgical procedures and trauma cases globally. For instance, the World Health Organization (WHO) reports that 313 million surgical procedures are performed worldwide each year. As surgeries and emergency interventions increase, there is a heightened need for effective blood transfusion and fluid management. Blood and fluid warming systems play a crucial role in preventing hypothermia, ensuring patient safety, and optimizing surgical outcomes. In trauma and critical care settings, these systems are essential for stabilizing patients and enhancing recovery, further driving market demand.
Rising Prevalence of Chronic Diseases:
The growing prevalence of chronic diseases, such as cardiovascular disorders, cancer, and diabetes, is contributing to the increased requirement for blood transfusions and fluid administration. For instance, the Cleveland Clinic has successfully utilized blood fluid warming systems in cardiovascular surgeries to maintain optimal body temperature and improve patient outcomes. Patients with chronic conditions often undergo frequent surgical treatments, which require blood and fluid support during and post-surgery. This trend, coupled with an aging global population, is expected to sustain the demand for blood fluid warming systems, as they are vital for maintaining optimal body temperature during medical procedures.
Technological Advancements:
Advancements in blood fluid warming technology, particularly the development of portable and efficient warming devices, are significantly enhancing system adoption. For instance, the Belmont Rapid Infuser, a widely used blood and fluid warming device, provides more user-friendly, reliable, and cost-effective solutions. These innovations provide more user-friendly, reliable, and cost-effective solutions, making them accessible to a wider range of healthcare settings, including ambulatory surgical centers and emergency medical services (EMS). Furthermore, improvements in device safety and precision continue to support their widespread implementation.
Supportive Healthcare Infrastructure:
The increasing investments in healthcare infrastructure, especially in emerging economies, are expected to further propel the market. For instance, India's National Health Mission (NHM) has been instrumental in improving healthcare facilities and modernizing medical equipment across the country. As countries enhance their healthcare facilities and modernize their medical equipment, the adoption of advanced medical devices, such as blood fluid warming systems, is rising. Improved access to healthcare and the growing awareness of patient safety are key factors boosting market growth, particularly in regions like Asia-Pacific and Latin America.
Market Trends:
Growing Adoption of Portable Devices:
One of the key trends in the Blood Fluid Warming System market is the increasing adoption of portable and compact warming devices. For instance, the ThermoSuit System by Life Recovery Systems is widely used in emergency medical services (EMS) and trauma care, where immediate access to medical equipment is crucial. These devices provide healthcare professionals with greater flexibility, especially in emergency medical services (EMS) and trauma care, where immediate access to medical equipment is crucial. Portable systems are also beneficial in outpatient settings, such as ambulatory surgical centers, where space and resources are limited. This trend is helping expand the reach of blood fluid warming systems across various healthcare settings.
Integration of Smart Technologies:
Another significant trend is the integration of smart technologies into blood fluid warming systems. For example, the 3M™ Bair Hugger™ Temperature Monitoring System is equipped with advanced monitoring features that allow healthcare providers to track temperature regulation and ensure patient safety. Modern devices are now equipped with advanced monitoring features that allow healthcare providers to track temperature regulation and ensure patient safety. Some systems are connected to hospital networks, enabling real-time data collection and analysis. These innovations improve the precision of fluid warming, reduce the risk of overheating or underheating, and enhance the overall efficiency of medical procedures.
Focus on Cost-Effectiveness and Sustainability:
As healthcare facilities increasingly face budget constraints, there is a growing emphasis on cost-effective and sustainable solutions in the blood fluid warming market. For instance, the Enthermics Medical Systems EC Series, which are energy-efficient and cost-effective warming cabinets, are being adopted by healthcare facilities. Manufacturers are developing systems that are both affordable and energy-efficient, reducing operational costs while maintaining optimal performance. Additionally, the trend toward eco-friendly materials and energy-efficient designs reflects the industry’s commitment to sustainability without compromising on patient care.
Expansion in Emerging Markets:
The demand for blood fluid warming systems is also rising in emerging markets, driven by improved healthcare access and infrastructure. For instance, in India, the National Health Mission (NHM) has been instrumental in modernizing medical equipment and improving healthcare facilities. Countries in regions such as Asia-Pacific, Latin America, and the Middle East are witnessing significant growth in the adoption of advanced medical devices. This trend is largely fueled by government investments in healthcare and increasing awareness of patient safety, leading to greater market opportunities in these regions.
Market Challenges Analysis:
High Initial Cost of Devices:
One of the primary challenges faced by the Blood Fluid Warming System market is the high initial cost of devices, which can limit their adoption, especially in resource-constrained healthcare settings. Hospitals and clinics with tight budgets may find it difficult to justify the investment in advanced warming systems, despite their long-term benefits in patient care. This is particularly true in developing regions where healthcare infrastructure is still evolving and funding for medical equipment is limited.
Regulatory and Compliance Issues:
Blood fluid warming systems must comply with stringent regulatory standards to ensure safety and efficacy. Navigating these regulations can be complex and time-consuming for manufacturers, especially when introducing new technologies to the market. Additionally, varying regulations across different countries can create barriers for global market expansion. Manufacturers must ensure that their products meet the specific requirements of each region, which can increase development time and costs.
Risk of Device Malfunction:
While technological advancements have improved the reliability of blood fluid warming systems, there is still a risk of device malfunction, particularly in critical care situations. Any failure in the warming system during surgery or trauma care could result in adverse patient outcomes. Ensuring the reliability of these systems, particularly in high-stakes environments, remains a significant challenge. Regular maintenance and rigorous testing are essential to mitigate these risks, but the potential for errors persists.
Lack of Awareness in Emerging Markets:
In emerging markets, there is a lack of awareness about the importance of blood fluid warming systems in patient safety and recovery. This lack of education, coupled with limited access to advanced healthcare technologies, hampers market growth in these regions. Increased awareness campaigns and improved healthcare education are essential to drive adoption in these regions.
Market Opportunities:
The rapid expansion of healthcare infrastructure in emerging markets presents significant opportunities for the blood fluid warming system market. As developing countries such as those in Asia-Pacific, Latin America, and the Middle East invest heavily in modernizing their healthcare systems, the demand for advanced medical devices, including blood fluid warming systems, is expected to rise. The increasing focus on improving patient care and safety in these regions creates a fertile environment for the adoption of such technologies. Additionally, government initiatives to enhance healthcare access and improve outcomes are likely to further fuel the demand for these critical systems in hospitals, ambulatory surgical centers, and trauma units.
Technological advancements and innovations in blood fluid warming systems also create vast opportunities for market growth. Manufacturers are increasingly focusing on developing portable, user-friendly, and energy-efficient warming devices that cater to a wide range of healthcare settings, including emergency medical services (EMS) and outpatient clinics. Innovations such as smart systems with real-time monitoring capabilities are driving demand for more precise and reliable warming solutions. Furthermore, as healthcare providers seek more cost-effective and sustainable options, opportunities to introduce affordable, eco-friendly devices are growing. These technological improvements not only enhance patient safety but also contribute to long-term operational savings, making blood fluid warming systems a compelling investment for healthcare providers worldwide.
Market Segmentation Analysis:
By Product
The Blood Fluid Warming System market is segmented into static warmers, portable warmers, and blood/fluid warming devices. Static warmers dominate the market due to their widespread use in hospital settings for surgical and critical care procedures. However, portable warmers are gaining traction due to their versatility in emergency medical services (EMS) and trauma care, where quick access to blood or fluids is crucial.
By Application
The market is divided into surgical applications, trauma care, and emergency care. Surgical applications hold the largest share, driven by the increasing number of surgeries globally and the need for maintaining normothermia during operations. Trauma and emergency care segments are also growing rapidly, fueled by the rising number of trauma cases and the critical need for blood and fluid management in these situations.
By Distribution Channel
The market is segmented into hospitals, ambulatory surgical centers, and emergency medical services. Hospitals account for the largest market share, driven by the high volume of surgical procedures and emergency care activities. Ambulatory surgical centers are expected to witness significant growth due to the increasing number of outpatient procedures, while the emergency medical services segment is expanding due to the rising demand for mobile blood fluid warming solutions in pre-hospital care.
Segmentations:
By Product:
- Patient Blood Fluid Warming Accessories
- Surface Blood Fluid Warming System
- Intravenous Blood Fluid Warming System
By Distribution Channel:
- Clinics
- E-Commerce
- Hospitals
By Application:
- New Born Care
- Homecare
- Acute Care
- Preoperative Care
- Other Applications
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share of 38% in the Blood Fluid Warming System market, driven by a well-established healthcare infrastructure, a high number of surgical procedures, and strong healthcare spending. The demand for blood fluid warming systems in the region is primarily fueled by the increasing prevalence of chronic diseases, rising trauma cases, and the adoption of advanced medical technologies. Additionally, the presence of key manufacturers and the development of innovative, portable warming devices have further solidified the region’s dominance. The robust regulatory framework, favorable reimbursement policies, and high healthcare standards continue to support market growth in North America.
Europe
Europe accounts for a significant share of 32% in the global market. The region’s healthcare system is known for its high standards, and there is a growing emphasis on patient safety and advanced medical technologies, driving the demand for blood fluid warming systems. The increasing number of surgeries, rising geriatric population, and the expansion of trauma care services are key factors contributing to market growth. Additionally, European countries are focusing on improving healthcare access, further propelling the adoption of such systems in hospitals and surgical centers. Research and development in medical devices are also advancing, with manufacturers introducing more efficient and cost-effective warming systems.
Asia-Pacific
Asia-Pacific is expected to experience the fastest market growth, with a projected market share of 20%. This region is witnessing significant healthcare investments and improvements in medical infrastructure. Emerging economies, such as China and India, are expanding their healthcare facilities, leading to greater demand for advanced medical technologies, including blood fluid warming systems. The growing awareness of patient safety, an increasing number of surgeries, and the rising incidence of trauma and chronic diseases contribute to market growth in the region. Furthermore, the increasing number of medical tourism patients in countries like Thailand, Malaysia, and India is expected to further accelerate market adoption.
Rest of the World
The Rest of the World (RoW) region, which includes Latin America, the Middle East, and Africa, holds a market share of 10%. Despite lower healthcare expenditure compared to other regions, the RoW segment is experiencing gradual growth. Increased healthcare investments in the Middle East and Latin America are fostering market expansion. Additionally, the growing number of surgical procedures, trauma cases, and improvements in healthcare access in these regions are driving the adoption of blood fluid warming systems. However, challenges such as limited awareness and budget constraints still impede widespread market penetration in this segment.
Key Player Analysis:
- Smiths Medical
- Barkey GmbH & Co. KG
- The 3M Company
- Stryker Corporation
- Zoll Medical Corporation
- ThermoTek, Inc.
- Fresenius Kabi
- Baxter International Inc.
- Lepu Medical Technology
- Carefusion (a BD Company)
Competitive Analysis:
The Blood Fluid Warming System market is highly competitive, with several key players striving for market share through innovation, product development, and strategic partnerships. Companies like Smiths Medical, Stryker Corporation, and Fresenius Kabi lead the market due to their established brand presence and comprehensive product offerings across surgical, trauma, and emergency care segments. These players focus on enhancing the efficiency, portability, and safety of their warming systems to cater to diverse healthcare settings, including hospitals and emergency medical services (EMS). For instance, ThermoTek's VascuTherm 5 device is recognized for its portability and cost-effectiveness, making it ideal for use in developing regions. Emerging players such as ThermoTek and Lepu Medical Technology are gaining traction by introducing cost-effective and portable warming devices, targeting markets in developing regions. Innovation, such as smart monitoring systems and eco-friendly solutions, is becoming increasingly important to differentiate products in the competitive landscape. Additionally, strategic mergers, acquisitions, and collaborations are key strategies to expand geographical presence and product offerings.
Recent Developments:
- In January 2024, Ballad Health, and the Ballad Health Innovation Center partnered with 410 Medical, Inc., to employ their LifeFlow device, a quick fluid delivery mechanism that lowers the time required to resuscitate a patient in need of blood and fluids. This development indirectly supports the market for blood and fluid warming systems by enhancing the speed and efficiency of fluid administration.
- In March 2023, Barkey GmbH & Co. KG launched the Vialguard Pro, an automated solution designed to thaw multiple small volume vials vertically, building on their expertise in fluid warming for the cell and gene therapy sector.
- In June 2023, Dragerwerk AG & Co. KGAA, a company known for its medical technology solutions, launched the FDA-cleared Babyroo TN300, a new open warmer that offers supportive lung protection and temperature stability from the moment of birth through discharge. This development indirectly supports the market for blood and fluid warming systems by enhancing neonatal care.
Market Concentration & Characteristics:
The Blood Fluid Warming System market is moderately concentrated, with a few key players dominating the industry, including Smiths Medical, Stryker Corporation, and Fresenius Kabi. These companies hold significant market share due to their extensive product portfolios, advanced technological solutions, and strong brand recognition. However, the market also features a number of emerging players, such as ThermoTek and Lepu Medical Technology, which are focusing on developing portable, cost-effective, and innovative warming devices. The competition is driven by continuous innovation, with key players striving to differentiate their products through improved efficiency, safety features, and integration with smart technologies. As demand grows, particularly in emerging markets, smaller companies are tapping into niche segments, providing opportunities for new entrants. The market’s characteristics are shaped by the need for high-quality, reliable, and user-friendly systems to meet the growing demands of healthcare settings globally.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, Distribution Channel and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for blood fluid warming systems will continue to rise as surgical procedures and trauma cases increase globally.
- Advancements in portable and compact warming devices will drive adoption in emergency medical services and outpatient care.
- Technological innovations such as smart systems with real-time monitoring will improve the precision and safety of blood fluid warming.
- The growing focus on patient safety and normothermia in surgery will further propel the need for efficient warming systems.
- The expansion of healthcare infrastructure in emerging markets, particularly in Asia-Pacific, will create significant growth opportunities.
- The aging global population and the rising prevalence of chronic diseases will contribute to a steady increase in blood transfusions and fluid management requirements.
- Eco-friendly and cost-effective warming solutions will become more popular as healthcare providers look to optimize budgets while maintaining quality care.
- Manufacturers will focus on developing energy-efficient and user-friendly devices to meet the needs of various healthcare settings.
- Regulatory standards and product safety features will become more stringent, driving continuous improvements in system reliability.
- Strategic partnerships, mergers, and acquisitions will allow companies to expand their product offerings and geographical reach, further strengthening competition in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Blood Fluid Warming System market?
What are the key drivers of the Blood Fluid Warming System market?
How do technological advancements impact the Blood Fluid Warming System market?
Which region currently holds the largest market share for Blood Fluid Warming Systems?
Which region is expected to show the fastest growth in the Blood Fluid Warming System market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Blood and Fluid Warming Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Blood and Fluid Warming Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,098.30 million → 2032: USD 3,046.12 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Blood and Fluid Warming Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Blood and Fluid Warming Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Blood and Fluid Warming Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Blood and Fluid Warming Systems Market Drivers
- 3.3 Blood and Fluid Warming Systems Market Restraints & Challenges
- 3.4 Blood and Fluid Warming Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Blood and Fluid Warming Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Blood and Fluid Warming Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Blood and Fluid Warming Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Blood and Fluid Warming Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Blood and Fluid Warming Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Blood and Fluid Warming Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Blood and Fluid Warming Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Blood and Fluid Warming Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Blood and Fluid Warming Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Blood and Fluid Warming Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Blood and Fluid Warming Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Blood and Fluid Warming Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Blood and Fluid Warming Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Blood and Fluid Warming Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Blood and Fluid Warming Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Blood and Fluid Warming Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Blood and Fluid Warming Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Blood and Fluid Warming Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Blood and Fluid Warming Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
