
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Robotic Rehabilitation and Assistive Technologies Market Size 2023 | USD 1957.68 Million |
| Robotic Rehabilitation and Assistive Technologies Market, CAGR | 20.91% |
| Robotic Rehabilitation and Assistive Technologies Market Size 2032 | USD 9020.88 Million |
Market Overview
The Robotic Rehabilitation and Assistive Technologies Market is projected to witness substantial growth, escalating from USD 1957.68 million in 2023 to USD 9020.88 million by 2032, representing a remarkable compound annual growth rate of 20.91%. The Robotic Rehabilitation and Assistive Technologies Market stands as a burgeoning sector, seamlessly blending the realms of healthcare and technology to offer groundbreaking solutions that augment patient outcomes and enrich quality of life. With a wide spectrum of robotic devices and assistive technologies, this market addresses the diverse needs of individuals grappling with disabilities or undergoing rehabilitation processes. Leveraging robotics, artificial intelligence, and sensor technologies, these innovations deliver tailored rehabilitation programs and assistive devices tailored to the unique requirements of patients.
Driven by an escalating demand for personalized healthcare solutions, the domain of robotic rehabilitation and assistive technologies has witnessed remarkable strides in recent years. Propelled by factors such as the increasing prevalence of disabilities stemming from aging populations, chronic ailments, and traumatic injuries, there's a growing impetus behind the adoption of these technologies. Offering enhanced mobility, independence, and functional recovery, robotic rehabilitation and assistive devices cater to a broad spectrum of physical impairments, fostering improved patient outcomes.
The landscape is further enriched by rapid technological advancements, with innovations such as exoskeletons, robotic prosthetics, and virtual reality-based rehabilitation systems expanding treatment options and elevating patient care standards. As the global population ages at an unprecedented pace, there's an escalating demand for rehabilitation services and assistive devices to address age-related conditions like stroke, Parkinson's disease, and osteoarthritis. Robotic technologies play a pivotal role in providing targeted interventions tailored to the unique needs of elderly patients, thereby fostering independence and enhancing their quality of life.
Government initiatives aimed at promoting healthcare accessibility and technological innovation have infused significant momentum into the market. Funding support for research and development projects, coupled with favorable reimbursement policies for assistive devices, has propelled market growth and fostered collaboration within the industry. Embracing a patient-centric approach, these technologies enable personalized treatment plans, real-time monitoring, and remote rehabilitation services, empowering patients to actively engage in their recovery journey and attain optimal outcomes.
Segmentation Analysis
By Product Type:
The market segmentation by product type encompasses a range of offerings tailored to address specific rehabilitation and assistive needs. Surveillance and security robots ensure patient safety and monitoring within healthcare facilities. Humanoid robots simulate human interaction, facilitating engagement and socialization during therapy sessions. Physical therapy and rehabilitation robots provide targeted exercises and assistive movements, enhancing recovery outcomes. Assistive robotics offer support in daily activities, promoting independence for individuals with disabilities. Intelligent prosthetics incorporate advanced technologies to mimic natural limb functionality, improving mobility and quality of life.
By Application:
The application segmentation highlights the versatility of robotic rehabilitation and assistive technologies in addressing a wide spectrum of medical conditions and therapeutic needs. Orthopedics and sports medicine utilize robotic systems for precise movement analysis, personalized rehabilitation programs, and performance enhancement strategies. Stroke rehabilitation focuses on restoring motor function and cognitive abilities through targeted exercises and task-specific training facilitated by robotic assistance. Cognitive and motor skills therapy utilizes interactive robots to engage patients in cognitive exercises and motor skill development, promoting neuroplasticity and functional improvement. Military Strength Training employs robotic systems for physical conditioning and injury prevention among military personnel.
Segments:
By Product Type:
- Surveillance and security
- Humanoid
- Physical therapy and rehabilitation
- Assistive Robotics
- Intelligent Prosthetics
By Portability:
- Fixed Base
- Mobile
By Application:
- Orthopedics and Sports Medicine
- Stroke
- Cognitive and motor skills
- Military strength training
- Post Surgery
By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Market Drivers
Empowering Independence Through Innovation
In recent years, the prevalence of disabilities and chronic diseases has witnessed a notable surge. For instance, the overall prevalence of disability was 4.52% in India. Conditions such as rheumatoid arthritis, spinal cord injuries, cerebral palsy, and age-related disabilities are becoming increasingly common. In 2019, 18 million people worldwide were living with rheumatoid arthritis, and between 250,000 and 500,000 people suffer a spinal cord injury each year. Cerebral palsy affects between 1 and 4 children for every 1,000 babies born. Age-related disabilities are also on the rise, with more than 46% of older persons – those aged 60 years and over having disabilities.
Unveiling the Impact of a Growing Elderly Population
One of the primary drivers behind the escalating demand for robotic rehabilitation and assistive technologies is the global phenomenon of population aging. As society ages and life expectancy increases, a greater proportion of individuals are predisposed to chronic health conditions that often result in disabilities. For instance, the global life expectancy has increased by more than 6 years between 2000 and 2019-from 66.8 years in 2000 to 73.4 years in 2019. For seniors, maintaining autonomy and preserving quality of life are paramount concerns. Robotic technologies present a promising avenue for addressing these challenges, enabling seniors to access comprehensive rehabilitation services and personalized assistance that facilitate independent living.
Revolutionizing Patient Care Through Robotics
The landscape of robotics technology is undergoing a paradigm shift, characterized by continuous advancements that revolutionize patient care. These technological innovations have ushered in a new era of sophisticated and effective rehabilitation and assistive devices. By leveraging robotics, healthcare professionals can administer more intensive and targeted therapy tailored to the unique needs of each individual. From robotic exoskeletons facilitating mobility for individuals with spinal cord injuries to assistive robotic arms aiding those with limited dexterity, the possibilities for enhancing patient outcomes are boundless.
Driving Adoption Through Healthcare Investment
Amidst escalating healthcare spending, governments and private insurers are increasingly recognizing the value of investing in technologies that enhance patient care while optimizing healthcare costs. Robotic rehabilitation and assistive technologies have emerged as prime candidates for such investment, offering the dual benefits of improved patient outcomes and cost-effectiveness. By streamlining rehabilitation processes and reducing the need for prolonged hospital stays, these technologies not only enhance the quality of care but also alleviate financial burdens on healthcare systems.
Charting a Course Towards Inclusive Healthcare
As the prevalence of disabilities continues to rise and the demographic landscape evolves, the imperative for accessible and inclusive healthcare solutions becomes ever more pronounced. Robotic rehabilitation and assistive technologies represent a beacon of hope, offering transformative solutions that empower individuals to overcome physical limitations and lead fulfilling lives. By harnessing the power of innovation, collaboration, and investment, we can navigate towards a future where healthcare is not just a service but a fundamental right accessible to all, regardless of ability or age.
Market Trends
Home-Based Rehabilitation
A notable market trend in rehabilitation robotics is the growing focus on providing therapies in the comfort of patients' homes. This shift is fueled by various factors, including convenience, reduced costs, and improved patient comfort. As healthcare delivery models evolve, there's a surge in the development of portable and teleoperated rehabilitation robots, facilitating seamless home-based rehabilitation experiences.
Harnessing AI and machine learning for personalized therapy
The integration of advanced technologies like AI and machine learning is revolutionizing rehabilitation robotics. These technologies enable the creation of personalized therapy plans tailored to individual needs, offering real-time feedback for both patients and therapists. Additionally, AI-driven data collection mechanisms enhance progress tracking, fostering more effective rehabilitation outcomes and empowering patients on their recovery journey.
Immersive Therapy Experiences with VR and AR
Virtual reality (VR) and augmented reality (AR) are emerging as powerful tools in rehabilitation robotics, offering immersive and engaging therapy experiences. By leveraging VR and AR technologies, therapists can create realistic training environments that motivate patients and improve coordination. These innovative approaches not only enhance rehabilitation efficacy but also pave the way for novel therapeutic interventions in diverse clinical settings.
Enhancing Mobility with Wearable Robotic Exoskeletons
Wearable robotic exoskeletons are gaining momentum as transformative solutions for rehabilitation and functional assistance. These devices provide physical support and improve gait for individuals with mobility impairments, offering newfound independence and mobility. With advancements in materials and design, wearable exoskeletons are becoming increasingly ergonomic and adaptable, catering to a wide range of patient needs.
Beyond physical rehabilitation
In addition to physical rehabilitation, there's a burgeoning market for robots designed to aid cognitive recovery in patients recovering from strokes, brain injuries, or other neurological conditions. These cognitive rehabilitation robots offer tailored cognitive stimulation exercises, assisting patients in regaining memory, focus, and problem-solving skills. By addressing cognitive impairments, these innovative solutions contribute to comprehensive rehabilitation strategies aimed at restoring overall functional independence.
Market Restraints and Challenges
High Cost
The adoption of robotic rehabilitation and assistive technologies is often impeded by their substantial financial burden. The initial purchase price, coupled with ongoing maintenance and service costs, creates a significant barrier to entry, particularly for individual patients without adequate insurance coverage. The sheer expense associated with these technologies not only limits accessibility but also exacerbates healthcare disparities, as those with limited financial resources may struggle to afford the benefits they offer. Tackling the issue of affordability requires innovative financing solutions and collaborative efforts among stakeholders to ensure equitable access to transformative rehabilitation technologies.
Lack of reimbursement
Despite their potential to revolutionize patient care, robotic rehabilitation and assistive technologies may not always be covered by insurance policies, leaving patients to navigate complex reimbursement processes on their own. This lack of coverage exacerbates disparities in healthcare access, as individuals may be unable to afford these technologies without financial assistance. Addressing coverage gaps requires advocacy efforts to expand insurance coverage for rehabilitation robotics and to streamline reimbursement processes, ensuring that patients can access the care they need without financial hardship.
Regulatory Hurdles
The stringent regulatory requirements governing the approval of new robotic rehabilitation and assistive devices pose formidable challenges for manufacturers and healthcare providers alike. Navigating the complex landscape of regulatory compliance can be time-consuming and resource-intensive, delaying the availability of innovative technologies to patients in need. Streamlining regulatory processes and fostering collaboration between regulatory agencies and industry stakeholders are essential to expediting the development and approval of rehabilitation robotics and facilitating timely access to cutting-edge solutions for patients worldwide.
Skilled personnel shortage
The effective utilization of robotic rehabilitation and assistive technologies hinges on the availability of a skilled workforce equipped with specialized training in their operation and integration into treatment plans. However, there is a shortage of qualified personnel, including therapists and caregivers, capable of harnessing the full potential of these technologies. Investing in workforce development initiatives, such as training programs and continuing education opportunities, is essential to address this shortage and ensure that healthcare professionals are equipped to deliver high-quality care using rehabilitation robotics.
Patient Acceptance
Despite their potential benefits, some patients may harbor reservations about the use of robotic devices for rehabilitation, citing concerns about safety, comfort, or a lack of understanding about the advantages they offer. Fostering patient acceptance requires efforts to build trust and provide comprehensive education about the benefits and safety protocols associated with rehabilitation robotics. Engaging patients in shared decision-making and addressing their concerns through transparent communication are essential to promoting acceptance and facilitating the integration of robotic technologies into rehabilitation practice.
Data privacy and security
The collection of sensitive patient data by robotic rehabilitation and assistive technologies raises important concerns about data privacy and security. Safeguarding patient confidentiality is paramount, necessitating robust measures to protect data from unauthorized access or breaches. Ensuring compliance with data privacy regulations and implementing stringent security protocols are critical steps in safeguarding patient information and fostering trust in the ethical use of rehabilitation robotics. Collaborative efforts among stakeholders are essential to developing standardized protocols and best practices for data privacy and security in the field of rehabilitation robotics.
Key Players
- Kinova, Inc
- Instead Technologies Ltd.
- ReWalk Robotics
- AlterG, Inc
- Bionik Laboratories Corp.
- Health Robotics S.R.L.
- Bioxtreme Robotics Rehabilitation
- Mazor Robotics Ltd.
- Incent Medical Holdings Limited
- Cyberdyne INC
Recent Developments
In November 2021, Inrobics Social Robotics, S.L.L., a spin-off from the Universidad Carlos III de Madrid (UC3M), unveiled a groundbreaking robotic device designed to offer a novel motor and cognitive rehabilitation service. This innovative technology, developed through research conducted by the university's Department of Computer Science and Engineering, presents a versatile solution that can be seamlessly integrated into healthcare settings as well as utilized within the comfort of patients' homes. Leveraging cutting-edge research outcomes, Inrobics aims to revolutionize the field of rehabilitation by providing tailored therapeutic interventions to individuals seeking to regain motor function and cognitive abilities.
In January 2021, Harmonic Bionics forged a strategic partnership with H Robotics to introduce smart tele-rehabilitation solutions to patients in the United States grappling with neurological and musculoskeletal movement impairments. This collaboration represents a concerted effort to harness technological advancements in robotics and telemedicine to address the diverse rehabilitation needs of patients across the nation. By combining Harmonic Bionics' expertise in rehabilitation robotics with H Robotics' proficiency in smart telepresence solutions, the partnership seeks to deliver innovative and accessible rehabilitation services to individuals navigating movement impairments, enhancing their quality of life, and promoting functional independence.
Regional Analysis
North America
North America dominates the global robotic rehabilitation and assistive technologies market, accounting for over 40% of the total market share. The United States leads this dominance, driven by the presence of major market players such as Intuitive Surgical, Cyberdyne, and Ekso Bionics. The region's advanced healthcare infrastructure, favorable reimbursement policies, and the increasing prevalence of neurological disorders and musculoskeletal conditions have fueled the demand for robotic rehabilitation and assistive technologies. Moreover, the region's focus on technological innovation and the adoption of cutting-edge solutions have further propelled market growth.
Europe
Europe holds a significant share of the robotic rehabilitation and assistive technologies market, capturing approximately 30% of the global revenue. Countries like Germany, France, and the United Kingdom have witnessed a surge in the adoption of these technologies, driven by the aging population and the rising incidence of disabilities. The region's well-established healthcare systems, coupled with favorable government initiatives and funding for research and development, have fostered the growth of the market. Additionally, the presence of skilled professionals and the increasing awareness of the benefits of robotic rehabilitation have contributed to market expansion.
Asia Pacific
The Asia Pacific region is experiencing rapid growth in the robotic rehabilitation and assistive technologies market, with a market share of around 20%. Countries like Japan, China, and India are witnessing an increasing demand for these technologies due to the rising geriatric population, the prevalence of chronic conditions, and improving healthcare infrastructure. The region's vast population, combined with favorable government initiatives and increasing investments in healthcare technology, have created lucrative opportunities for market players. Furthermore, the growing focus on patient-centric care and the adoption of advanced medical technologies have fueled the market's expansion in the Asia Pacific.
Latin America
Latin America accounts for a modest share of the robotic rehabilitation and assistive technologies market, estimated at around 6%. However, the region is anticipated to witness substantial growth in the coming years due to the increasing awareness of advanced rehabilitation solutions and the rising prevalence of disabilities. Countries like Brazil and Mexico are leading the way in adopting robotic rehabilitation and assistive technologies, driven by improving healthcare infrastructure and increasing healthcare expenditure. The presence of favorable government initiatives and the growing focus on patient care are expected to drive market growth in the region.
Middle East and Africa
The Middle East and Africa region holds the smallest share of the robotic rehabilitation and assistive technologies market, accounting for approximately 4% of global revenue. Limited access to healthcare services, a lack of awareness, and inadequate reimbursement policies have hindered market growth in this region. However, initiatives by healthcare organizations and governments to improve healthcare accessibility and promote the adoption of advanced rehabilitation solutions are expected to create growth opportunities in the future. Countries like Saudi Arabia and the United Arab Emirates are leading the way in adopting robotic rehabilitation and assistive technologies, driven by the increasing prevalence of disabilities and the focus on improving patient outcomes.
Future Outlook
- The robotic rehabilitation and assistive technologies market is poised for significant growth, driven by advancements in technology and increasing demand for innovative rehabilitation solutions.
- The integration of artificial intelligence and machine learning will lead to more personalized and effective rehabilitation interventions, optimizing patient outcomes.
- Home-based rehabilitation solutions will continue to gain traction, offering convenience and accessibility for patients recovering from injuries or managing chronic conditions.
- Virtual reality and augmented reality technologies will play a pivotal role in creating immersive and engaging therapy experiences, motivating patients, and enhancing rehabilitation efficacy.
- Wearable robotic exoskeletons will become increasingly prevalent, providing physical support and enhancing mobility for individuals with mobility impairments.
- Robotics for cognitive rehabilitation will see further development, aiding patients in recovering cognitive function following strokes, brain injuries, or neurological conditions.
- Regulatory frameworks will evolve to accommodate the growing market for robotic rehabilitation and assistive technologies, facilitating faster approval processes and market entry.
- Investments in workforce training and education will address the shortage of skilled personnel, ensuring optimal utilization and integration of robotic technologies into rehabilitation practice.
- Continued collaboration between industry stakeholders, policymakers, and healthcare providers will drive innovation and address challenges related to cost, reimbursement, and patient acceptance.
- Overall, the future outlook for the robotic rehabilitation and assistive technologies market is promising, with a focus on enhancing patient care, improving functional outcomes, and promoting inclusivity in healthcare delivery.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Rising Disability Prevalence
The global increase in the elderly population and the prevalence of disabilities due to chronic diseases and injuries are driving demand for advanced rehabilitation and assistive technologies. These demographics require tailored solutions to maintain independence and improve quality of life.
Technological Advancements in Robotics and AI
Continuous innovation in robotics, artificial intelligence, and sensor technologies has enabled the development of more effective, personalized, and user-friendly rehabilitation devices. These advancements are expanding the range of treatable conditions and improving patient outcomes.
Government Initiatives and Healthcare Investment
Supportive government policies, funding for R&D, and favorable reimbursement frameworks are encouraging the adoption of robotic rehabilitation and assistive technologies. These investments help reduce costs and increase accessibility for patients.
Shift Toward Home-Based and Remote Rehabilitation
The trend toward home-based care and tele-rehabilitation is increasing the demand for portable and remotely operated robotic devices. This shift offers greater convenience, reduces healthcare costs, and enables continuous patient engagement outside traditional clinical settings.
Focus on Comprehensive and Inclusive Patient Care
There is a growing emphasis on providing holistic rehabilitation solutions that address both physical and cognitive impairments. Robotic technologies are being integrated into multidisciplinary care models, supporting broader patient populations and promoting inclusivity in healthcare delivery.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the robotic rehabilitation and assistive technologies market between 2023 and 2032?
What factors are driving the growth of the robotic rehabilitation and assistive technologies market?
Who are the major players in the robotic rehabilitation and assistive technologies market?
How is the availability of the robotic rehabilitation and assistive technologies market expanding, and through what channels?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Orthopedics and Sports Medicine
- 1.2.2 Stroke
- 1.2.3 Cognitive and Motor Skills
- 1.2.4 Military Strength Training
- 1.2.5 Post Surgery
- 1.3 By Portability
- 1.3.1 Fixed Base
- 1.3.2 Mobile
- 1.4 By Product Type
- 1.4.1 Surveillance and Security
- 1.4.2 Humanoid
- 1.4.3 Physical Therapy and Rehabilitation
- 1.4.4 Assistive Robotics
- 1.4.5 Intelligent Prosthetics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
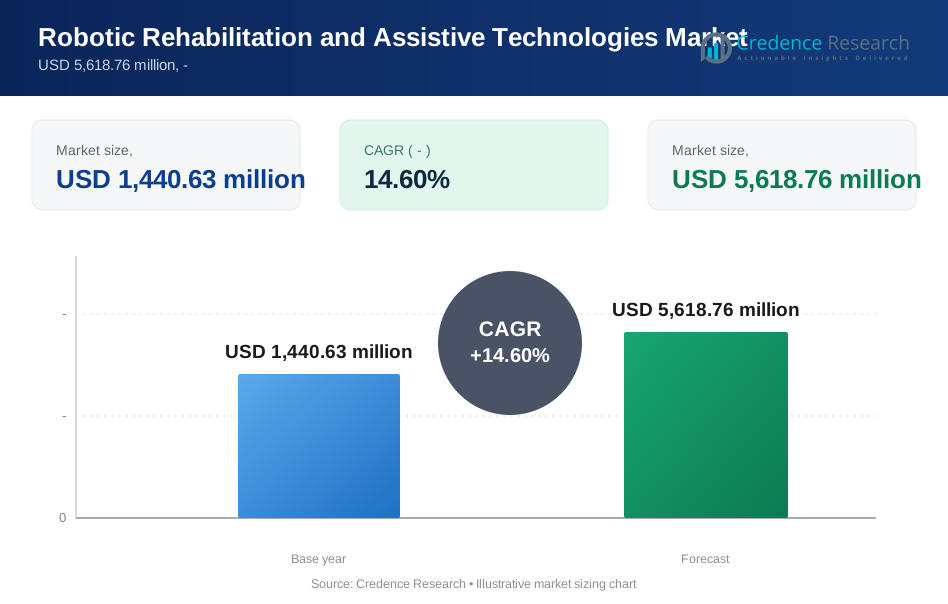
- 2.5.1 2023: USD 1,440.63 million → 2032: USD 5,618.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Robotic Rehabilitation and Assistive Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Robotic Rehabilitation and Assistive Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Robotic Rehabilitation and Assistive Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Robotic Rehabilitation and Assistive Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Robotic Rehabilitation and Assistive Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Robotic Rehabilitation and Assistive Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Robotic Rehabilitation and Assistive Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Robotic Rehabilitation and Assistive Technologies Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,440.63 million → 2032: USD 5,618.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Robotic Rehabilitation and Assistive Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Orthopedics and Sports Medicine
- 12.3.7.2 Stroke
- 12.3.7.3 Cognitive and Motor Skills
- 12.3.7.4 Military Strength Training
- 12.3.7.5 Post Surgery
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Portability - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fixed Base
- 12.4.7.2 Mobile
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Surveillance and Security
- 12.5.7.2 Humanoid
- 12.5.7.3 Physical Therapy and Rehabilitation
- 12.5.7.4 Assistive Robotics
- 12.5.7.5 Intelligent Prosthetics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Robotic Rehabilitation and Assistive Technologies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Robotic Rehabilitation and Assistive Technologies Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Robotic Rehabilitation and Assistive Technologies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Robotic Rehabilitation and Assistive Technologies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kinova, Inc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Instead Technologies Ltd.
- 18.4 ReWalk Robotics
- 18.5 AlterG, Inc
- 18.6 Bionik Laboratories Corp.
- 18.7 Health Robotics S.R.L.
- 18.8 Bioxtreme Robotics Rehabilitation
- 18.9 Mazor Robotics Ltd.
- 18.10 Incent Medical Holdings Limited
- 18.11 Cyberdyne INC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

