
Breast Imaging Technologies Market Overview:
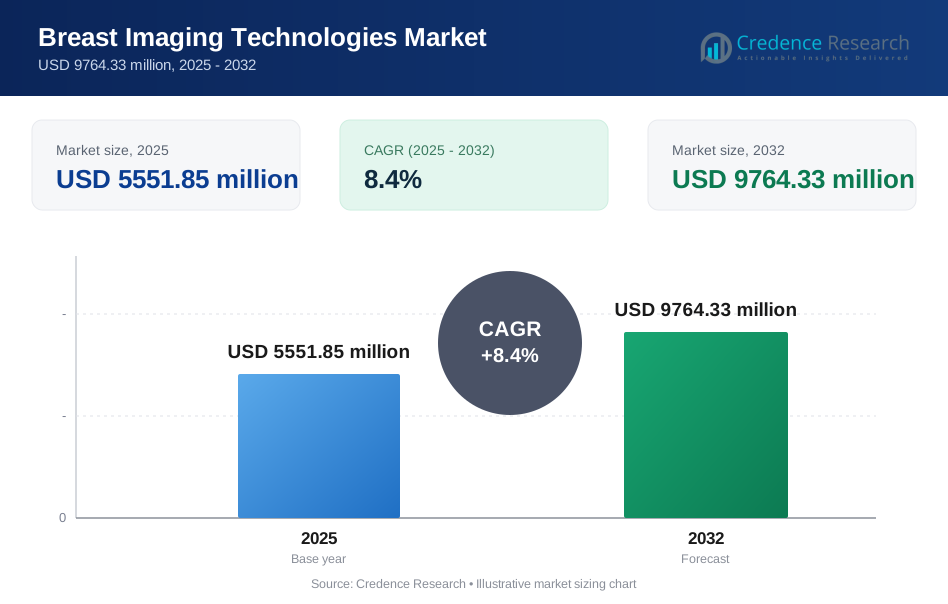
The global Breast Imaging Technologies Market size was estimated at USD 5551.85 million in 2025 and is expected to reach USD 9764.33 million by 2032, growing at a CAGR of 8.4% from 2025 to 2032. Growth momentum is primarily driven by sustained expansion of breast cancer screening volumes alongside faster adoption of advanced imaging workflows that improve lesion visualization, triage speed, and diagnostic confidence across screening and diagnostic pathways. North America continues to anchor adoption through mature reimbursement pathways and high penetration of digital mammography upgrades, with accelerating modernization across Asia Pacific supporting incremental unit installations and procedure growth.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Breast Imaging Technologies Market Size 2025 | USD 5551.85 million |
| Breast Imaging Technologies Market, CAGR | 8.4% |
| Breast Imaging Technologies Market Size 2032 | USD 9764.33 million |
Key Market Trends & Insights
- The Breast Imaging Technologies Market is projected to expand from USD 5551.85 million in 2025 to USD 9764.33 million by 2032, reflecting an 8.4% CAGR during 2025–2032.
- Ionizing Breast Imaging accounted for the largest share of 60.9% in 2025, supported by the scale of routine screening programs and the installed base of mammography systems.
- Mammography represented 37.6% share in 2025, maintaining leadership as the primary screening modality and a core focus area for technology upgrades.
- Hospitals held 61.1% share in 2025 due to integrated diagnostic-to-treatment workflows and centralized oncology care pathways.
- North America accounted for 36.4% share in 2025, reflecting high screening participation, established care pathways, and faster refresh cycles for advanced mammography platforms.

Segment Analysis
Breast Imaging Technologies Market demand is shaped by two structural factors: the need for high-throughput screening at population scale and the increasing requirement for problem-solving diagnostics in dense-breast and high-risk patient cohorts. Breast imaging buyers prioritize clinical accuracy, workflow efficiency, and lifecycle service coverage because imaging systems sit at the front of downstream biopsy, surgery, and therapy decisions. The Breast Imaging Technologies Market also reflects a clear shift toward integrated ecosystems that combine imaging hardware with decision support software, supporting earlier detection and more consistent reporting across care settings.
Technology adoption varies by clinical pathway, with screening workflows favoring high-throughput systems and diagnostic workflows favoring complementary modalities that improve sensitivity in complex cases. Non-ionizing techniques continue to gain visibility because non-ionizing techniques support supplemental imaging and risk-based pathways without ionizing exposure, particularly for dense breast tissue assessment and younger patient populations. The Breast Imaging Technologies Market benefits from increasing standardization of reporting and quality programs that encourage equipment upgrades and consistent image quality across sites.
By Technology Insights
Ionizing Breast Imaging accounted for the largest share of 60.9% in 2025. Ionizing Breast Imaging leadership is supported by the central role of mammography in organized screening programs and routine diagnostic workups. Ionizing Breast Imaging utilization is reinforced by established clinical pathways and repeat annual or biennial screening cycles. Ionizing Breast Imaging demand also benefits from ongoing platform upgrades that improve image quality and workflow efficiency.
By Modality Insights
Mammography accounted for the largest share of 37.6% in 2025. Mammography remains the default first-line modality for screening, creating consistent procedure volumes and stable equipment utilization. Mammography platform upgrades continue to attract investment because imaging providers aim to improve recall management and diagnostic confidence. Mammography also anchors multi-modality pathways by triggering follow-up ultrasound, breast MRI, or contrast-enhanced imaging for confirmatory evaluation.
By End User Insights
Hospitals accounted for the largest share of 61.1% in 2025. Hospitals concentrate diagnostic imaging demand due to integrated referral networks, oncology service lines, and higher-acuity diagnostic pathways. Hospitals also maintain broader multi-modality portfolios that support end-to-end clinical pathways from screening through staging and treatment monitoring. Hospitals benefit from centralized procurement and service contracts that improve uptime and standardize imaging quality across departments.
Breast Imaging Technologies Market Drivers
Expansion of screening volumes and early-detection programs
Breast Imaging Technologies Market growth is strongly supported by sustained emphasis on early detection, which expands screening participation and increases repeat imaging volume. Health systems continue to strengthen referral pathways from primary care into imaging, supporting stable baseline demand. Screening protocols also drive predictable system utilization and reinforce replacement cycles for aging equipment. The Breast Imaging Technologies Market benefits as screening programs increasingly seek higher-quality image acquisition and better recall management.
- For instance, in a study of 7,500 screening exams, Hologic’s Genius AI Detection solution correctly flagged almost 90% of 500 cancers already identified by radiologists and additionally detected roughly one‑third of cancers that had initially been interpreted as negative, improving recall management and follow‑up imaging workflows for participating centers.
Technology upgrades that improve diagnostic confidence and workflow
Breast Imaging Technologies Market adoption is supported by continuous technology refresh across mammography platforms and adjunct modalities. Imaging providers invest in upgrades that improve lesion visibility, standardize image quality, and reduce reading time. Workflow improvements support higher daily throughput and better scheduling utilization, which improves return on investment for imaging centers. The Breast Imaging Technologies Market also benefits from integration of software that supports consistent reporting and clinical decision-making.
Rising focus on dense-breast assessment and risk-based imaging
Breast Imaging Technologies Market expansion is reinforced by increasing clinical focus on dense-breast assessment and personalized imaging pathways. Dense breast tissue can reduce sensitivity in conventional screening, encouraging use of supplemental modalities. Risk-based imaging pathways increase demand for complementary approaches in high-risk cohorts, which supports a broader modality mix. The Breast Imaging Technologies Market gains incremental growth as care pathways expand beyond single-modality screening toward multi-modality evaluation.
- For instance, in a U.S. cohort of 498,855 women with dense breasts and more than 1.17 million negative mammograms, 2.8% of examinations were followed by supplemental ultrasound and 0.3% by MRI within one year, with onsite availability of ultrasound increasing use more than fourfold, underscoring how facility capabilities shape risk‑based imaging mixes.
Growth of diagnostic imaging capacity and service availability
Breast Imaging Technologies Market demand strengthens as imaging capacity expands across hospitals and independent diagnostic imaging centers. Capacity expansion is supported by investments in equipment installations, radiology staffing models, and service networks that reduce downtime. Private-sector expansion in emerging markets increases access to screening and diagnostic services, supporting procedure growth. The Breast Imaging Technologies Market also benefits from modernization initiatives that replace legacy systems with newer platforms.
Breast Imaging Technologies Market Challenges
Breast Imaging Technologies Market expansion is constrained by high capital costs and total cost of ownership, which can delay procurement cycles in budget-limited facilities. Installation requirements such as room shielding, cooling, and integration with hospital IT can add implementation complexity. Radiologist workload and shortages can limit effective utilization even when equipment is available. The Breast Imaging Technologies Market can also face uneven adoption when reimbursement and clinical guidelines vary across payers and geographies.
- For instance, one diagnostic imaging center cost analysis estimated 420,000 USD just for digital imaging and IT (300,000 USD for a digital X‑ray system and 120,000 USD for servers, network gear, and workstations), plus an additional 200,000 USD for PACS/RIS setup as a one‑time integration cost, underscoring the non‑equipment IT burden around imaging deployments.
Breast Imaging Technologies Market stakeholders also manage challenges related to interoperability and data integration across imaging systems, PACS, and reporting tools. Data governance requirements and cybersecurity expectations add operational burden, particularly for multi-site imaging networks. Variation in quality assurance practices can create performance differences across sites and affect patient experience. The Breast Imaging Technologies Market must also address patient comfort and access barriers that can reduce screening adherence in some populations.
Breast Imaging Technologies Market Trends and Opportunities
Breast Imaging Technologies Market differentiation increasingly centers on software-enabled workflows, including automation in image acquisition, triage support, and reporting consistency. Providers seek solutions that improve throughput and reduce variability in interpretation across readers and sites. Multi-modality pathway optimization creates opportunities for vendors that can offer integrated portfolios across mammography, ultrasound, and breast MRI. The Breast Imaging Technologies Market can capture incremental demand where platforms reduce recall burden and support earlier diagnostic resolution.
- For instance, a prospective implementation of a multi‑modal AI system integrating 2D and 3D mammography at a tertiary center reduced false‑positive recalls by 31.7% and radiologist workload by 43.8% while maintaining 100% sensitivity, directly addressing variability and efficiency challenges in high‑volume practices.
Breast Imaging Technologies Market growth opportunities also increase as emerging markets expand imaging infrastructure and adopt standardized screening practices. Diagnostic imaging centers can scale access by deploying efficient workflows and flexible staffing models. Partnerships between hardware vendors and software specialists create new commercialization models that bundle imaging equipment with decision support. The Breast Imaging Technologies Market can also benefit from service-led offerings that improve uptime, lifecycle performance, and predictable cost management.
Regional Insights
North America
Breast Imaging Technologies Market performance in North America is supported by mature screening infrastructure, high penetration of digital imaging, and consistent upgrade cycles. North America accounted for 36.4% share in 2025, reflecting strong procedure volumes and broad access to advanced imaging services. Demand is reinforced by integrated care pathways that link screening, diagnostics, and treatment. Competitive differentiation increasingly emphasizes workflow optimization and software integration across multi-site imaging networks.
Europe
Breast Imaging Technologies Market demand in Europe is supported by organized screening programs and steady modernization of imaging fleets across major countries. Europe accounted for 26.6% share in 2025, supported by ongoing replacement of legacy platforms and expanding access to adjunct imaging in diagnostic pathways. Regional variability remains driven by differences in reimbursement and procurement processes. Multi-modality adoption continues to expand in specialized centers focused on high-risk and complex case management.
Asia Pacific
Breast Imaging Technologies Market growth in Asia Pacific is supported by expanding imaging capacity, rising screening awareness, and increasing private-sector investment in diagnostic services. Asia Pacific accounted for 20.1% share in 2025, reflecting a large addressable population base and ongoing infrastructure upgrades. Demand is strengthened by deployment of new imaging sites in urban hubs and improved referral pathways. Adoption remains uneven across countries due to differences in access, reimbursement maturity, and workforce availability.
Latin America
Breast Imaging Technologies Market development in Latin America is supported by gradual expansion of diagnostic imaging networks and improving access in urban centers. Latin America accounted for 9.4% share in 2025, reflecting moderate penetration of screening services relative to higher-income regions. Private imaging providers play a key role in access expansion and modernization. Procurement cycles can be influenced by budget constraints and variability in public-sector screening coverage.
Middle East & Africa
Breast Imaging Technologies Market growth in Middle East & Africa is supported by targeted investments in tertiary hospitals and diagnostic centers, especially in higher-income subregions. Middle East & Africa accounted for 7.5% share in 2025, reflecting infrastructure constraints outside major cities and uneven screening coverage. Market development is supported by modernization of hospital systems and increasing emphasis on early diagnosis. Service availability and workforce limitations can affect utilization rates in under-resourced areas.
Competitive Landscape
Breast Imaging Technologies Market competition is characterized by platform differentiation in image quality, workflow efficiency, and integration with reading and reporting tools. Vendors compete through installed-base expansion, system upgrades, service coverage, and partnerships that combine hardware with decision support capabilities. Product portfolios that cover multiple modalities enable stronger positioning across screening, diagnostics, and high-risk pathways. Competitive intensity also increases as providers prioritize lifecycle uptime and consistent imaging performance across multi-site networks.
Hologic, Inc. focuses on mammography-centered ecosystems that combine acquisition platforms with software enhancements designed to improve reading confidence and workflow throughput. Hologic, Inc. positions offerings around screening reliability, upgradeability, and streamlined clinical operations across high-volume environments. Hologic, Inc. also reinforces adoption through service programs and integrated product roadmaps that support multi-year refresh cycles. Hologic, Inc. remains strongly aligned with screening-centric demand and platform modernization priorities.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Hologic, Inc.
- GE HealthCare
- Siemens Healthineers
- Koninklijke Philips N.V.
- FUJIFILM Holdings Corporation
- Canon Medical Systems Corporation
- Carestream Health
- Planmed Oy
- Aurora Imaging Technology, Inc.
- Dilon Technologies, Inc.
- Delphinus Medical Technologies, Inc.
- Lunit
- Kheiron Medical Technologies
- SonoCine, Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In April 2025, Hologic, Inc. announced new clinical data on its Genius AI Detection Solution for mammography at the Society of Breast Imaging Annual Symposium, highlighting improved radiologist efficiency while maintaining cancer detection accuracy in breast imaging workflows.
- In April 2025, GE HealthCare disclosed at the Society of Breast Imaging Symposium that its breast imaging portfolio now includes SmartMammo, an AI-powered SaaS solution commercially available for the Senographe Pristina platform to enhance mammography diagnostic accuracy and workflow, building on its ongoing collaboration with DeepHealth and RadNet.
- In January2025, Siemens Healthineers reported the first U.S. installation of its Mammomat B.brilliant mammography system at GRACE Breast Imaging & Medical Spa, introducing wide-angle tomosynthesis, UltraHD image reconstruction, and integrated biopsy and contrast-enhanced mammography capabilities for advanced breast imaging.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 5551.85 million |
| Revenue forecast in 2032 | USD 9764.33 million |
| Growth rate (CAGR) | 8.4% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Technology Outlook: Ionizing Breast Imaging, Non-Ionizing Breast Imaging; By Modality Outlook: Mammography, Breast Ultrasound, Breast MRI, Molecular Breast Imaging, Contrast-Enhanced Imaging, Thermography; By End User Outlook: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Research & Academic Institutes |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | 14 companies |
| No. of Pages | 326 |
By Segmentation
By Technology
- Ionizing Breast Imaging
- Non-Ionizing Breast Imaging
By Modality
- Mammography
- Breast Ultrasound
- Breast MRI
- Molecular Breast Imaging
- Contrast-Enhanced Imaging
- Thermography
By End User
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
- Research & Academic Institutes
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Screening Volumes and Early-Detection Programs
Sustained emphasis on early detection of breast cancer is increasing screening participation and repeat imaging volumes, driving predictable demand for breast imaging technologies and supporting regular equipment replacement cycles.
Technology Upgrades Improving Diagnostic Confidence and Workflow
Continuous investment in advanced imaging platforms and adjunct modalities enhances lesion visibility, standardizes image quality, and reduces reading time, making imaging centers more efficient and improving clinical outcomes.
Rising Focus on Dense-Breast Assessment and Risk-Based Imaging
Growing clinical attention to dense breast tissue and high-risk patient cohorts is increasing the adoption of supplemental imaging modalities, expanding the market beyond traditional mammography.
Growth of Diagnostic Imaging Capacity and Service Availability
Expansion of imaging infrastructure in hospitals and independent centers, especially in emerging markets, is increasing access to breast imaging services and supporting higher procedure volumes.
Integration of Software-Enabled Workflows and Decision Support
The adoption of AI and decision support software is streamlining image acquisition, triage, and reporting, reducing variability in interpretation and improving throughput, which is increasingly valued by providers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Breast Imaging Technologies Market in 2025 and the forecast for 2032?
What is the CAGR for the Breast Imaging Technologies Market during 2025–2032?
Which segment is the largest in the Breast Imaging Technologies Market in 2025?
What are the key factors driving growth in the Breast Imaging Technologies Market?
Who are the leading companies in the Breast Imaging Technologies Market?
Which region leads the Breast Imaging Technologies Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Diagnostic Imaging Centers
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Research & Academic Institutes
- 1.3 By Modality
- 1.3.1 Mammography
- 1.3.2 Breast Ultrasound
- 1.3.3 Breast MRI
- 1.3.4 Molecular Breast Imaging
- 1.3.5 Contrast-Enhanced Imaging
- 1.3.6 Thermography
- 1.4 By Technology
- 1.4.1 Ionizing Breast Imaging
- 1.4.2 Non-Ionizing Breast Imaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 5551.85 million → 2032: USD 9764.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Breast Imaging Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Breast Imaging Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Breast Imaging Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Breast Imaging Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Breast Imaging Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Breast Imaging Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Breast Imaging Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Breast Imaging Technologies Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 5551.85 million → 2032: USD 9764.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Breast Imaging Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Diagnostic Imaging Centers
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Research & Academic Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Modality - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mammography
- 12.4.7.2 Breast Ultrasound
- 12.4.7.3 Breast MRI
- 12.4.7.4 Molecular Breast Imaging
- 12.4.7.5 Contrast-Enhanced Imaging
- 12.4.7.6 Thermography
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ionizing Breast Imaging
- 12.5.7.2 Non-Ionizing Breast Imaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Breast Imaging Technologies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Breast Imaging Technologies Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Breast Imaging Technologies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Breast Imaging Technologies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hologic, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE HealthCare
- 18.4 Siemens Healthineers
- 18.5 Koninklijke Philips N.V.
- 18.6 FUJIFILM Holdings Corporation
- 18.7 Canon Medical Systems Corporation
- 18.8 Carestream Health
- 18.9 Planmed Oy
- 18.10 Aurora Imaging Technology, Inc.
- 18.11 Dilon Technologies, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

