
Market Overview:
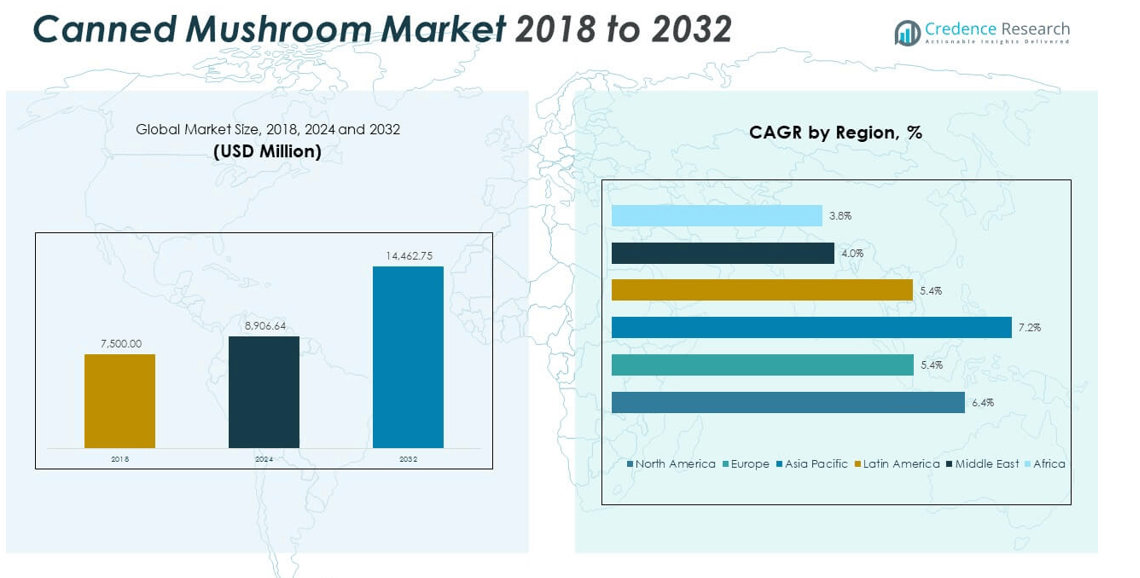
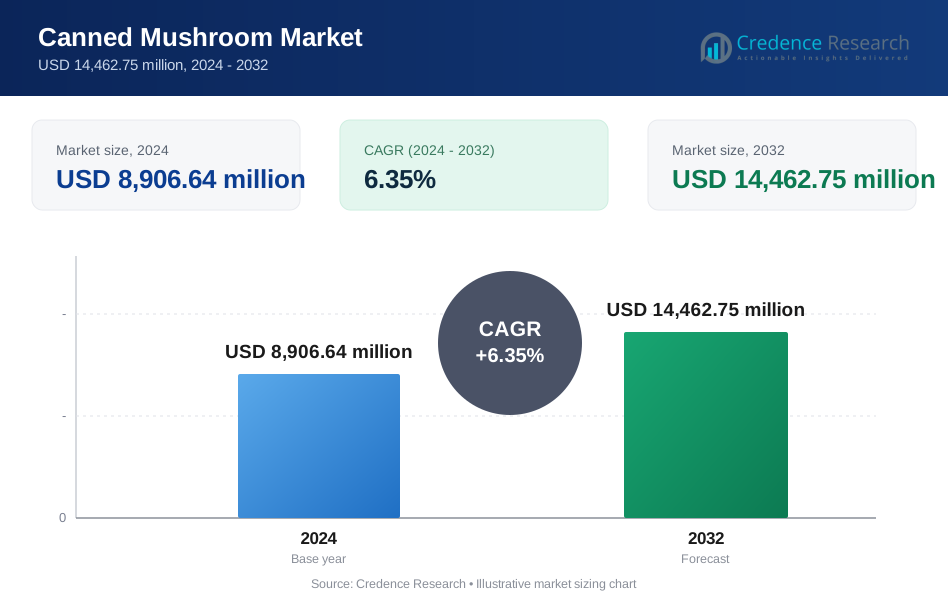
The Global Canned Mushroom Market size was valued at USD 7,500 million in 2018, reached USD 8,906.64 million in 2024, and is anticipated to reach USD 14,462.75 million by 2032, at a CAGR of 6.35% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canned Mushroom Market Size 2024 | USD 8,906.64 million |
| Canned Mushroom Market, CAGR | 6.35% |
| Canned Mushroom Market Size 2032 | USD 14,462.75 million |
Demand grows because consumers want longer shelf-life and easy-to-use food options. Brands expand supply chains to support fast retail turnover. Rising use in ready meals, sauces, and soups boosts steady uptake. Food processors value stable texture and flavor in bulk formats. Urban lifestyle changes raise interest in quick cooking ingredients. Hotels and restaurants use canned mushrooms to keep stock stable. Manufacturers improve sorting and slicing to meet quality needs. These drivers shape product adoption in many segments.
North America leads due to strong processed food consumption and wide retail access. Europe follows close behind with high use across commercial kitchens and home cooking. Asia Pacific emerges fast as China and India show rising interest in affordable packaged foods. Latin America gains momentum because local producers improve canning capacity. The Middle East and Africa grow steadily as urban markets expand. Each region advances based on local diets, supply strength, and affordability trends.
Market Insights:
- The Global Canned Mushroom Market reached USD 7,500 million in 2018, increased to USD 8,906.64 million in 2024, and is projected to hit USD 14,462.75 million by 2032, advancing at a CAGR of 6.35% driven by strong retail and foodservice demand.
- Asia Pacific (40.00%), North America (27.87%), and Europe (20.86%) hold the largest shares due to strong consumption patterns, wide retail penetration, and reliable processing capacities across these mature and high-volume markets.
- Asia Pacific, the fastest-growing region, holds a 00% share supported by strong production strength, expanding urban household consumption, and rising adoption of packaged ingredients across major economies.
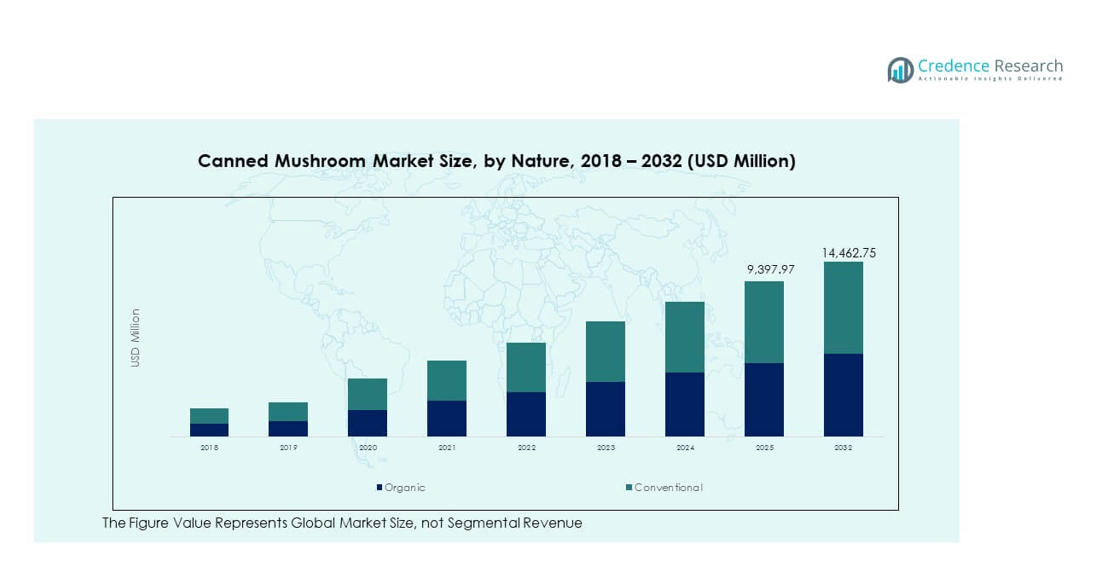
- Conventional products dominate segment distribution in the chart, contributing roughly 70% of total revenue due to broad availability and lower pricing across global retail channels.
- Organic variants account for nearly 30%, gaining steady momentum from health-focused consumers and premium product lines supported by clean-label preferences.
Market Drivers:
Strong Growth In Shelf-Stable Food Demand Driven By Busy Lifestyles
The Global Canned Mushroom Market benefits from rising preference for convenient food formats. Consumers want longer storage time without quality loss. Retail chains push ready-to-use ingredients for daily cooking. Processors improve preservation methods to keep texture stable during heat cycles. It supports faster meal preparation for urban households. Food service operators pick bulk packs to maintain steady supply. Brands highlight consistent taste that helps repeat purchase. Strong interest in packaged vegetables lifts overall volume growth. Product reliability helps secure strong adoption across many channels.
- For instance, Bonduelle processes about 750,000 tonsof products (canned, frozen, and fresh processed) each year across its global network of facilities, supporting strong production volumes.
Rising Penetration Of Processed Ingredients Across Foodservice And Industrial Kitchens
Foodservice operators increase use of canned mushrooms to maintain menu consistency. Hotels and caterers prefer uniform cuts that reduce preparation time. Industrial kitchens expand orders to support large batch cooking. It ensures stable output during peak hours. Product demand grows in sauces, frozen meals, and ready-mix dishes. Processors value predictable moisture levels for controlled formulation. Cold-chain gaps in many regions strengthen the role of canned inputs. Rising tourism widens foodservice activity and pushes ingredient use. Manufacturers gain repeat contracts from high-volume buyers.
- For instance, Sysco supplies more than 725,000 customer locations worldwide, reinforcing strong demand for processed and shelf-stable food ingredients across foodservice operations.
Improved Production Capabilities And Stronger Supply Chain Efficiency
Producers expand processing lines to support higher throughput. Modern canning systems help cut waste and raise grading precision. It improves product safety and supports longer shelf life. Contract growers expand mushroom cultivation to meet rising orders. Large firms invest in automated slicing and sorting modules. Supply networks improve delivery timelines across key regions. Retailers push stable packaged options to reduce spoilage risk. Consumer trust grows due to strict quality control rules. Stronger farm-to-factory coordination helps secure steady distribution.
Growing Use In Packaged Foods, Quick Meals, And Institutional Menus
Product adoption rises due to strong demand for ready meals and instant cooking formats. Food processors include canned mushrooms in pasta kits, pizza toppings, and mixed vegetables. It supports consistent taste during reheating steps. Institutional buyers such as schools and hospitals prefer safe, preset ingredients. Manufacturers offer varied cuts that match diverse cooking needs. New flavor variants increase shelf appeal across retail chains. Rising dual-income households drive interest in faster meal options. Commercial kitchens reduce workload through pre-processed inputs. Stable pricing strengthens long-term procurement decisions.
Market Trends:
Higher Adoption Of Value-Added Canned Mushroom Varieties And Premium Cuts
The Global Canned Mushroom Market observes rising demand for premium sliced and whole-button formats. Brands roll out higher-grade selections for gourmet dishes. Retail shelves expand space for specialty blends that support diverse cuisines. It helps buyers choose options that suit recipe styles. Food processors introduce cleaner labels to attract health-focused groups. More firms reduce sodium levels to match regulatory trends. Brine innovations help strengthen flavor retention. Growing interest in premium cooking pushes upscale variants. Product diversification supports wider consumer reach.
- For instance, Greenyard’s Long Fresh segment (comprising the Prepared and Frozen divisions) produces over 800,000 tonnes of products annually for both retail and industrial buyers. The prepared division specializes in products such as classic preserved items in cans or jars, along with dips, soups, and sauces, while the frozen division is a market leader in frozen pure-plant food, including various vegetable products.
Stronger Movement Toward Eco-Friendly Packaging And Responsible Sourcing
Producers shift toward recyclable cans to support sustainability goals. Buyers value packaging that reduces environmental load. It aligns with rising awareness of responsible consumption. Mushrooms sourced from controlled farms gain stronger traction. Traceability programs expand transparency across supply chains. Retailers highlight eco-labels to attract conscious shoppers. Global brands commit to greener production processes. Growing interest in ethical food choices reinforces this shift. Pack designs evolve to support better disposal practices.
- For instance, Crown Holdings reports that the high recyclability of steel contributes to its sustainability credentials; however, the actual recycled content of its new steel food cans is generally much lower than the high steel recycling rateachieved in regions like Europe (which was 82% in 2023).
Rise Of E-Commerce Platforms Supporting Wider Product Visibility
Online stores add more canned mushroom variants to meet diverse kitchen needs. Many buyers prefer doorstep delivery for heavier canned goods. It increases product reach in semi-urban regions. Digital platforms allow brands to market recipe ideas and usage tips. Subscription models help ensure repeat ordering. Retailers track consumer preferences using digital analytics. Search visibility boosts sales for smaller brands. Delivery networks expand access in remote zones. E-commerce growth pushes stronger brand competition.
Expansion Of Multi-Cuisine Cooking Culture Across Global Households
The Global Canned Mushroom Market gains support from rising interest in global recipes at home. Households try Asian, Italian, and fusion dishes that rely on mushroom ingredients. Television shows and cooking apps spread new meal ideas. It improves awareness of recipe versatility. Packaged mushrooms help new cooks manage complex steps. Changing food habits raise kitchen experimentation. Retail chains reinforce this trend through themed promotions. Home chefs value stable texture during long cooking cycles. Mushroom products fit well across many cuisines.
Market Challenges Analysis:
High Dependence On Raw Mushroom Supply And Strong Competition From Fresh Produce
The Global Canned Mushroom Market faces risk from volatile fresh mushroom harvests. Weather shifts reduce farm output and raise procurement strain. It pushes processors to manage stock more carefully. Fresh mushrooms remain a strong substitute in premium segments. Retail buyers often compare quality between formats. Some consumers view canned items with limited preference for flavor depth. Supply chain disruptions slow delivery speed. Producers must invest in stronger sourcing networks. Competition pressures raise marketing and branding needs.
Growing Concerns Related To Additives, Taste Perception, And Changing Health Preferences
Consumers focus on clean labels and minimal processing, which creates mixed sentiment. The Global Canned Mushroom Market responds by reducing preservatives and improving brine formulas. It needs to meet expectation for better texture and natural flavor. Health-focused shoppers lean toward fresh produce categories. Regulatory scrutiny pushes firms to adopt strict standards. Brands must balance taste retention with long storage goals. Misperceptions about canned food safety still affect some regions. Shifts in diet patterns create ongoing adaptation challenges.
Market Opportunities:
Expansion Into Ready-Meal Partnerships And Growth In Institutional Supply Chains
Large food processors adopt canned mushrooms for pasta kits, rice bowls, and meal bases. The Global Canned Mushroom Market gains new momentum from joint developments. It supports faster formulation cycles for commercial products. Institutional kitchens need stable and safe ingredients to meet rising meal volume. Brands can build long-term supply deals with hospitals and schools. New packaging sizes help match specific kitchen needs. Product reliability ensures strong repeat purchase rates. Wider menu diversification in foodservice opens new contract opportunities. Strong linkages with processors support multi-year demand.
Rising Demand In Emerging Economies And Growth Of Retail Modernization
Urban centers in Asia, Africa, and Latin America expand shelf space for canned vegetables. The Global Canned Mushroom Market unlocks new growth due to rising packaged-food use. It fits well with busy urban routines and limited cold-chain reach. Retail modernization raises visibility for private label lines. Local producers invest in new canning units to meet rising orders. Online grocery shopping helps smaller brands reach remote homes. Stable pricing supports household budget decisions. Expanding middle-income groups create steady consumption patterns. Product penetration grows with strong awareness campaigns.
Market Segmentation Analysis:
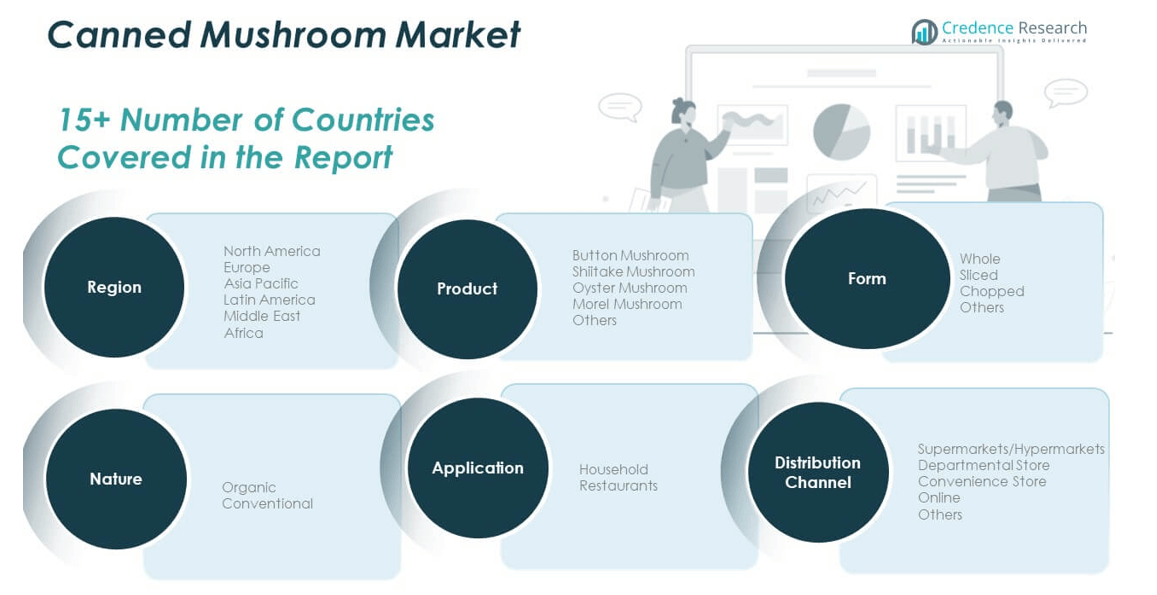
By Product Type The Global Canned Mushroom Market includes whole mushrooms, sliced forms, diced cuts, and specialty blends tailored for diverse culinary needs. Whole mushrooms remain preferred in foodservice due to strong visual appeal. Sliced formats support faster preparation in large kitchens. Diced variants help processors maintain uniform texture in ready meals. Specialty blends gain traction in gourmet mixes and private labels. It benefits from steady demand across retail and industrial buyers. Growth aligns with rising use in sauces, frozen meals, and snack formulations.
- For instance, Monterey Mushrooms distributes its processed mushroom products to more than 10,000 retail and foodservice outlets across North America, supporting broad application across prepared food categories.
By Application Key uses span food, beverages, personal care, pharmaceuticals, and tabletop categories. Food applications dominate due to broad use in pasta, noodles, soups, and pizzas. Beverage makers explore mushroom extracts for niche products. Personal care brands adopt mushroom derivatives for hydration claims. Pharmaceutical firms use extracts for functional benefits. Tabletop packs help households store long-lasting ingredients. Product flow grows with wider menu diversification in foodservice.
- For instance, Bonduelle supplies its processed vegetable portfolio to major food manufacturers across Europe and North America, supporting widespread use across sauces, ready meals, and institutional catering.
By Form Powder, liquid, and crystal forms support varied workflows. Powder formats help processors in seasoning mixes. Liquid bases suit sauces and broths. Crystal variants hold value in specialty blends. It supports manufacturers needing flexible integration.
By Nature Organic and conventional options meet distinct consumer preferences. Organic variants attract health-focused groups, while conventional formats stay dominant in bulk channels. Demand depends on pricing and availability shifts.
By Sales Channel Offline stores remain strong due to easy access in supermarkets and wholesale chains. Online sales gain traction through home delivery and broader product visibility. This shift supports smaller brands entering new regions.
Segmentation:
By Product Type
- Stevia
- Palm Sugar
- Coconut Sugar
- Honey
- Maple Syrup
- Monk Fruit Sugar
- Agave Syrup
- Lucuma Fruit Sugar
- Molasses
- Natural Sweetener Blends
By Application
- Food
- Beverages
- Personal Care
- Pharmaceuticals
- Tabletop Sweeteners
By Form
- Powder
- Liquid
- Crystals
By Nature
- Organic
- Conventional
By Sales Channel
- Offline Sales
- Online Sales
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Canned Mushroom Market size was valued at USD 2,122.50 million in 2018 to USD 2,481.34 million in 2024 and is anticipated to reach USD 4,022.12 million by 2032, at a CAGR of 6.4 during the forecast period. The North America region holds 27.87% share of the Global Canned Mushroom Market due to strong processed food consumption. Retail chains push consistent demand for ready-use vegetables. Foodservice providers rely on canned formats to support stable menu planning. It benefits from high adoption in pasta, pizza, and soup categories. Manufacturers strengthen distribution networks to improve delivery timelines. Consumers prefer long shelf-life products for home storage. Restaurants increase bulk purchases to reduce prep workload. Growing interest in convenient ingredients supports steady regional expansion.
Europe
The Europe Canned Mushroom Market size was valued at USD 1,640.25 million in 2018 to USD 1,856.79 million in 2024 and is anticipated to reach USD 2,812.32 million by 2032, at a CAGR of 5.4 during the forecast period. Europe accounts for 20.86% share of the Global Canned Mushroom Market due to strong culinary integration. Food processors use canned mushrooms extensively in meal kits. Retail buyers value consistent quality for home cooking. It gains support from high demand in Italian and French cuisines. Manufacturers follow strict safety rules that support consumer trust. Private labels expand shelf presence with low-cost options. Institutional kitchens maintain large orders for standard dishes. Regional supply chains operate with high efficiency to sustain output.
Asia Pacific
The Asia Pacific Canned Mushroom Market size was valued at USD 2,917.50 million in 2018 to USD 3,561.28 million in 2024 and is anticipated to reach USD 6,165.48 million by 2032, at a CAGR of 7.2 during the forecast period. Asia Pacific holds 40.00% share of the Global Canned Mushroom Market due to strong production and high consumption. China and India drive volume growth with rising packaged food use. Urban families demand convenient ingredients for daily meals. It supports wide use in noodles, stir-fries, and snacks. Local processors increase output to serve export markets. Retail modernization improves visibility across major cities. Foodservice chains expand menu options that include mushroom-based dishes. Strong agricultural capacity sustains raw material availability.
Latin America
The Latin America Canned Mushroom Market size was valued at USD 493.50 million in 2018 to USD 580.62 million in 2024 and is anticipated to reach USD 877.45 million by 2032, at a CAGR of 5.4 during the forecast period. Latin America represents 6.52% share of the Global Canned Mushroom Market with growing interest in packaged vegetables. Brazil and Mexico lead consumption through large urban centers. Foodservice operators adopt canned formats to control ingredient waste. It supports rising demand in fusion dishes and ready meals. Retail chains expand imported product shelves to meet consumer needs. Local processors enhance capacity to reduce dependence on imports. Awareness of convenient food choices increases across middle-income groups. Stable pricing helps maintain buyer confidence in key markets.
Middle East
The Middle East Canned Mushroom Market size was valued at USD 177.00 million in 2018 to USD 188.76 million in 2024 and is anticipated to reach USD 256.07 million by 2032, at a CAGR of 4.0 during the forecast period. The Middle East accounts for 2.12% share of the Global Canned Mushroom Market with steady growth driven by foodservice expansion. Hospitality projects boost procurement of canned ingredients. Urban households seek long-life products to reduce frequent shopping needs. It supports greater use in fast-food and casual dining formats. Importers hold key influence due to limited regional production. Retailers increase assortment of global mushroom brands. Rising tourism boosts hotel kitchen consumption. Consumption patterns shift toward convenient meal components across major cities.
Africa
The Africa Canned Mushroom Market size was valued at USD 149.25 million in 2018 to USD 237.84 million in 2024 and is anticipated to reach USD 329.31 million by 2032, at a CAGR of 3.8 during the forecast period. Africa holds 2.67% share of the Global Canned Mushroom Market with growth supported by expanding retail networks. Urban centers adopt packaged vegetables to address storage challenges. Foodservice businesses rely on canned mushrooms for predictable supply. It helps bridge gaps caused by irregular fresh produce availability. Importers dominate distribution across major markets. Consumers slowly increase interest in convenient cooking ingredients. Government programs supporting food security improve access to packaged goods. Wider supermarket penetration supports long-term demand growth.
Key Player Analysis:
- DuPont (US)
- ADM (Archer Daniels Midland) (US)
- Tate & Lyle PLC (UK)
- Cargill (US)
- Ingredion Incorporated (US)
- Roquette Frères (France)
- FoodChem International Corporation (China)
- PureCircle Ltd (US)
- MacAndrews & Forbes Holdings Inc (Merisant) (US)
- Ecogreen Oleochemicals (Indonesia)
- Pyure Brands LLC (US)
- Stevia Hub India (India)
- Suminter India Organics (India)
- Stevia Biotech Pvt Ltd (India)
- The Real Stevia Company (Sweden)
- Sweetly Stevia USA (UK)
- XiliNat (Mexico)
- Fooditive B.V. (Netherlands)
- Saganà Association (Switzerland)
- Hearthside Food Solutions LLC (US)
Competitive Analysis:
The Global Canned Mushroom Market features strong competition among multinational processors, regional suppliers, and vertically integrated farming groups. Firms compete on product quality, sourcing capability, and distribution reach. It focuses on efficiency in slicing, grading, and brining techniques to secure bulk contracts. Large brands expand retail visibility through private label collaborations. Foodservice buyers influence procurement due to high volume purchases. Market entrants push niche variants to gain share in gourmet and specialty segments. Strong logistics support helps established companies maintain steady output. Competitive intensity rises with broader adoption of value-added mushroom formats.
Recent Developments:
- In August 2025, FoodChem participated in Fi South America 2025 in São Paulo, Brazil, showcasing innovative food ingredient solutions including gelatin, collagen, collagen peptides, carrageenan, konjac gum, and sugar substitutes at booth B-80.
- In June 2025, FoodChem and Foodmate showcased their innovative solutions at the Hi&Fi Asia-China 2025 and CPHI & PMEC China 2025 exhibitions in Shanghai, featuring upgraded Instant Gelatin, FoodGel™ (edible gelatin), CapGel™ (pharmaceutical gelatin), collagen peptides, carrageenan, konjac gum, and compound sweeteners.
- In May 2025, Roquette completed the acquisition of IFF Pharma Solutions, marking a major step forward in the company's value-creation journey. With this acquisition, and following that of Qualicaps in 2023, Roquette decisively strengthened its position as a key player in the health industry by integrating IFF Pharma Solutions' expertise and innovative product portfolio, positioning Roquette as the pharmaceutical industry's go-to partner for the development of drug delivery solutions.
- In March 2025, FoodChem launched its new product, Instant Gelatin, at the 2025 FIC Exhibition held from March 17-19 at NECC Shanghai. The product launch conference was held on March 18, featuring instant gelatin with 5-second dissolution capability in room-temperature water, addressing market demand for efficiency in the food ingredients industry.
Report Coverage:
The research report offers an in-depth analysis based on product type, application, form, nature, and sales channel segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising interest in convenient, shelf-stable vegetables will expand mainstream demand.
- Increasing retail penetration of private label products will strengthen competition.
- Wider adoption of canned ingredients in foodservice kitchens will push bulk supply growth.
- Automation upgrades in processing units will raise output consistency and lower waste.
- Growth in value-added mushroom variants will support diversification across segments.
- Online grocery platforms will improve market access for regional and emerging brands.
- Stronger sustainability goals will encourage investment in improved packaging formats.
- Improved farm productivity will support steady raw material availability for processors.
- Urban population growth will sustain interest in long-life cooking ingredients.
- Broader international distribution networks will unlock new consumption opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canned Mushroom Market?
At what Compound Annual Growth Rate is the Global Canned Mushroom Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Canned Mushroom Market?
What are the key segments within the Canned Mushroom Market?
What are some challenges faced by the Canned Mushroom Market?
Who are the major players in the Canned Mushroom Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canned Mushroom Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canned Mushroom Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,906.64 million → 2032: USD 14,462.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canned Mushroom Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canned Mushroom Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canned Mushroom Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canned Mushroom Market Drivers
- 3.3 Canned Mushroom Market Restraints & Challenges
- 3.4 Canned Mushroom Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canned Mushroom Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canned Mushroom Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canned Mushroom category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canned Mushroom Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canned Mushroom Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canned Mushroom market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canned Mushroom Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canned Mushroom Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canned Mushroom Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canned Mushroom (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canned Mushroom Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canned Mushroom Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canned Mushroom Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canned Mushroom Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canned Mushroom Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canned Mushroom Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canned Mushroom Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canned Mushroom Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canned Mushroom Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
