
Cannula Market Overview:
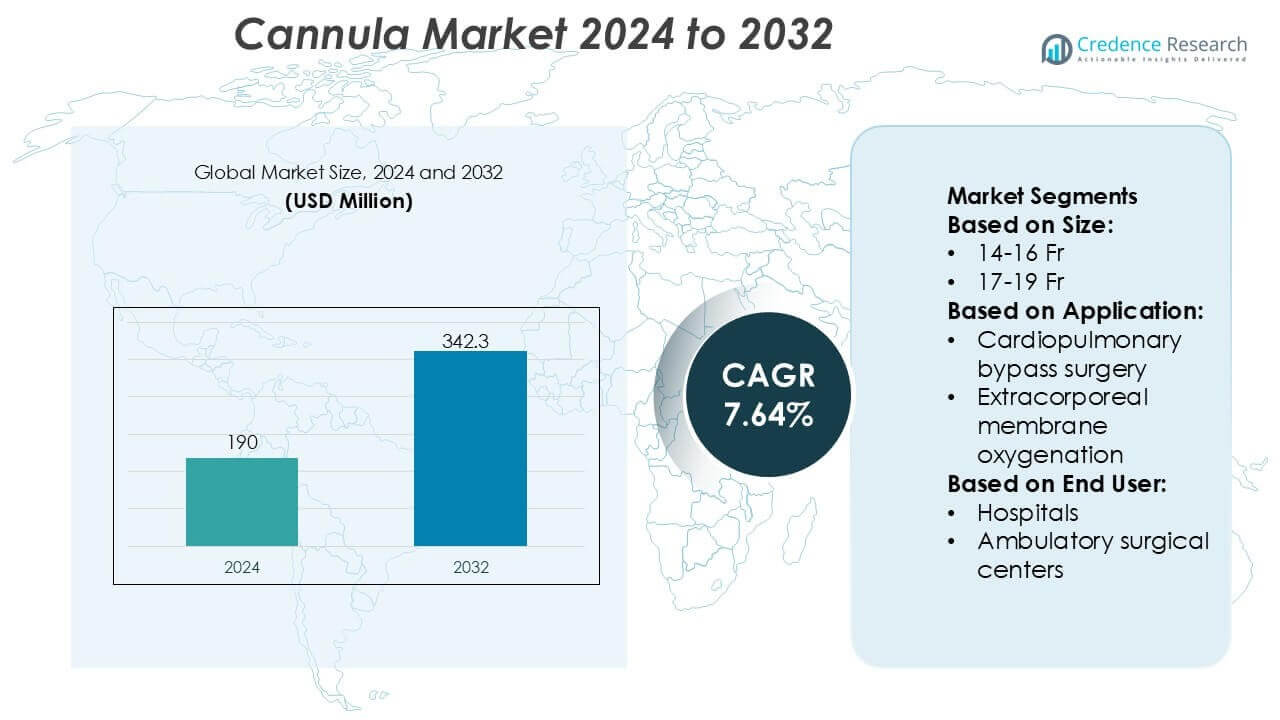
Cannula Market size was valued USD 190 million in 2024 and is anticipated to reach USD 342.3 million by 2032, at a CAGR of 7.64% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cannula Market Size 2024 | USD 190 million |
| Cannula Market, CAGR | 7.64% |
| Cannula Market Size 2032 | USD 342.3 million |
Cannula Market Insights
- Rising volumes of cardiopulmonary bypass and extracorporeal membrane oxygenation procedures are key growth drivers, with cardiopulmonary bypass applications accounting for an estimated ~55% share due to routine cardiac surgeries.
- Ongoing trends include the adoption of biocompatible materials, thin-wall designs, and improved flow dynamics to enhance safety, reduce hemolysis, and support complex and long-duration procedures.
- Competitive dynamics are shaped by continuous product innovation, strict regulatory compliance, clinician training programs, and long-term supply relationships with hospitals and cardiac centers.
- Regionally, North America leads the global market with an exact 38% share, supported by advanced cardiovascular infrastructure, high procedure volumes, and strong reimbursement frameworks, while Asia-Pacific shows faster growth momentum.
Cannula Market Segmentation Analysis:
By Size
The cannula market by size shows clear differentiation driven by clinical indication, patient anatomy, and flow requirements. The 20–22 Fr segment dominates the size-based landscape, accounting for an estimated 26% market share, as it offers an optimal balance between adequate flow rates and reduced vascular trauma in adult cardiothoracic and extracorporeal procedures. Strong adoption is supported by its compatibility with standard cardiopulmonary bypass circuits and ECMO setups. Smaller sizes (14–19 Fr) maintain steady demand in pediatric and minimally invasive procedures, while larger sizes (26–36 Fr) are selectively used in high-flow, complex cardiac surgeries.
- For instance, Freelife Medical GmbH engineers arterial and venous cannulae in the 20–22 Fr range with optimized tip geometry supporting flow rates above 5.5 liters per minute at clinically acceptable pressure gradients, reinforced thin-wall tubing with wall thickness below 0.6 millimeters, and laser-etched depth markers at 5-millimeter intervals to improve placement accuracy and procedural safety.
By Application
By application, cardiopulmonary bypass (CPB) surgery represents the leading segment, holding approximately 48% of the total market share, supported by the high global volume of open-heart procedures. Cannulas used in CPB are optimized for stable high-flow perfusion, hemodynamic control, and reduced hemolysis, reinforcing their clinical preference. Extracorporeal membrane oxygenation (ECMO) follows as a fast-growing segment due to rising incidence of acute respiratory failure and cardiac shock. Other applications, including trauma and specialized vascular procedures, contribute incremental demand driven by procedural diversification.
- For instance, Medtronic’s high-performance cannulas, such as the Bio-Medicus™ NextGen and EOPA™ (Elongated One-Piece Arterial) series, are engineered to support blood flow rates up to 7 liters per minute, providing sufficient perfusion for large adult patients during CPB and long-term ECLS.
By End User
In terms of end users, hospitals dominate the cannula market with an estimated 64% market share, reflecting their role as primary centers for complex cardiac surgeries, ECMO deployment, and critical care interventions. High procedural volumes, availability of specialized surgical teams, and access to advanced perfusion infrastructure sustain hospital dominance. Ambulatory surgical centers are gradually expanding adoption, particularly for less complex cardiovascular and minimally invasive procedures, supported by cost-efficiency initiatives. Other end users, including specialty clinics and research centers, account for a smaller but stable share driven by niche procedural requirements.
Key Growth Drivers
Rising Volume of Cardiovascular and Critical Care Procedures
The cannula market benefits directly from the growing number of cardiovascular surgeries, extracorporeal membrane oxygenation (ECMO) procedures, and critical care interventions worldwide. An aging population, increasing prevalence of cardiac disorders, and higher survival rates of complex surgeries continue to drive procedural volumes. Hospitals increasingly rely on high-performance cannulas that offer improved flow dynamics, reduced hemolysis, and enhanced patient safety. This sustained rise in procedure demand supports consistent procurement cycles and reinforces long-term market expansion across both adult and pediatric care settings.
- For instance, Andocor’s high-performance adult cannulae, particularly the Flex Line and Venous series, are engineered and validated to sustain continuous blood flow exceeding 6 liters per minute.
Advancements in Cannula Design and Material Technologies
Continuous innovation in cannula design significantly accelerates market growth. Manufacturers focus on biocompatible materials, thin-wall constructions, kink-resistant shafts, and optimized tip geometries to improve clinical outcomes and ease of use. Enhanced coatings that reduce thrombogenicity and improve blood compatibility further increase adoption. These technological advancements enable clinicians to perform complex procedures with greater precision and reduced complication risks, strengthening physician confidence and driving replacement demand for advanced cannula systems across surgical and intensive care applications.
- For instance, Getinge AB has developed arterial and venous cannulas using medical-grade polyurethane reinforced with embedded wire coils designed to maintain lumen integrity at bend radii below 25 millimeters, supports continuous flow performance above 6 liters per minute in cardiopulmonary bypass configurations, and applies biocompatible surface treatments validated through internal testing to significantly reduce platelet adhesion during extended blood-contact durations exceeding 6 hours.
Expansion of Healthcare Infrastructure in Emerging Economies
Rapid healthcare infrastructure development in emerging markets is a key growth driver for the cannula market. Governments and private healthcare providers are investing heavily in cardiac care units, advanced surgical centers, and critical care facilities. Improved access to specialized procedures increases the demand for essential consumables such as cannulas. Additionally, growing medical tourism and expanding reimbursement coverage in select regions further stimulate procurement volumes, supporting steady market growth beyond traditionally dominant developed healthcare systems.
Key Trends & Opportunities
Shift Toward Minimally Invasive and Percutaneous Procedures
A notable trend in the cannula market is the increasing preference for minimally invasive and percutaneous procedures. Clinicians seek cannulas that support smaller access points while maintaining optimal flow performance. This shift creates opportunities for manufacturers to develop low-profile, flexible cannulas designed for minimally invasive techniques. As hospitals aim to reduce patient trauma, shorten recovery times, and lower overall treatment costs, demand for specialized cannulas aligned with these procedural trends continues to rise.
- For instance, BD (Becton Dickinson) has engineered the BD Venflon™ Pro Safety IV Cannula with BD Vialon™ polyurethane material that softens in-vein up to 70 percent to support longer dwell times and lower mechanical phlebitis risk, incorporates BD Instaflash™ needle technology for immediate visual confirmation of vessel entry, and offers catheter lengths such as a 22 gauge, 45 mm configuration delivering approximately 31 mL/min gravity flow while its passive safety shield fully encapsulates the needle tip upon withdrawal to reduce accidental needlestick exposures.
Growing Adoption of ECMO and Advanced Life Support Therapies
The expanding use of ECMO and advanced life support therapies presents a strong growth opportunity. Cannulas designed specifically for prolonged support, stable positioning, and high flow efficiency are increasingly required in intensive care units. Rising awareness of ECMO benefits in respiratory and cardiac failure cases encourages hospitals to strengthen their capabilities. This trend supports demand for premium cannula products with enhanced durability, secure fixation features, and compatibility with modern life support systems.
- For instance, LivaNova plc has developed specialized cardiopulmonary cannulae such as the ProtekSolo™ arterial cannula available in sizes 15 Fr × 17 cm and 17 Fr × 17 cm with wire-reinforced tubing to preserve lumen integrity at extended lengths, and venous return cannulae like the dual-stage 32/40 Fr model with an effective length of 41 cm, designed to support consistent drainage performance in high-flow bypass circuits.
Increasing Focus on Pediatric and Neonatal Care Solutions
There is a growing emphasis on pediatric and neonatal cannula solutions as survival rates improve for critically ill infants and children. This creates opportunities for highly specialized, size-specific cannulas that minimize vascular trauma and support delicate physiological conditions. Manufacturers investing in precision-engineered pediatric portfolios can address this niche yet expanding segment, benefiting from higher clinical value perception and strong demand from specialized pediatric care centers.
Key Challenges
Stringent Regulatory Requirements and Compliance Burden
The cannula market faces challenges from stringent regulatory frameworks governing medical devices. Compliance with evolving quality standards, clinical validation requirements, and post-market surveillance obligations increases development timelines and costs. Smaller manufacturers may struggle to meet these requirements, limiting innovation speed. Delays in regulatory approvals can also slow product launches and restrict market entry, particularly in regions with complex approval pathways, thereby impacting overall market competitiveness.
Pricing Pressure and Hospital Cost Containment
Intensifying pricing pressure poses a significant challenge for cannula manufacturers. Hospitals and healthcare systems increasingly emphasize cost containment, often favoring bundled procurement and competitive tendering processes. This environment limits pricing flexibility, even for technologically advanced products. Manufacturers must balance innovation investments with cost efficiency while maintaining product quality. Sustained margin pressure may affect smaller players disproportionately and intensify competition, especially in high-volume, standardized cannula segments.
Regional Analysis
North America
North America leads the global cannula market with an estimated 38% market share, supported by high procedure volumes in cardiovascular surgery, ECMO, and critical care. Advanced healthcare infrastructure, widespread adoption of technologically advanced cannulas, and strong reimbursement frameworks drive consistent demand. Hospitals and specialized cardiac centers prioritize high-performance cannulas with improved flow efficiency and biocompatible materials, reinforcing premium product adoption. The strong presence of established manufacturers, continuous product innovation, and early uptake of advanced life-support technologies further strengthen North America’s dominant position in the global cannula market.
Europe
Europe accounts for approximately 28% of the global cannula market, driven by a well-established public healthcare system and rising prevalence of cardiovascular and respiratory diseases. Countries such as Germany, France, and the UK show strong demand due to increasing surgical volumes and expanding ECMO capabilities. Strict regulatory standards encourage the adoption of high-quality, clinically validated cannula products. Additionally, growing investments in hospital modernization and critical care infrastructure support steady replacement demand, positioning Europe as a mature yet innovation-driven regional market.
Asia-Pacific
Asia-Pacific represents around 22% market share and is the fastest-growing region in the cannula market. Rapid expansion of healthcare infrastructure, increasing access to advanced surgical procedures, and rising awareness of critical care therapies drive growth. Countries such as China, India, and Japan are witnessing higher cardiovascular disease incidence, leading to increased procedural volumes. Government initiatives to improve tertiary care facilities and growing medical tourism further stimulate demand. Cost-effective cannula offerings and rising adoption of advanced devices support strong regional growth momentum.
Latin America
Latin America holds an estimated 7% share of the global cannula market, supported by gradual improvements in healthcare access and increasing investments in cardiac and critical care services. Brazil and Mexico are key contributors due to expanding hospital networks and rising surgical procedure volumes. Although budget constraints limit rapid adoption of premium devices, demand for reliable and cost-effective cannulas remains strong. Ongoing public-private partnerships and incremental upgrades in critical care infrastructure are expected to support moderate but steady market growth.
Middle East & Africa
The Middle East & Africa region accounts for roughly 5% of the global cannula market, reflecting developing healthcare systems and uneven access to advanced procedures. Gulf countries drive regional demand through significant investments in advanced hospitals and cardiac care centers. In contrast, parts of Africa experience slower adoption due to limited infrastructure and funding constraints. However, increasing government healthcare spending, expansion of tertiary care facilities, and rising awareness of life-support therapies are gradually improving cannula demand across the region.
Cannula Market Segmentations:
By Size:
- 14-16 Fr
- 17-19 Fr
By Application:
- Cardiopulmonary bypass surgery
- Extracorporeal membrane oxygenation
By End User:
- Hospitals
- Ambulatory surgical centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The cannula market players such as Freelife Medical GmbH, Medtronic, plc., Andocor, Nipro Corp., Surgical Holdings, Getinge AB, BD, LivaNova plc, Fresenius Medical Care. The cannula market is characterized by a moderately consolidated competitive environment in which manufacturers compete primarily on product reliability, clinical performance, and regulatory compliance. Market participants focus on advancing material quality, flow dynamics, and structural integrity to support demanding applications such as cardiopulmonary bypass and extracorporeal life support. Continuous design refinements, including thin-wall constructions, kink resistance, and atraumatic tip configurations, are widely adopted to enhance procedural safety and clinician control. Companies also emphasize manufacturing consistency, adherence to international quality standards, and comprehensive validation to secure long-term contracts with hospitals. In addition, strategic investments in R&D, expansion of global distribution networks, and alignment with evolving surgical protocols enable suppliers to maintain competitiveness while addressing rising procedure volumes and increasingly complex clinical requirements.
Key Player Analysis
- Freelife Medical GmbH
- Medtronic, plc.
- Andocor
- Nipro Corp.
- Surgical Holdings
- Getinge AB
- BD
- LivaNova plc
- Fresenius Medical Care
- Edward Lifesciences
Recent Developments
- In May 2025, Liquidia Corporation announced that the U.S. Food and Drug Administration (FDA) approved YUTREPIA™ (treprostinil) inhalation powder, a dry powder prostacyclin analog, for adults with Pulmonary Arterial Hypertension (PAH) and Pulmonary Hypertension associated with Interstitial Lung Disease (PH-ILD) to improve exercise ability, marking a significant advancement for treating these rare cardiopulmonary conditions with an easy-to-use, deep-lung delivery device.
- In September 2024, Shockwave Medical has expanded its U.S. peripheral intravascular lithotripsy (IVL) portfolio by introducing an enhanced catheter, designed for treating calcified arterial lesions.
- In April 2024, The FDA has announced a recall of Arrow QuickFlash Radial Artery Catheterization Kits due to potential device malfunctions that could pose safety risks. This highlights the importance of stringent quality standards in arterial cannula manufacturing to ensure reliability and safety in procedures like arterial line placement and catheterization.
- In March 2024, Merck, known as MSD outside of the United States and Canada, announced today that the U.S. Food and Drug Administration (FDA) has approved sotatercept-csrk (U.S. Brand Name: WINREVAIR, for injection, 45mg, 60mg) for the treatment of adults with pulmonary arterial hypertension. WINREVAIR is a breakthrough biologic for this rare, progressive disease.
Report Coverage
The research report offers an in-depth analysis based on Size, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing volumes of cardiac and extracorporeal procedures will continue to drive steady demand for advanced cannula solutions.
- Manufacturers will prioritize improved flow efficiency and reduced hemolysis to support complex and long-duration procedures.
- Adoption of biocompatible and kink-resistant materials will accelerate to enhance patient safety and clinical outcomes.
- Product designs will increasingly focus on ease of insertion and precise placement to support minimally invasive techniques.
- Integration of cannulas with next-generation perfusion and ECMO systems will strengthen system-level compatibility.
- Expanding aging populations will increase the need for cardiovascular and critical care interventions.
- Regulatory emphasis on quality assurance will push manufacturers toward higher manufacturing and validation standards.
- Emerging markets will offer growth opportunities through expanding surgical infrastructure and training programs.
- Customization of cannula sizes and configurations will gain importance to address diverse patient anatomies.
- Ongoing innovation and clinical collaboration will remain essential to sustain competitive positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Volume of Cardiovascular and Critical Care Procedures
The increasing number of cardiac surgeries, ECMO procedures, and critical care interventions globally is directly boosting demand for cannulas, as hospitals require reliable, high-performance devices to support these complex procedures.
Advancements in Cannula Design and Material Technologies
Continuous innovation in biocompatible materials, thin-wall constructions, and optimized flow dynamics is enhancing clinical outcomes, reducing complications, and driving replacement demand for advanced cannula systems.
Expansion of Healthcare Infrastructure in Emerging Economies
Rapid development of cardiac care units and critical care facilities in emerging markets is increasing access to specialized procedures, thereby raising the need for essential consumables like cannulas.
Shift Toward Minimally Invasive and Percutaneous Procedures
Growing clinical preference for minimally invasive techniques is fueling demand for low-profile, flexible cannulas that support smaller access points while maintaining optimal flow, aligning with trends to reduce patient trauma and recovery times.
Growing Adoption of ECMO and Advanced Life Support Therapies
The expanding use of ECMO and advanced life support in intensive care units is creating strong demand for cannulas designed for prolonged support, high flow efficiency, and compatibility with modern life support systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cannula Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cannula Market projected to grow between 2024 and 2032?
Which Cannula Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cannula Market?
Who are the leading companies in the Cannula Market?
Which region commanded the largest share of the Cannula Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Size
- 1.2.1 14-16 Fr
- 1.2.2 17-19 Fr
- 1.2.3 20-22 Fr
- 1.2.4 23-25 Fr
- 1.2.5 26-36 Fr
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Ambulatory surgical centers
- 1.3.3 Specialty clinics
- 1.3.4 Research centers
- 1.4 By Application
- 1.4.1 Cardiopulmonary bypass surgery
- 1.4.2 Extracorporeal membrane oxygenation
- 1.4.3 Trauma and vascular procedures
- 1.4.4 Minimally invasive procedures
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 190 million → 2032: USD 342.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cannula Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cannula Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cannula Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cannula Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cannula Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cannula Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cannula Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cannula Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 190 million → 2032: USD 342.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cannula Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Size - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 14-16 Fr
- 12.3.7.2 17-19 Fr
- 12.3.7.3 20-22 Fr
- 12.3.7.4 23-25 Fr
- 12.3.7.5 26-36 Fr
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Ambulatory surgical centers
- 12.4.7.3 Specialty clinics
- 12.4.7.4 Research centers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cardiopulmonary bypass surgery
- 12.5.7.2 Extracorporeal membrane oxygenation
- 12.5.7.3 Trauma and vascular procedures
- 12.5.7.4 Minimally invasive procedures
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cannula End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cannula Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cannula Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cannula Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Freelife Medical GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic, plc.
- 18.4 Andocor
- 18.5 Nipro Corp.
- 18.6 Surgical Holdings
- 18.7 Getinge AB
- 18.8 BD (Becton Dickinson)
- 18.9 LivaNova plc
- 18.10 Fresenius Medical Care
- 18.11 Edward Lifesciences
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

