
Market Overview
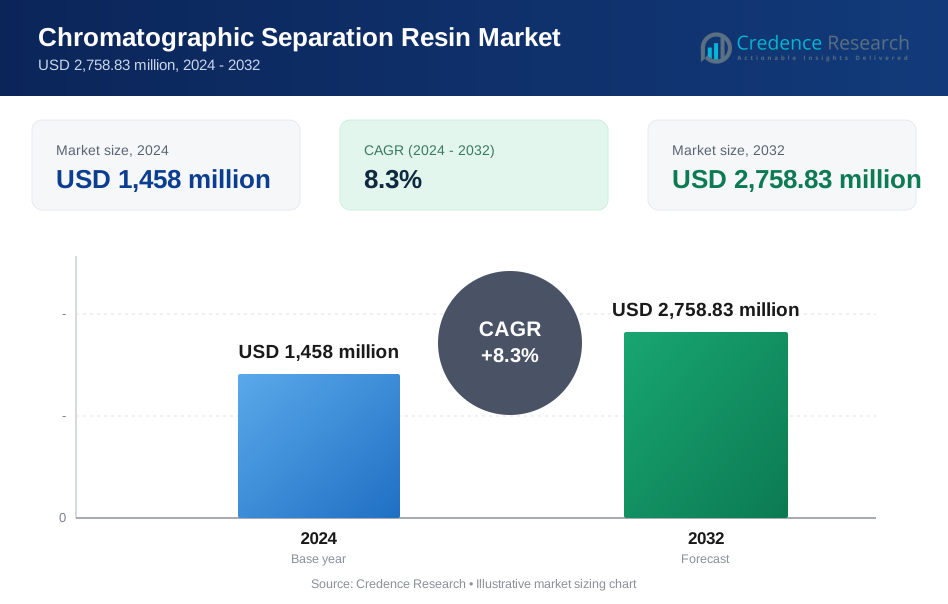
The chromatographic separation resin market was valued at USD 1,458 million in 2024 and is projected to reach USD 2,758.83 million by 2032, expanding at a compound annual growth rate (CAGR) of 8.3% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
|
|
USD 1,458 million |
| Chromatographic Separation Resin Market , CAGR | 8.3% |
| Chromatographic Separation Resin Market Size 2032 | USD 2,758.83 million |
The chromatographic separation resin market is led by a group of well-established global players, including Merck KGaA, Thermo Fisher Scientific Inc., GE Healthcare, Tosoh Bioscience, Bio-Rad Laboratories, Agilent Technologies, Pall Corporation, Avantor Performance Materials Inc., and Mitsubishi Chemical Corporation, all of which compete on resin chemistry innovation, binding efficiency, and lifecycle performance. These companies maintain strong positions through extensive bioprocess portfolios and long-term relationships with biopharmaceutical manufacturers. North America is the leading region, accounting for approximately 38% of the global market, supported by high biologics production volumes, advanced downstream processing infrastructure, and early adoption of high-performance affinity and synthetic resins. Europe and Asia Pacific follow, driven by biosimilar expansion and manufacturing scale-up.

Market Insights
- The chromatographic separation resin market was valued at USD 1,458 million in 2024 and is projected to reach USD 2,758.83 million by 2032, growing at a CAGR of 8.3% during the forecast period.
- Market growth is primarily driven by rising biologics and biosimilar production, where chromatography remains the core downstream purification method; synthetic resins dominate the product type segment due to higher durability and scalability, while affinity chromatography leads the technology segment owing to its high selectivity in monoclonal antibody purification.
- Key market trends include the adoption of high-capacity resins, intensified bioprocessing, and single-use chromatography systems; biopharmaceutical companies account for the largest end-user share, supported by continuous commercial-scale manufacturing and pipeline expansion of advanced biologics.
- Competitive intensity remains high, with leading players focusing on resin performance, ligand innovation, and long lifecycle stability, while regional and mid-tier suppliers gain traction through cost-optimized offerings, particularly for biosimilar manufacturing.
- Regionally, North America holds about 38% market share, followed by Europe at 28% and Asia Pacific at 22%, with Asia Pacific showing the fastest growth due to expanding biomanufacturing capacity in China, India, and South Korea.
Market Segmentation Analysis:
By Product Type:
Within the chromatographic separation resin market, synthetic resins represent the dominant sub-segment, accounting for the majority of market share due to their superior mechanical strength, higher binding capacity, and consistent batch-to-batch performance. Synthetic polymer- and silica-based resins are widely preferred in industrial-scale bioprocessing, particularly for monoclonal antibody and recombinant protein purification. Their chemical stability enables repeated cleaning-in-place (CIP) cycles, reducing operational costs for manufacturers. Growing biopharmaceutical production volumes, along with the shift toward high-throughput and continuous chromatography processes, continues to drive strong demand for synthetic chromatographic resins globally.
- For instance, Cytiva’s MabSelect™ PrismA protein A resin is qualified for more than 200 CIP cycles using 0.5 molar sodium hydroxide and delivers dynamic binding capacities of up to 80 milligrams of IgG per milliliter of resin at industrial flow rates, while Merck’s Eshmuno® A resin supports operating pressures of 3 bar and enables linear flow velocities exceeding 300 centimeters per hour without loss of resolution.
By Technology:
By technology, affinity chromatography holds the leading market share, driven by its exceptional selectivity and high recovery yields in downstream bioprocessing. Protein A affinity resins, in particular, are extensively used for monoclonal antibody purification, which remains a core segment of biologics manufacturing. The dominance of affinity chromatography is reinforced by rising approvals of antibody-based therapeutics and biosimilars, as well as increasing adoption of single-use and intensified purification workflows. While ion exchange and hydrophobic interaction chromatography remain essential polishing steps, affinity-based techniques continue to anchor primary capture stages in modern biomanufacturing.
- For instance, Repligen’s OPUS® pre-packed Protein A columns are qualified for a maximum hardware pressure limit of up to 4 bar (for smaller columns) or 3 bar (for larger columns) and typically support linear flow rates of up to 200 centimeters per hour in a standard platform process, enabling efficient cycle times in single-use antibody capture.
By End User:
Among end users, biopharmaceutical companies constitute the dominant sub-segment, capturing the largest share of chromatographic separation resin consumption. These organizations rely heavily on chromatography resins for large-scale purification of biologics, vaccines, and cell- and gene-based therapies. Expansion of in-house manufacturing capacity, coupled with sustained investment in biologics pipelines, underpins resin demand from this segment. While clinical research organizations and academic institutes contribute through process development and early-stage research, biopharmaceutical manufacturers remain the primary revenue drivers due to their continuous, high-volume, and GMP-compliant production requirements.
Key Growth Drivers
Expansion of Biopharmaceutical Manufacturing
The rapid expansion of global biopharmaceutical manufacturing is a primary growth driver for the chromatographic separation resin market. Increasing development and commercialization of monoclonal antibodies, recombinant proteins, vaccines, and advanced biologics require highly efficient downstream purification processes, where chromatography remains the backbone technology. Rising prevalence of chronic diseases, oncology indications, and autoimmune disorders has accelerated biologics pipelines, prompting manufacturers to scale production capacities. Large biopharmaceutical firms are investing in new manufacturing facilities and upgrading existing plants, directly increasing consumption of high-performance chromatographic resins. Additionally, regulatory emphasis on product purity and consistency reinforces reliance on chromatography-based separations, ensuring sustained demand for resins across both commercial production and late-stage clinical manufacturing.
- For instance, Samsung Biologics’ fourth manufacturing plant in Incheon added 256,000 liters of bioreactor capacity, bringing its total installed capacity to 620,000 liters, a scale that necessitates large-volume Protein A and ion-exchange resin deployment for commercial antibody production, while Lonza’s Portsmouth, New Hampshire facility expansion incorporated 2,000-liter single-use bioreactors configured for intensified downstream processing supported by high-capacity affinity and mixed-mode resins.
Growth of Biosimilars and Cost-Optimized Therapeutics
The global push toward biosimilars and cost-optimized biologic therapies significantly drives demand for chromatographic separation resins. As patent expirations open markets for biosimilar versions of high-value biologics, manufacturers are intensifying process optimization to improve yields and reduce purification costs. Chromatography resins with higher binding capacities, longer lifetimes, and improved chemical stability are increasingly adopted to support economically viable biosimilar production. Emerging markets, in particular, are witnessing rapid biosimilar development, expanding resin demand beyond traditional biopharma hubs. This cost-efficiency focus strengthens the adoption of advanced synthetic resins that enable robust, repeatable purification cycles under stringent regulatory standards.
- For instance, Merck’s Eshmuno® A resin has demonstrated dynamic binding capacities of 80 milligrams of IgG per milliliter at industrial flow rates and supports more than 200 cleaning-in-place cycles with sodium hydroxide, enabling multi-year reuse in biosimilar antibody campaigns, while Purolite’s Praesto® Jetted A50 resin is manufactured using controlled jetting technology that delivers uniform bead sizes of approximately 50 micrometers and maintains performance over 100 alkaline cleaning cycles in commercial-scale operations.
Increasing Adoption of Advanced Therapeutic Modalities
The rise of advanced therapeutic modalities, including cell therapies, gene therapies, and nucleic acid–based products, is creating new growth avenues for chromatographic separation resins. These complex products require specialized purification strategies to ensure safety, potency, and regulatory compliance. Chromatographic techniques such as ion exchange, size exclusion, and affinity chromatography are increasingly tailored for viral vectors, plasmid DNA, and mRNA purification. As clinical pipelines for advanced therapies expand and transition toward commercialization, demand for customized and high-resolution resins continues to grow. This shift toward complex biologics strengthens long-term resin demand across both established and emerging therapeutic platforms.
Key Trends & Opportunities
Shift Toward Single-Use and Intensified Bioprocessing
A notable trend in the chromatographic separation resin market is the shift toward single-use and intensified bioprocessing systems. Biopharmaceutical manufacturers are adopting disposable chromatography formats and smaller, high-capacity columns to improve flexibility and reduce cleaning validation requirements. High-performance resins that deliver greater productivity per cycle support intensified processing strategies, enabling higher output within smaller facility footprints. This trend creates opportunities for resin suppliers to develop products optimized for rapid processing, scalability, and compatibility with single-use systems. Growing adoption of modular biomanufacturing facilities further reinforces this opportunity across both developed and emerging markets.
- For instance, Tosoh Bioscience reports that its TOYOPEARL® MX-Trp-650M affinity resin achieves IgG binding capacities exceeding 80 g/L, supporting higher productivity per cycle in reduced footprints.
Rising Demand for Customized and Application-Specific Resins
Increasing process complexity is driving demand for customized and application-specific chromatographic resins. Biopharmaceutical companies seek resins tailored to specific molecules, such as antibodies, viral vectors, or nucleic acids, to maximize selectivity and recovery. Resin suppliers are responding by offering ligand-modified, mixed-mode, and high-resolution products designed for targeted purification challenges. This customization trend enables closer collaboration between resin manufacturers and end users, creating long-term supply relationships. As biologics pipelines diversify, the need for specialized resin solutions presents significant growth opportunities for innovation-focused suppliers.
- For instance, Sartorius has co-developed application-specific ion-exchange media such as the Sartobind® Q membrane, which offers DNA binding capacities of roughly 10 mg per mL for viral vector purification workflows."
Key Challenges
High Cost of Chromatography Resins and Process Economics
The high cost of chromatographic separation resins remains a key challenge, particularly for large-scale manufacturing. Affinity resins, especially those used for monoclonal antibody purification, represent a substantial portion of downstream processing expenses. Frequent resin replacement, cleaning requirements, and validation costs can strain production budgets, especially for biosimilar and emerging-market manufacturers. Cost sensitivity may limit adoption of premium resins in price-competitive environments, prompting manufacturers to seek alternative purification strategies. Balancing performance improvements with cost-effectiveness remains a critical challenge for both resin suppliers and end users.
Technical Complexity and Process Optimization Constraints
Technical complexity associated with chromatography-based purification presents another significant challenge. Selecting the optimal resin, chromatography mode, and operating conditions requires extensive process development and validation. Variability in feedstock composition and product characteristics can impact resin performance and reproducibility. Additionally, scaling laboratory processes to commercial production often introduces operational inefficiencies and yield losses. These challenges necessitate skilled expertise and increase development timelines, particularly for emerging therapeutic modalities. Overcoming these constraints requires continued innovation in resin design, process modeling, and integrated downstream solutions.
Regional Analysis
North America
North America holds the largest share of the chromatographic separation resin market at approximately 38%, driven by the strong presence of leading biopharmaceutical manufacturers and advanced bioprocessing infrastructure. The United States dominates regional demand due to high biologics production volumes, extensive R&D activity, and early adoption of advanced purification technologies. Large-scale monoclonal antibody manufacturing and growing commercialization of cell and gene therapies sustain resin consumption. Additionally, strict regulatory requirements for product purity reinforce reliance on chromatography-based separations, supporting steady demand for high-performance synthetic and affinity resins across commercial and clinical manufacturing facilities.
Europe
Europe accounts for around 28% of the global chromatographic separation resin market, supported by a well-established biopharmaceutical industry and strong biosimilar development activity. Countries such as Germany, Switzerland, the UK, and France host major biologics manufacturing hubs and contract development organizations. The region benefits from increasing investments in biomanufacturing capacity and a robust regulatory framework that emphasizes quality and consistency. Growth in biosimilars and vaccines continues to drive demand for cost-efficient and high-capacity resins. Collaborative research initiatives between industry and academic institutes further strengthen long-term market adoption across Europe.
Asia Pacific
Asia Pacific represents approximately 22% of the chromatographic separation resin market and is the fastest-growing regional segment. Rapid expansion of biopharmaceutical manufacturing in China, India, South Korea, and Japan is driving strong resin demand. The region benefits from increasing biosimilar production, rising healthcare investments, and supportive government initiatives to localize biologics manufacturing. Cost-competitive production capabilities encourage adoption of advanced chromatographic resins for large-scale purification. Growing outsourcing to regional contract manufacturing organizations further accelerates resin consumption, positioning Asia Pacific as a key growth engine in the global market.
Latin America
Latin America holds an estimated 7% share of the global chromatographic separation resin market, supported by gradual growth in biopharmaceutical production and public-sector vaccine manufacturing. Brazil and Mexico are the primary contributors, driven by government-backed biologics programs and increasing partnerships with global pharmaceutical companies. While the region relies partly on imported resins, rising local manufacturing capabilities are improving adoption rates. Expansion of clinical research activities and regional efforts to strengthen healthcare self-sufficiency support steady market growth, although adoption remains moderate compared to North America and Europe.
Middle East & Africa
The Middle East & Africa region accounts for roughly 5% of the chromatographic separation resin market, reflecting its early-stage biopharmaceutical manufacturing base. Growth is driven by increasing investments in healthcare infrastructure, vaccine production, and localized pharmaceutical manufacturing, particularly in the Gulf Cooperation Council countries. Government initiatives to reduce reliance on imports and improve biologics availability are supporting gradual adoption of chromatography technologies. While market penetration remains limited, expanding research capabilities and international collaborations are expected to enhance long-term demand for chromatographic resins across the region.
Market Segmentations:
By Product Type:
- Natural
- Synthetic
By Technology:
- Affinity Chromatography
- Anion Exchange Chromatography
- Cation Exchange Chromatography
- Size Exclusion Chromatography
- Hydrophobic Interaction Chromatography
By End User:
- Biopharmaceutical Companies
- Clinical Research Organizations
- Academic Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The chromatographic separation resin market features a competitive landscape dominated by established life science and specialty materials companies with strong technological expertise and global distribution networks. Leading players compete on resin performance, ligand chemistry, binding capacity, and lifecycle durability to meet the stringent demands of biopharmaceutical purification. Continuous innovation in synthetic and affinity-based resins supports differentiation, particularly for monoclonal antibody and advanced therapy applications. Strategic investments in R&D, capacity expansion, and process-specific resin development remain central to competitive positioning. Companies also strengthen market presence through long-term supply agreements with biopharmaceutical manufacturers and contract development organizations. Additionally, partnerships and collaborations with research institutes enable early-stage adoption of new resin technologies. While global players maintain a dominant position, emerging regional suppliers are increasing competition by offering cost-optimized alternatives, particularly for biosimilar manufacturing and high-volume purification workflows.
Key Player Analysis
- Merck KGaA
- Thermo Fisher Scientific Inc.
- Tosoh Bioscience
- Agilent Technologies
- Bio-Rad Laboratories
- GE Healthcare
- Pall Corporation
- Avantor Performance Materials Inc.
- Mitsubishi Chemical Corporation
- Waters Corporation
Recent Developments
- In October 2025, Merck announced the signing of a definitive agreement to acquire the chromatography business of JSR Life Sciences, which includes JSR’s advanced Protein A resin technologies such as Amsphere™ A3 and Amsphere™ A+ Protein A resins, enhancing Merck’s downstream purification portfolio to support more efficient antibody purification workflows in biopharmaceutical manufacturing.
- In December 2024, Agilent introduced the Infinity III LC Series platforms at the HUPO 2024 World Congress, which, although primarily instrumentation, support advanced liquid chromatography separations and underscore Agilent’s expansion of high-performance LC systems that enhance compatibility with modern resin-based workflows in analytical and preparative applications.
- In July 2024,Tosoh Bioscience announced strategic initiatives in chromatographic solutions focusing on its liquid chromatography resins and downstream processing media, reflecting ongoing enhancement of its TOYOPEARL® and TSKgel resin technologies for biomolecule purification at various scales.
Report Coverage
The research report offers an in-depth analysis based on Product type, Technology, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will continue to rise as global biopharmaceutical pipelines expand, particularly for monoclonal antibodies, vaccines, and recombinant proteins.
- Advanced synthetic and affinity-based resins will gain wider adoption due to their higher binding capacity and longer operational lifecycles.
- Biosimilar manufacturing will increasingly prioritize cost-efficient and high-throughput chromatographic resin solutions.
- Customized and application-specific resins will see stronger uptake to address molecule-specific purification challenges.
- Single-use and intensified chromatography formats will reshape resin design and deployment strategies.
- Cell and gene therapy commercialization will create new demand for specialized ion exchange and size exclusion resins.
- Continuous bioprocessing adoption will drive the need for resins compatible with extended and stable operation.
- Asia Pacific will emerge as a major growth engine supported by expanding biomanufacturing infrastructure.
- Collaboration between resin suppliers and biopharmaceutical manufacturers will deepen to optimize downstream workflows.
- Ongoing innovation in ligand chemistry and resin matrices will remain central to long-term competitive differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Biopharmaceutical Manufacturing
The rapid growth of global biopharmaceutical manufacturing, especially for monoclonal antibodies, recombinant proteins, and vaccines, is driving demand for chromatographic separation resins as these products require highly efficient downstream purification processes.
Growth of Biosimilars and Cost-Optimized Therapeutics
Increasing development and commercialization of biosimilars is intensifying the need for high-capacity, durable, and cost-effective chromatographic resins to support economically viable large-scale purification under stringent regulatory standards.
Adoption of Advanced Therapeutic Modalities
The rise of cell therapies, gene therapies, and nucleic acid-based products is creating new demand for specialized chromatographic resins tailored for complex purification challenges, expanding the market beyond traditional biologics.
Shift Toward Single-Use and Intensified Bioprocessing
Biopharmaceutical manufacturers are increasingly adopting single-use and intensified chromatography systems, which require high-performance resins optimized for rapid processing, scalability, and compatibility with disposable formats.
Rising Demand for Customized and Application-Specific Resins
As bioprocessing becomes more complex, there is growing demand for resins customized to specific molecules or applications, driving innovation and deeper collaboration between resin suppliers and end users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chromatographic Separation Resin, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chromatographic Separation Resin market projected to grow between 2024 and 2032?
What are the key factors driving the growth of the chromatographic separation resin market?
What are the main types of chromatographic separation resins available on the market?
How do manufacturers ensure the quality and performance of chromatographic separation resins?
Who are the leading companies in the Chromatographic Separation Resin market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Biopharmaceutical Companies
- 1.2.2 Clinical Research Organizations
- 1.2.3 Academic Institutes
- 1.3 By Technology
- 1.3.1 Affinity Chromatography
- 1.3.2 Anion Exchange Chromatography
- 1.3.3 Cation Exchange Chromatography
- 1.3.4 Size Exclusion Chromatography
- 1.3.5 Hydrophobic Interaction Chromatography
- 1.4 By Product Type
- 1.4.1 Natural
- 1.4.2 Synthetic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,458 million → 2032: USD 2,758.83 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chromatographic Separation Resin Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chromatographic Separation Resin Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chromatographic Separation Resin Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chromatographic Separation Resin Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chromatographic Separation Resin Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chromatographic Separation Resin Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chromatographic Separation Resin Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chromatographic Separation Resin Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,458 million → 2032: USD 2,758.83 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chromatographic Separation Resin Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Biopharmaceutical Companies
- 12.3.7.2 Clinical Research Organizations
- 12.3.7.3 Academic Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Affinity Chromatography
- 12.4.7.2 Anion Exchange Chromatography
- 12.4.7.3 Cation Exchange Chromatography
- 12.4.7.4 Size Exclusion Chromatography
- 12.4.7.5 Hydrophobic Interaction Chromatography
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Natural
- 12.5.7.2 Synthetic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chromatographic Separation Resin End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Chromatographic Separation Resin Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Chromatographic Separation Resin Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Chromatographic Separation Resin Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Merck KGaA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific Inc.
- 18.4 Tosoh Bioscience
- 18.5 Agilent Technologies
- 18.6 Bio-Rad Laboratories
- 18.7 GE Healthcare
- 18.8 Pall Corporation
- 18.9 Avantor Performance Materials Inc.
- 18.10 Mitsubishi Chemical Corporation
- 18.11 Waters Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

