
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Radiation Curable Coatings Market Size 2023 | USD 112,073.43 Million |
| Radiation Curable Coatings Market, CAGR | 6.10% |
| Radiation Curable Coatings Market Size 2032 | USD 193,860.41 Million |
Market Overview
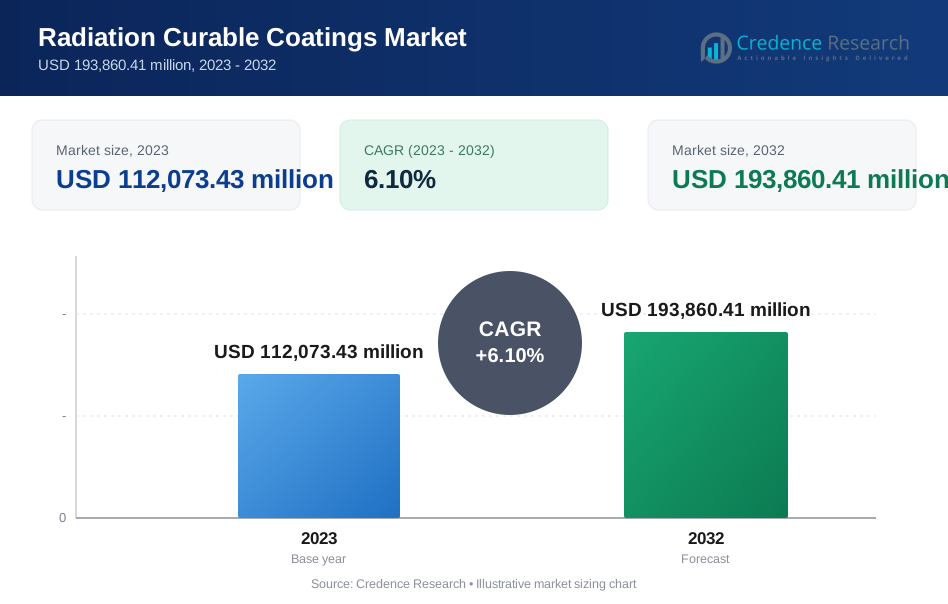
The radiation-curable coatings market is projected to grow from USD 112,073.43 million in 2023 to USD 193,860.41 million by 2032, at a compound annual growth rate (CAGR) of 6.10%.
The radiation-curable coatings market is driven by growing environmental awareness and stringent regulatory standards that favor low-VOC, energy-efficient solutions. These coatings are gaining traction due to their rapid curing times and superior finish quality, significantly enhancing productivity in automotive, industrial, and consumer goods applications. Additionally, advancements in UV and EB curing technologies are expanding the range of substrates and applications suitable for radiation-curable coatings. The trend towards sustainability and increased operational efficiency continues to push demand, positioning these coatings as an attractive option for environmentally conscious manufacturers seeking to minimize their ecological footprint.
Geographically, the radiation-curable coatings market is witnessing significant growth in the Asia-Pacific region, driven by rapid industrialization and rising environmental regulations in countries like China and India. North America and Europe also hold substantial market shares, bolstered by advanced manufacturing sectors and stringent environmental norms. Key players in the market include BASF SE, Allnex, and Covestro AG, which dominate through technological innovation and global distribution networks. These companies are expanding their presence in high-growth regions and focusing on developing eco-friendly products to meet the evolving demands of the global market and regulatory landscape.
Market Drivers
Enhanced Performance and Rapid Curing Benefits
Radiation-cured coatings offer superior performance characteristics that conventional solvent-borne or waterborne coatings often cannot match. One of their most notable features is rapid curing, as these coatings solidify almost instantly upon exposure to UV light or electron beams. In terms of application, these coatings are used on vehicle components, such as interior trims, exterior parts, and aircraft interiors, to provide aesthetic appeal and durability. They are also applied to wood surfaces for furniture, cabinets, flooring, and decorative items to provide protection against moisture, scratches, and UV radiation. Moreover, based on function, the radiation-curable coatings market is segmented as scratch-resistant, UV protection, chemical-resistant, high-gloss, matte, and satin. For instance, Scratch-Resistant held a dominant market share of around 40% in 2022 and is expected to grow at a lucrative pace through 2032.
Durability and Eco-Friendly Attributes
These coatings are known for their exceptional durability and chemical resistance. For instance, energy-cured coatings generally have enhanced impact, scratch, chemical, and abrasion resistance compared to conventionally cured coatings. They form a tough, chemically resistant layer that is ideal for use in demanding environments such as automotive parts, industrial machinery, and outdoor furniture. Additionally, unlike traditional coatings that often rely on solvents, radiation-cured coatings are formulated with minimal or no solvents, leading to significantly lower VOC emissions. For instance, the U.S. Environmental Protection Agency defines a VOC as any compound containing at least one atom of carbon. The measurement of volatile emissions from coatings is an important requirement for demonstrating compliance with air emission standards as set by the EPA. Despite the volume of resin consumed, there is no established ASTM test method for measuring these emissions from thin radiation-curable coatings.
Energy Efficiency and Regulatory Compliance
The energy efficiency of radiation-cured coatings is another critical advantage. For instance, radiation cure coatings offer a high-speed light curing process with multiple advantages, including high speed, lower energy requirements, less production space, less dirt collection, a high-quality finish, rapid processing, and instant on-off with some UV light technologies, which also expedite production and energy savings. Their ability to cure quickly translates to lower energy consumption compared to traditional drying methods used with solvent-borne coatings. This attribute aligns well with the increasing global focus on energy-efficient manufacturing processes across various industries. Moreover, the minimal use of solvents and low VOC emissions from radiation-cured coatings make them highly favored in regions with strict environmental regulations, further driving their adoption. For instance, the U.S. Environmental Protection Agency defines a VOC as any compound containing at least one atom of carbon. The measurement of volatile emissions from coatings is an important requirement for demonstrating compliance with air emission standards as set by the EPA. Despite the volume of resin consumed, there is no established ASTM test method for measuring these emissions from thin radiation-curable coatings. Radiation-cured coatings have gained importance, being favored by environmental regulations and technological developments compared with other coatings.
Versatility Across Multiple Industries
Radiation-cured coatings are versatile enough to find applications across a diverse range of industries due to their enhanced performance benefits. In the wood coatings sector, they are applied to furniture, cabinets, and flooring to provide a durable, attractive finish that resists scratches and stains. For instance, prefinished wood products, which include wood flooring and wood furniture and fixtures, each account for approximately 11% of the market for radiation-cured coatings and are growing at much healthier annual rates of 5% and 6%, respectively. In the realm of electronics, these coatings are chosen for their excellent electrical insulating properties and adaptability to complex shapes. UV curing is widely used for electronics applications such as adhesive bonding and assembly, component marking, gasketing and sealing, potting, masking, encapsulating, and conformal coating. The automotive industry also benefits from the use of radiation-cured coatings, utilizing them for various parts due to their durability, chemical resistance, and ability to meet rigorous performance standards. Within automotive applications, radiation-curable coatings play a vital role by providing fast-curing and durable finishes, contributing to enhanced efficiency and environmental sustainability in the coating process.
Market Trends
Innovations in materials and technology drive sustainability and efficiency.
The radiation curable coatings market is witnessing a significant shift towards sustainability, with an increasing number of products being developed from bio-based materials such as vegetable oils or recycled content. This move caters to a growing segment of environmentally conscious consumers and manufacturers, aiming to reduce the coatings industry’s overall environmental footprint.
Alongside this, advancements in radiation curing technology are enhancing the market’s dynamism. The emergence of new and improved curing methods, which utilize varying wavelengths of light and electron beam sources, offers better control over the curing process. These innovations not only allow for customization tailored to specific applications but also improve the energy efficiency of the curing process. This trend is driven by the need for more environmentally friendly production processes and products that do not compromise on quality or performance.
Automation and specialized coatings propel the market forward.
As the industry moves towards Industry 4.0, there is a growing trend towards automation and integration within the radiation-cured coatings sector. This includes the adoption of robotic systems for the precise application of coatings and the integration of curing processes into automated production lines, enhancing both efficiency and consistency in manufacturing.
Additionally, research and development are paving the way for radiation-cured coatings with unique functionalities, such as scratch-self-healing, anti-microbial, and temperature-sensitive properties. These specialty coatings are expected to open new avenues for innovative applications across various industries.
Concurrently, the focus on regional market variations is becoming more pronounced. While North America and Europe continue to lead with mature markets that emphasize high performance and strict environmental compliance, the Asia-Pacific region is burgeoning, driven by its expansive manufacturing sector. This region is particularly poised for rapid growth, with a strong focus on developing cost-effective solutions that meet local manufacturing demands and regulatory standards. For instance, Asia-Pacific holds the largest share of the radiation-cured coatings market at 45%, followed by North America at 25% and Europe at 22%.
Market Challenge Analysis
Cost and Compatibility Challenges in Radiation-Cured Coatings
Implementing radiation-cured coating systems often involves significant initial investments, primarily due to the need for specialized curing equipment such as UV lamps or electron beam accelerators. These upfront costs can be considerably higher than those associated with traditional coating setups, posing a financial barrier, especially for small and medium-sized enterprises (SMEs) that may find these costs prohibitive. Additionally, radiation curing technologies face challenges related to substrate compatibility. Not all materials are suitable for radiation curing; some substrates may not effectively transmit UV light or electron beams, leading to issues such as uneven curing or incomplete cure throughout the coating layer. This limitation can severely compromise the performance and quality of the coating, restricting the range of applications for radiation-cured coatings and impacting their market penetration.
Complex Formulations and Safety Considerations
The development of radiation-curable coatings often requires complex formulation strategies. Achieving specific performance characteristics necessitates a meticulous selection of ingredients and additives, which can be more intricate and demanding compared to formulating traditional solvent-borne coatings. This complexity increases the challenge for manufacturers, requiring advanced technical knowledge and capabilities. Moreover, the limitations in curing depth with UV technology present another hurdle, especially for applications that require thick coatings or a deep cure. Alternatives like electron beam curing may be necessary, further complicating the production process. Additionally, radiation curing processes expose workers to UV light or electron beams, which can pose significant health and safety risks. Ensuring worker safety demands rigorous safety protocols, proper equipment, and comprehensive training. These safety concerns add another layer of complexity to the adoption and implementation of radiation-cured coatings, necessitating careful management and adherence to strict regulatory standards to safeguard personnel and maintain a safe work environment.
Market segmentation analysis:
By Type:
In the radiation-curable coatings market, segmentation by type is primarily divided into UV-curable coatings and EB-curable coatings. UV-curable coatings dominate the sector due to their wide range of applications and the relative simplicity and cost-effectiveness of the UV-curing equipment. These coatings are particularly favored for quick-drying processes and applications requiring clear, high-quality finishes, such as in the graphic arts and automotive industries. On the other hand, electron beam (EB) curable coatings are utilized for their deeper penetration capabilities and the absence of photoinitiators, which is beneficial for food packaging and healthcare products. EB-curable coatings are preferred in applications where complete through-curing of thicker layers is necessary, offering superior physical properties without the dependency on light exposure.
By Function:
Functionally, the radiation-curable coatings market includes options such as scratch-resistant, UV protection, chemical-resistant, high-gloss, and matte and satin finishes. Scratch-resistant coatings are highly sought-after in the automotive and electronics industries to enhance product durability and longevity. UV protection coatings are crucial for outdoor applications, protecting surfaces from fading and material degradation under sun exposure. Chemical-resistant variants are essential in industrial environments where exposure to solvents and other harsh chemicals is common. High-gloss finishes are predominantly used in the consumer goods and automotive sectors to achieve an aesthetically pleasing appearance. Conversely, matte and satin finishes are increasingly popular in both residential and commercial settings for their modern look and ability to hide imperfections. This functional segmentation underlines the adaptability and versatility of radiation-curable coatings to meet specific industry requirements and consumer preferences.
Segments:
Based on Type
- UV-curable coatings
- EB Curable Coatings
Based on function
- Scratch-Resistant
- UV Protection
- Chemical-Resistant
- High-Gloss
- Matte and Satin
Based on the application
- Paper and film coatings
- Printing Inks
- Wood
- Plastics
- Electronic Products
- Others
Based on End-Use
- Wood Coatings
- Metal Coatings
- Plastic Coatings
- Printed Materials
- Electronic Components
- Optical Coatings
- Automotive Coatings
- Aerospace Coatings
- Other
Based on the geography
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific accounts for nearly 25% of the global market share, representing a rapidly growing region. The increasing industrialization, the expansion of the automotive and electronics sectors, and the growing adoption of advanced manufacturing technologies have driven the demand for radiation-curable coatings in countries like China, India, and Japan. Additionally, the region's focus on reducing environmental impact and improving energy efficiency is expected to further bolster market growth in the coming years.
Europe
Europe closely follows, holding approximately 30% of the global radiation-curable coatings market share. The region's demand is fueled by factors such as the emphasis on sustainability, the need for energy-efficient manufacturing processes, and the stringent regulations governing environmental impact. Countries like Germany, the United Kingdom, and France are key contributors to the region's market growth, with a strong focus on developing eco-friendly and high-performance coating solutions for various applications.
Key Player Analysis
- BASF SE
- DSM Coating Resins
- Allnex
- Covestro AG
- Bayer MaterialScience AG
- Royal DSM N.V.
- Eternal Materials Co., Ltd.
- Bomix Chemie GmbH
- Red Spot Paint & Varnish Co., Inc.
- Miwon Specialty Chemical Co., Ltd.
Competitive Analysis
The competitive landscape of the radiation-curable coatings market is highly dynamic, with key players such as BASF SE, DSM Coating Resins, and Covestro AG leading the charge. These companies excel through continuous innovation, extensive R&D investments, and broad product portfolios that cater to diverse industrial requirements. BASF and Covestro, for instance, leverage their global presence and cutting-edge technology to deliver high-performance coatings with enhanced properties. Allnex stands out for its specialized resins, which improve the functionality and sustainability of coatings. Similarly, Royal DSM N.V. and Bayer MaterialScience AG focus on eco-friendly solutions that meet stringent environmental standards. Companies like Eternal Materials Co., Ltd. and Miwon Specialty Chemical Co., Ltd. enhance their market positions through localized strategies and tailored solutions, particularly in Asian markets. Smaller players such as Bomix Chemie GmbH and Red Spot Paint & Varnish Co., Inc., distinguish themselves by offering niche products and specialized services, demonstrating the market's wide range of opportunities for innovation and customer engagement.
Recent Developments
In June 2023, Evonik added to its product lineup the ‘TEGO Rad 2550’ slip and defoamer additive, designed for radiation-curing inks and coatings.
Market Concentration and Characteristics
The radiation-curable coatings market features a moderate to high market concentration, dominated by a handful of global players who have established strong footholds through extensive innovation, diverse product portfolios, and strategic global networks. Key players such as BASF SE, DSM Coating Resins, and Covestro AG lead the market, bolstered by robust research and development capabilities and wide-reaching distribution channels. These companies continually adapt to evolving environmental regulations and shifting consumer preferences towards more sustainable and efficient coating solutions. Additionally, the market is characterized by a persistent drive towards technological advancements, particularly in UV and EB curing technologies, which enhance product performance and application efficiency. New entrants face significant barriers due to the technical expertise and capital investment required, yet the growing demand for eco-friendly coatings offers opportunities for innovative startups to carve out niche markets. Overall, this competitive environment fosters a continuous push for innovation and efficiency, shaping the market's dynamics and future growth trajectory.
Report Coverage
The research report offers an in-depth analysis based on type, function, application, end-use, and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Anticipate robust growth in the Asia-Pacific region, driven by expanding manufacturing sectors and environmental policies.
- Expect continued innovations in UV and EB curing technologies that enhance curing efficiency and coating performance.
- Predict an increase in demand for bio-based and sustainable materials within the coating formulations.
- We foresee a shift towards more energy-efficient production processes in response to global sustainability trends.
- The project increased the integration of automation and advanced robotics in coating applications, improving consistency and reducing labor costs.
- Anticipate new product developments focusing on advanced functionalities like self-healing, anti-microbial, and temperature-sensitive properties.
- Expect stricter environmental regulations to spur the adoption of low-VOC and non-toxic radiation-curable coatings.
- Project growth in niche markets and specialized applications is expanding the scope of radiation-curable coatings.
- Anticipate challenges in raw material supply stability and price volatility, impacting production costs.
- Foresee greater market penetration and competitive strategies by emerging companies focusing on innovative and eco-friendly solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enhanced Performance and Rapid Curing
Radiation-curable coatings offer instant curing upon exposure to UV light or electron beams, significantly reducing production times and increasing throughput in industries such as automotive, electronics, and wood finishing. Their superior finish quality and durability make them highly attractive for manufacturers seeking both efficiency and high product standards.
Stringent Environmental Regulations and Low VOC Emissions
Increasingly strict environmental standards globally are pushing manufacturers to adopt coatings with minimal volatile organic compound (VOC) emissions. Radiation-curable coatings, which use little to no solvents, align with these regulations and help companies reduce their ecological footprint.
Energy Efficiency and Cost Savings
The rapid curing process of radiation-curable coatings requires less energy compared to traditional thermal curing methods, resulting in lower operational costs and supporting the shift towards energy-efficient manufacturing practices.
Technological Advancements in UV and EB Curing
Ongoing innovations in UV and electron beam curing technologies are expanding the range of substrates and applications for radiation-curable coatings, enabling their use in more complex and demanding environments and driving broader market adoption.
Versatility Across Multiple Industries
Radiation-curable coatings are used in a wide array of applications, from automotive parts and electronics to wood products and packaging, due to their adaptability and ability to meet diverse functional requirements such as scratch resistance, chemical resistance, and UV protection.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Radiation Curable Coatings Market?
What factors are driving the growth of the radiation-curable coatings market?
What are the key segments within the Radiation Curable Coatings Market?
What are some challenges faced by the radiation-curable coatings market?
Who are the major players in the radiation-curable coatings market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 UV-curable coatings
- 1.2.2 EB Curable Coatings
- 1.3 By End-Use
- 1.3.1 Wood Coatings
- 1.3.2 Metal Coatings
- 1.3.3 Plastic Coatings
- 1.3.4 Printed Materials
- 1.3.5 Electronic Components
- 1.3.6 Optical Coatings
- 1.3.7 Automotive Coatings
- 1.3.8 Aerospace Coatings
- 1.3.9 Other
- 1.4 By Function
- 1.4.1 Scratch-Resistant
- 1.4.2 UV Protection
- 1.4.3 Chemical-Resistant
- 1.4.4 High-Gloss
- 1.4.5 Matte and Satin
- 1.5 By Application
- 1.5.1 Paper and Film Coatings
- 1.5.2 Printing Inks
- 1.5.3 Wood
- 1.5.4 Plastics
- 1.5.5 Electronic Products
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 112,073.43 million → 2032: USD 193,860.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Radiation Curable Coatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Radiation Curable Coatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Radiation Curable Coatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Radiation Curable Coatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Radiation Curable Coatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Radiation Curable Coatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Radiation Curable Coatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Radiation Curable Coatings Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 112,073.43 million → 2032: USD 193,860.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Radiation Curable Coatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 UV-curable coatings
- 12.3.7.2 EB Curable Coatings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wood Coatings
- 12.4.7.2 Metal Coatings
- 12.4.7.3 Plastic Coatings
- 12.4.7.4 Printed Materials
- 12.4.7.5 Electronic Components
- 12.4.7.6 Optical Coatings
- 12.4.7.7 Automotive Coatings
- 12.4.7.8 Aerospace Coatings
- 12.4.7.9 Other
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Function - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Scratch-Resistant
- 12.5.7.2 UV Protection
- 12.5.7.3 Chemical-Resistant
- 12.5.7.4 High-Gloss
- 12.5.7.5 Matte and Satin
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Paper and Film Coatings
- 12.6.7.2 Printing Inks
- 12.6.7.3 Wood
- 12.6.7.4 Plastics
- 12.6.7.5 Electronic Products
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Radiation Curable Coatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Radiation Curable Coatings Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Radiation Curable Coatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Radiation Curable Coatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DSM Coating Resins
- 18.4 Allnex
- 18.5 Covestro AG
- 18.6 Bayer MaterialScience AG
- 18.7 Royal DSM N.V.
- 18.8 Eternal Materials Co., Ltd.
- 18.9 Bomix Chemie GmbH
- 18.10 Red Spot Paint & Varnish Co., Inc.
- 18.11 Miwon Specialty Chemical Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

