
Combination Therapies in Aesthetics Market Overview:
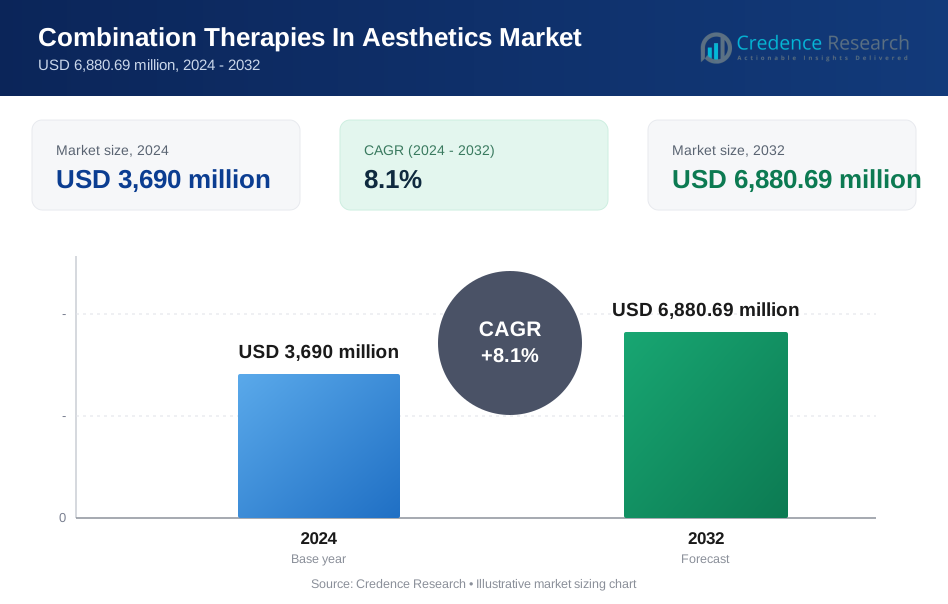
The global combination therapies in aesthetics market was valued at USD 3,690 million in 2024 and is projected to reach USD 6,880.69 million by 2032, expanding at a compound annual growth rate (CAGR) of 8.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Combination Therapies in Aesthetics Market Size 2024 | USD 3,690 million |
| Combination Therapies in Aesthetics Market , CAGR | 8.1% |
| Combination Therapies in Aesthetics Market Size 2032 | USD 6,880.69 million |
Combination Therapies in Aesthetics Market Insights
- Market growth is primarily driven by rising demand for comprehensive aesthetic outcomes, where combination protocols address wrinkles, volume loss, texture, and pigmentation in fewer sessions with longer-lasting results, improving patient satisfaction and clinic efficiency.
- Key market trends include increasing adoption of protocol-based treatments and personalized therapy planning, with BTx-A combined with dermal fillers emerging as the dominant segment, accounting for approximately 35–38% share, supported by strong clinical efficacy and repeat demand.
- Competitive dynamics are shaped by established injectable and device manufacturers offering integrated portfolios, practitioner training programs, and cross-modality treatment ecosystems to strengthen brand loyalty and procedural adoption.
- Regionally, North America leads with around 39-40% market share, followed by Europe at nearly 27% and Asia-Pacific at about 23%, while cost sensitivity and skill requirements remain key restraints in emerging regions.

Combination Therapies in Aesthetics Market Segmentation Analysis:
By Therapy Type:
By therapy type, BTx-A combined with dermal fillers represents the dominant sub-segment, accounting for an estimated around 34-38% of total market share. Its leadership is driven by the ability to simultaneously address dynamic wrinkles and volume loss, delivering comprehensive facial rejuvenation with high patient satisfaction. This combination reduces treatment sessions while improving aesthetic balance and longevity of results. BTx-A/lasers and laser/radiofrequency follow, supported by demand for texture refinement and skin tightening. Ongoing innovation in injectable formulations and energy-based devices continues to strengthen adoption across clinical settings.
- For instance, AbbVie’s Allergan Aesthetics routinely pairs onabotulinumtoxinA (Botox®, supplied in 50- and 100-unit vials) with JUVÉDERM® VYCROSS fillers, which feature a tightly cross-linked hyaluronic acid matrix engineered for controlled lift and sustained tissue integration over several months, enabling physicians to treat glabellar lines and mid-face volume deficits in one session.
By Application:
By application, skin resurfacing is the leading sub-segment, holding approximately 30-35% of the market share, driven by rising demand for treatments targeting wrinkles, pigmentation, acne scars, and overall skin quality. Combination protocols using lasers, radiofrequency, and topical agents deliver superior outcomes by addressing both superficial and deeper dermal concerns. Scar removal and tattoo removal also show strong uptake due to improved clearance rates with multi-modal approaches. Hair removal maintains steady demand, while emerging applications benefit from personalized, protocol-based aesthetic treatment strategies.
- For instance, Lumenis has advanced combination resurfacing through its UltraPulse® CO₂ laser, operating at a 10,600 nm wavelength with pulse energies exceeding 100 mJ, often paired clinically with Legend Pro™ RF, which delivers multi-depth bipolar and tri-polar radiofrequency energy to stimulate neocollagenesis while minimizing downtime.
By End User:
By end user, dermatology clinics dominate the market with nearly 45-50% share, supported by high procedure volumes, specialized expertise, and rapid adoption of advanced combination protocols. Clinics benefit from flexible treatment customization and strong patient trust in minimally invasive aesthetic procedures. Ambulatory surgical centers follow, driven by outpatient efficiency and growing cosmetic service portfolios. Hospitals account for a smaller share, mainly handling complex or adjunctive aesthetic procedures. Increasing medical spa integration and practitioner training further reinforce dermatology clinics as the primary growth driver.
Key Growth Drivers
Rising Demand for Comprehensive and Long-Lasting Aesthetic Outcomes
One of the primary growth drivers for combination therapies in aesthetics is the increasing patient preference for comprehensive treatment outcomes that address multiple concerns simultaneously. Single-modality treatments often deliver limited or short-term improvements, whereas combination approaches such as neuromodulators with fillers or lasers with radiofrequency enable synergistic effects across different skin layers. Patients increasingly seek treatments that improve wrinkles, volume loss, pigmentation, and skin texture in fewer sessions with longer-lasting results. This demand is particularly strong among aging populations and younger consumers focused on preventative aesthetics. Higher satisfaction rates, reduced retreatment frequency, and visible outcome optimization are driving practitioners to adopt multimodal protocols as standard practice.
- For instance, Solta Medical’s Thermage FLX system utilizes monopolar radiofrequency (RF) energy with a maximum average power of 400 W. For comprehensive facial rejuvenation, it commonly employs a treatment tip with a 900-pulse (REP) count to deliver precise, bulk heating. This procedure is frequently integrated with injectable neuromodulators to prolong firmness and enhance wrinkle reduction outcomes with little to no additional downtime."
Advancements in Minimally Invasive and Energy-Based Technologies
Technological innovation in injectables, laser systems, radiofrequency platforms, and topical delivery systems is significantly accelerating market growth. Modern devices offer improved precision, customizable energy settings, and enhanced safety profiles, enabling practitioners to combine therapies with minimal downtime. Advances such as fractional lasers, non-ablative RF, and next-generation dermal fillers allow clinicians to tailor treatment plans based on skin type, age, and aesthetic goals. These improvements reduce procedural risks while expanding the scope of combination treatments across facial and body applications. As technology becomes more user-friendly and predictable, adoption among dermatologists and aesthetic clinics continues to rise.
- For instance, Cynosure’s Potenza™ RF microneedling system integrates monopolar and bipolar RF delivered through needles penetrating up to 4 mm, enabling precise dermal coagulation while preserving the epidermis, and is frequently combined with injectables or topical actives to enhance overall skin quality.
Growing Awareness and Acceptance of Aesthetic Procedures
Increasing social acceptance of aesthetic treatments, driven by digital media influence and evolving beauty standards, is another major growth driver. Consumers are more informed about treatment options and outcomes, often requesting combination therapies proactively. The normalization of minimally invasive aesthetic procedures among both men and women has expanded the addressable patient pool. In parallel, growing disposable income in emerging markets and increased access to aesthetic clinics are supporting procedural growth. Practitioner-led education, before-and-after visibility, and personalized consultation models further reinforce patient confidence, accelerating demand for integrated aesthetic treatment approaches.
Key Trends & Opportunities
Personalized and Protocol-Based Treatment Planning
A major trend shaping the market is the shift toward personalized aesthetic treatment protocols. Rather than standardized procedures, practitioners increasingly design combination regimens based on individual skin biology, aging patterns, and lifestyle factors. This protocol-driven approach improves predictability and clinical outcomes while differentiating service offerings. Digital skin analysis tools and AI-assisted treatment planning further enhance customization. This trend creates opportunities for clinics to increase patient retention, premium pricing, and long-term treatment programs, strengthening revenue streams across repeat visits.
- For instance, Canfield Scientific’s VISIA® Gen 7 Skin Analysis System captures multi-spectral facial images using RBX®, UV, and cross-polarized lighting and quantifies parameters such as wrinkles, pores, texture, and UV damage through objective numerical scoring, enabling clinicians to select and sequence injectables, lasers, and energy-based devices with data-backed precision.
Expansion of Combination Therapies Beyond Facial Aesthetics
Combination therapies are increasingly applied to non-facial areas such as the neck, décolletage, hands, scalp, and body contouring. Applications including scar revision, stretch mark treatment, hair restoration, and skin tightening are gaining traction. The ability to combine energy-based devices with injectables or topical agents expands therapeutic versatility. This diversification opens new revenue opportunities for clinics while addressing unmet aesthetic needs beyond facial rejuvenation, supporting broader market penetration.
- For instance, Merz Aesthetics has expanded clinical use of Radiesse® (calcium hydroxylapatite microspheres with particle sizes in the 25-45 µm range) for hand and neck rejuvenation, frequently combined with Belotero® hyaluronic acid fillers to simultaneously improve structural support and superficial skin quality while maintaining natural mobility in thinner skin zones.
Integration of Regenerative and Skin-Quality Enhancing Treatments
The incorporation of regenerative techniques such as platelet-rich plasma, biostimulatory fillers, and advanced cosmeceuticals into combination protocols is an emerging opportunity. These treatments focus on improving skin quality, collagen stimulation, and tissue regeneration rather than volume correction alone. Their integration enhances long-term outcomes and aligns with patient demand for natural-looking results, positioning combination therapies as holistic aesthetic solutions.
Key Challenges
High Treatment Costs and Accessibility Barriers
One of the key challenges facing the market is the relatively high cost of combination aesthetic procedures. Multiple modalities increase treatment expenses, limiting accessibility for price-sensitive consumers. Advanced devices, premium injectables, and skilled practitioner involvement contribute to higher procedural pricing. This can restrict adoption in emerging markets and among younger demographics. Clinics must balance treatment efficacy with affordability to expand patient reach, which remains a significant constraint on market scalability.
Requirement for Advanced Practitioner Expertise and Training
Combination therapies require a high level of clinical expertise, anatomical knowledge, and procedural sequencing skills. Incorrect treatment order or dosage can compromise outcomes or increase complication risks. Continuous training and certification are essential, creating operational and time burdens for clinics. Variability in practitioner skill levels can also lead to inconsistent patient experiences, affecting trust and adoption. Ensuring standardized training and protocol adherence remains a critical challenge for sustained market growth.
Regional Analysis
North America:
North America leads the combination therapies in aesthetics market, accounting for approximately 38-40% of global market share. Growth is driven by high procedure volumes, early adoption of advanced combination protocols, and strong consumer spending on minimally invasive aesthetic treatments. The U.S. dominates the region due to a dense network of dermatology clinics, medical spas, and ambulatory surgical centers offering multimodal treatments such as BTx-A with fillers and lasers with radiofrequency. Strong practitioner expertise, continuous technology upgrades, and high awareness of aesthetic maintenance further reinforce North America’s leadership position.
Europe:
Europe represents the second-largest regional market, holding nearly 26-28% of total market share. Demand is supported by an aging population, strong preference for natural-looking outcomes, and widespread acceptance of combination-based rejuvenation protocols. Countries such as Germany, France, the UK, and Italy drive regional growth through advanced dermatology infrastructure and regulatory-compliant aesthetic practices. European patients increasingly opt for protocol-driven treatments combining injectables and energy-based devices to achieve subtle, long-term results. Additionally, rising medical tourism in Southern and Eastern Europe supports procedural volumes and clinic expansion.
Asia-Pacific:
Asia-Pacific accounts for around 22-24% of the global market share and represents the fastest-growing region. Growth is driven by rising disposable income, expanding middle-class populations, and strong aesthetic consciousness across countries such as South Korea, China, Japan, and India. The region shows high demand for skin resurfacing, scar reduction, and combination laser-based treatments tailored to diverse skin types. Rapid expansion of dermatology clinics, increasing practitioner training, and growing influence of social media aesthetics are accelerating adoption of combination therapy protocols across both metropolitan and tier-two cities.
Latin America:
Latin America holds approximately 6-7% of market share, supported by growing demand for aesthetic procedures in countries such as Brazil, Mexico, and Colombia. The region benefits from a strong cultural emphasis on appearance and a well-established cosmetic surgery ecosystem transitioning toward minimally invasive combination therapies. Clinics increasingly integrate injectables with energy-based devices to improve outcomes while reducing downtime. Although affordability constraints persist, expanding private clinics, improving access to advanced technologies, and rising medical tourism are contributing to steady market growth across urban centers.
Middle East & Africa:
The Middle East & Africa region accounts for nearly 4-5% of the global market share, with growth concentrated in the Gulf Cooperation Council (GCC) countries. High-income populations, luxury aesthetic clinics, and strong demand for premium combination treatments drive adoption in markets such as the UAE and Saudi Arabia. In Africa, growth remains gradual due to limited access and cost sensitivity, though private dermatology clinics are expanding. Increasing awareness, medical tourism, and investments in advanced aesthetic infrastructure are expected to support long-term regional market development.
Combination Therapies in Aesthetics Market Segmentations:
By Therapy Type:
- BTx-A / Dermal Fillers
- BTx-A / Lasers
- Laser / Topical Drugs
- Laser / Radiofrequency
- Dermal Fillers / Topical Drugs
- Others
By Application:
- Hair Removal
- Tattoo Removal
- Skin Resurfacing
- Scar Removal
- Others
By End User:
- Hospitals
- Ambulatory Surgical Centers
- Dermatology Clinics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the combination therapies in aesthetics market is characterized by the presence of established global aesthetic companies alongside specialized device and injectable manufacturers competing through innovation, portfolio breadth, and clinical integration. Leading players focus on offering complementary product ecosystems that enable practitioners to combine neuromodulators, dermal fillers, lasers, and energy-based devices within unified treatment protocols. Strategic priorities include continuous product upgrades, expansion of indication approvals, and practitioner training programs to support safe and effective multimodal use. Companies increasingly emphasize synergistic positioning of injectables with devices to strengthen brand loyalty and cross-selling opportunities. Partnerships with dermatology clinics, aesthetic chains, and training academies play a critical role in market penetration. Competitive differentiation is further supported by investments in R&D aimed at improving treatment precision, durability of results, and reduced downtime. Overall, competition remains moderately consolidated, with innovation, clinical education, and integrated solutions defining long-term success.
Key Player Analysis
- Allergan
- Galderma S.A.
- Merz Pharma GmbH & Co. KGaA
- Lumenis Ltd.
- Alma Lasers Ltd.
- Cynosure Inc.
- Cutera, Inc.
- Syneron Medical Ltd.
- Valeant Pharmaceutical International, Inc.
- Anika Therapeutics, Inc.
- Speciality European Pharma
Recent Developments
- In November 17, 2025, Galderma unveiled pivotal new data on its injectable aesthetics portfolio, highlighting results for Restylane® HA injectables, Sculptra®, and its investigational Relfydess™ (relabotulinumtoxinA) - notably reporting rapid onset effects as soon as day one on frown lines and crow’s feet from Phase III studies.
- In September 25, 2025, Allergan Aesthetics introduced the AA Signature™ multimodal treatment approach at the International Aesthetic Anti-Aging Medicine World Congress (AMWC) in Dubai. This framework integrates Allergan’s portfolio of neuromodulators, fillers, and complementary modalities to support tailored multimodal aesthetic plans across facial treatment areas, reflecting its strategic shift toward combination therapy protocols and enhanced clinical education.
Report Coverage
The research report offers an in-depth analysis based on Therapy Type, Application, End user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Combination therapies in aesthetics, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Combination therapies in aesthetics projected to grow between 2024 and 2032?
Which Combination therapies in aesthetics segment held the largest share in 2024?
What are the primary factors fueling the growth of the Combination therapies in aesthetics market?
Who are the leading companies in the Combination therapies in aesthetics market?
Which region commanded the largest share of the Combination therapies in aesthetics market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Combination Therapies In Aesthetics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Combination Therapies In Aesthetics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,690 million → 2032: USD 6,880.69 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Combination Therapies In Aesthetics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Combination Therapies In Aesthetics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Combination Therapies In Aesthetics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Combination Therapies In Aesthetics Market Drivers
- 3.3 Combination Therapies In Aesthetics Market Restraints & Challenges
- 3.4 Combination Therapies In Aesthetics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Combination Therapies In Aesthetics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Combination Therapies In Aesthetics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Combination Therapies In Aesthetics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Combination Therapies In Aesthetics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Combination Therapies In Aesthetics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Combination Therapies In Aesthetics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Combination Therapies In Aesthetics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Combination Therapies In Aesthetics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Combination Therapies In Aesthetics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Combination Therapies In Aesthetics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Combination Therapies In Aesthetics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Combination Therapies In Aesthetics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Combination Therapies In Aesthetics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Combination Therapies In Aesthetics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Combination Therapies In Aesthetics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Combination Therapies In Aesthetics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Combination Therapies In Aesthetics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Combination Therapies In Aesthetics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Combination Therapies In Aesthetics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
