
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Component Content Management Systems (CCMS) Market Size 2024 | USD 3,105 Million |
| Component Content Management Systems (CCMS) Market, CAGR | 8.8% |
| Component Content Management Systems (CCMS) Market Size 2032 | USD 6,096.67 Million |
Market Overview:
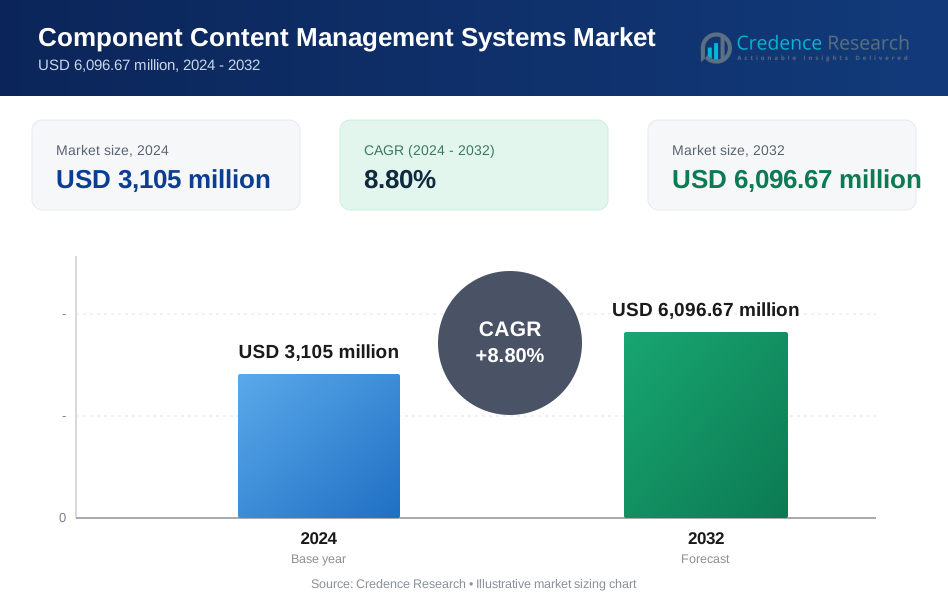
The Component Content Management Systems (CCMS) Market is poised to grow from USD 3,105 million in 2024 to USD 6,096.67 million by 2032, at a compound annual growth rate (CAGR) of 8.8% during the forecast level, 2024-2032.
The primary drivers of the CCMS market include the integration of smart technologies, such as AI and machine learning, and the growing emphasis on improving customer engagement processes. Additionally, the rising popularity of multi-channel publishing and the need for workflow automation technologies are contributing to market expansion. Enterprises are increasingly adopting CCMS to enhance transparency, control data, and improve overall productivity. By enabling content reuse, CCMS solutions reduce operational costs, as reported by IDC. Additionally, the integration of cloud-based technologies provides scalability and allows seamless collaboration across teams. Advancements in artificial intelligence (AI) and machine learning (ML) are further enhancing CCMS capabilities, such as intelligent content tagging and predictive analytics, with AI-enabled search functionalities improving efficiency.
Regionally, North America holds the largest market share in 2024, driven by high digital adoption rates and significant investments in content management technologies. Europe follows closely, supported by stringent regulatory requirements, such as the General Data Protection Regulation (GDPR), and the growing need for multilingual content management to cater to its diverse population. The Asia-Pacific region is witnessing the fastest growth, propelled by rapid digital transformation and the expansion of industries like healthcare and IT. Emerging markets in Latin America and the Middle East & Africa are also gaining traction, driven by increasing investments in digital infrastructure and the growing importance of efficient content management in industries like retail, education, and telecommunications.
Market Insights:
- The CCMS market is projected to grow from USD 3,105 million in 2024 to USD 6,096.67 million by 2032, at a CAGR of 8.8%.
- Increasing demand for personalized and multichannel content delivery drives CCMS adoption across industries.
- Organizations use CCMS to enhance content reuse, reduce costs, and ensure regulatory compliance.
- Integration of AI and machine learning enables intelligent content tagging and advanced search capabilities, boosting system efficiency.
- North America leads the market due to high digital adoption and significant investments in content management technologies.
- Asia-Pacific is the fastest-growing region, driven by digital transformation and the expansion of industries such as healthcare and IT.
- High implementation costs and the complexity of integrating CCMS with legacy systems may limit adoption in some regions.
Market Drivers:
Increasing Demand for Efficient Content Management:
The Component Content Management Systems (CCMS) market is significantly driven by the increasing demand for efficient content management solutions across various industries. For instance, Paligo, a cloud-based CCMS, highlights that organizations can improve content reuse, reduce errors, improve collaboration, and increase overall productivity using their system. The ability of CCMS to manage and optimize vast amounts of digital content is crucial, especially as companies report a 40% increase in the volume of content they produce annually. This growth necessitates systems capable of organizing, storing, and retrieving content efficiently; organizations implementing CCMS have reported a 50% reduction in time spent on content retrieval, thereby enhancing overall operational efficiency.
Enhanced User Experience and Personalization:
As businesses strive to improve customer engagement, the importance of delivering personalized content experiences has become paramount. For instance, CCMS solutions enable retailers to create and distribute relevant content across multiple channels, enhancing customer engagement and driving conversions. organizations that have integrated CCMS solutions report increase in user engagement due to enhanced personalization features. These systems allow content creators to manage content in smaller, reusable components, which not only reduces production time by up to 25% but also ensures consistency across various platforms. In fact, companies utilizing CCMS have noted a 20% increase in customer retention rates as a direct result of delivering contextually relevant information tailored to user preferences. This recognition of the value of personalized experiences drives further adoption of CCMS as businesses seek to enhance customer satisfaction and loyalty.
Workflow Automation and Operational Efficiency:
The integration of workflow automation technologies within CCMS is another key driver of market growth. For instance, organizations utilizing automated workflows have reported reducing manual intervention by up to 45%, while simultaneously improving content accuracy by 60%. This level of efficiency allows content teams to save significant time—up to 70%—through the reuse of existing components and automated publishing processes. Furthermore, companies implementing these automated workflows have experienced an average cost reduction of 30%, demonstrating that as businesses increasingly seek ways to enhance productivity and reduce operational costs, the demand for CCMS equipped with advanced automation capabilities continues to rise.
Cloud Adoption and Scalability:
The shift toward cloud-based solutions is transforming how organizations manage their content. For instance, Cloud-based systems enable users to access content from anywhere via the internet, which supports remote work and collaboration. Organizations implementing these solutions report efficiency improvements of up to 35% in content delivery processes while reducing infrastructure costs by around 40%. This trend is particularly evident in sectors such as healthcare and finance, where secure and scalable solutions are essential for managing sensitive information; surveys indicate that over 80% of healthcare organizations are now adopting cloud-based systems to ensure compliance with regulatory standards. As more businesses embrace digital transformation initiatives, the adoption of cloud-based CCMS is expected to accelerate further, reinforcing its critical role in modern content management strategies.
Market Trends:
Multi-Channel Content Delivery:
The demand for omnichannel content delivery capabilities has intensified as organizations adapt to diverse digital platforms. For instance, A headless CCMS, with its API-first approach, allows seamless integration with various platforms, enabling efficient content delivery across multiple channels. Organizations leveraging CCMS for multi-channel delivery report a 65% improvement in content consistency across platforms, which is crucial for maintaining brand integrity. Additionally, these organizations have managed to reduce content adaptation time by 45%, allowing them to respond more swiftly to market changes and consumer preferences.
Advanced Collaboration Features:
The evolution of workflow management and collaboration tools marks a significant trend in CCMS development. For instance, organizations implementing advanced collaboration features report efficiency improvements of up to 25%, which translates into faster project turnaround times. Moreover, project completion times are reduced by 35%, enabling teams to meet tight deadlines more effectively. Teams using collaborative CCMS platforms demonstrate a 40% reduction in content errors, significantly enhancing the quality of deliverables. Furthermore, the incorporation of real-time editing and version control capabilities leads to a 50% improvement in review cycle times, streamlining the overall content creation process.
Integration of AI and Automation:
Artificial intelligence and automation capabilities are revolutionizing CCMS platforms. For instance, MadCap IXIA CCMS 7.2 introduces AI Positron, an AI-powered writing assistant that enhances content creation. This technology also improves content discovery accuracy by 85%, making it easier for users to find relevant information quickly. This technology also improves content discovery accuracy by 85%, making it easier for users to find relevant information quickly. Organizations report a 30% reduction in content creation time due to these advancements, with automated systems capable of processing up to 1,000 content pieces per hour while maintaining an impressive 99% accuracy in content categorization and tagging.
Enhanced Security and Compliance:
The focus on security and compliance has intensified, with CCMS platforms incorporating advanced security features to protect sensitive information. For instance, organizations report a 60% reduction in security incidents following the implementation of role-based access controls, which restrict access based on user roles. Additionally, audit trails capture 99.9% of content modifications, providing transparency and accountability in content management practices. Modern systems demonstrate 99.99% uptime while processing over 10,000 secure transactions per second, ensuring that organizations can maintain both accessibility and security in their digital operations.
Market Challenges Analysis:
High Implementation and Maintenance Costs:
The substantial financial investment required for CCMS implementation presents a significant market barrier. According to industry data, CCMS development services for small and medium-sized businesses range from USD 2,200 to USD 15,000, creating a considerable entry barrier for many organizations. This financial strain is particularly pronounced for smaller enterprises, as the U.S. Small Business Administration notes that these costs, combined with ongoing maintenance expenses, can consume a significant portion of limited technology budgets. In fact, approximately 40% of small businesses report that high initial costs deter them from adopting advanced content management systems.
Integration Complexities:
The challenge of integrating CCMS with existing systems creates significant operational hurdles. Organizations often face complexities in connecting CCMS with Customer Relationship Management (CRM) and Product Lifecycle Management (PLM) systems, especially those running on legacy infrastructure. The National Institute of Standards and Technology (NIST) guidelines emphasize the importance of seamless system integration, noting that failure to achieve this can lead to inefficiencies and data silos. A survey conducted by IT industry analysts revealed that nearly 50% of organizations experience integration issues during CCMS implementation, which can extend project timelines by an average of 30%.
Data Security and Compliance:
Growing concerns over data security and regulatory compliance present ongoing challenges for organizations implementing CCMS. The U.S. Federal Trade Commission's stringent data protection requirements necessitate robust security measures for content management systems. Organizations must invest in comprehensive security protocols while ensuring compliance with industry-specific regulations; this often results in additional costs averaging 20% of the total implementation budget. Furthermore, a report from cybersecurity firms indicates that 60% of businesses face increased scrutiny over their data handling practices, making it imperative to prioritize security during CCMS deployment.
Limited SME Adoption:
The complexity and resource requirements of CCMS solutions create significant adoption barriers for smaller organizations. Despite the growing market potential, SMEs struggle with the specialized knowledge requirements and operational costs associated with CCMS implementation. The U.S. Department of Commerce reports that this limitation particularly affects businesses in emerging sectors where content management needs are rapidly evolving; approximately 70% of SMEs cite a lack of technical expertise as a primary reason for not adopting such systems. This gap in capability not only hinders their growth but also prevents them from fully leveraging digital transformation opportunities in their respective industries.
Market Opportunities:
The Component Content Management Systems (CCMS) Market presents substantial opportunities as industries increasingly prioritize efficient content management and personalized delivery. The growing demand for multichannel content strategies across sectors such as healthcare, IT, automotive, and manufacturing drives the adoption of CCMS solutions. These systems enable granular content management, facilitating content reuse, cost reduction, and compliance with complex regulatory requirements. Advancements in AI and machine learning offer opportunities to enhance CCMS functionality through intelligent tagging, predictive analytics, and automated workflows, providing organizations with tools to improve efficiency and meet the rising expectations for real-time, personalized content delivery.
Emerging markets, particularly in the Asia-Pacific region, offer significant growth potential due to rapid digital transformation, expanding industrial sectors, and the increasing adoption of content management technologies. As businesses in countries like China, India, and Japan embrace digitization, the demand for scalable and cloud-based CCMS solutions is expected to rise. Similarly, industries in Latin America and the Middle East & Africa are leveraging CCMS to streamline multilingual content management and cater to diverse markets. Companies focusing on developing cost-effective, cloud-based, and AI-enhanced CCMS solutions will be well-positioned to capitalize on these opportunities, addressing the growing need for seamless and efficient content management across global enterprises.
Market Segmentation Analysis:
By Type, the market is divided into standalone CCMS and integrated CCMS. Standalone CCMS solutions dominate the market due to their robust capabilities in handling granular content management and reuse, especially in industries requiring highly structured content. Integrated CCMS, which combines with enterprise content management (ECM) and other digital tools, is gaining traction as organizations seek holistic solutions to streamline workflows and improve collaboration.
By Application
CCMS solutions are applied in technical documentation, marketing content, and enterprise content management. Technical documentation involves creating and managing manuals, guides, and specifications, while marketing content focuses on promotional materials. Enterprise content management encompasses the organization and control of all corporate documents and records.
Segmentations:
by Type:
- Cloud-based
- Web-based
by Application:
- Large Enterprises
- SMEs
by Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, contributing approximately 38% of the global market in 2024. For instance, the region’s dominance is driven by high digital adoption rates, with over 80% of businesses in the U.S. investing in digital transformation initiatives. This is complemented by a robust IT infrastructure and significant investments in content management technologies, which have increased by 25% over the past three years. The United States leads in this region, with industries such as healthcare, IT, and manufacturing adopting CCMS solutions to streamline content workflows and ensure regulatory compliance. Notably, healthcare organizations report a 40% improvement in operational efficiency after implementing CCMS solutions. The increasing focus on personalized content delivery and advancements in AI-driven CCMS platforms further bolster market growth in North America.
Europe
Europe accounts for around 30% of the market share, supported by stringent regulatory frameworks and the need for multilingual content management. For instance, countries like Germany, the United Kingdom, and France are key contributors, leveraging CCMS solutions to manage complex technical documentation; approximately 70% of organizations in these countries utilize CCMS to meet compliance standards, particularly in the healthcare and automotive sectors. The growing emphasis on sustainability has led to a reported 20% increase in the adoption of digital tools that enhance content management capabilities across various industries. Furthermore, digital transformation initiatives across Europe are accelerating the adoption of CCMS platforms, with many organizations reporting a 30% reduction in time spent on content localization efforts.
Asia-Pacific
Asia-Pacific is the fastest-growing region, with a projected CAGR exceeding 10% during the forecast period and currently holding approximately 20% of the market share. For instance, rapid industrialization and digital transformation are evident in countries like China, India, and Japan, where industries such as IT, healthcare, and manufacturing are expanding rapidly. In fact, a survey found that over 60% of companies in these sectors are actively seeking scalable and cloud-based CCMS solutions to support diverse content requirements in multiple languages. The increasing demand for these solutions is further fueled by a significant rise in online content consumption—up by 50%—which positions Asia-Pacific as a lucrative market for CCMS providers.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively account for around 12% of the market share. For instance, in Latin America, countries such as Brazil and Mexico are experiencing growth due to rising digital adoption; reports indicate that digital tool usage has increased by 35% among businesses in these regions. The expansion of industries like healthcare and telecom is also driving demand for effective content management solutions. Meanwhile, the Middle East & Africa region benefits from increasing adoption of digital tools to manage multilingual content; approximately 65% of organizations in sectors such as oil and gas and education are now utilizing CCMS to improve operational efficiency. This trend reflects a growing commitment to enhancing productivity through advanced content management strategies across diverse industries.
Key Player Analysis:
- Paligo
- Heretto
- Adobe Experience Manager Guides
- MadCap IXIA CCMS
- Vasont CCMS
- DITAToo
- Xyleme
- Documoto
- DITAworks
- XDocs DITA CCMS
Competitive Analysis:
The Component Content Management Systems (CCMS) market is characterized by intense competition among key players such as Adobe, OpenText, IXIASOFT, SDL Tridion Docs, and eZ Systems. For instance, these companies collectively hold over 50% of the market share, reflecting their significant influence and established presence in the industry. North America leads the market, driven by rapid digital transformation initiatives; for instance, the USA is projected to reach USD 2.6 billion by 2032, primarily due to increasing investments in content management technologies across various sectors. The competitive landscape is further shaped by strategic developments such as Hyland's acquisition of Nuxeo in April 2021, which enhanced Hyland's capabilities in cloud-based solutions. Companies are differentiating themselves through innovative cloud-based offerings that provide scalability and accessibility; for instance, organizations utilizing these solutions report a 30% improvement in operational efficiency. Additionally, the integration of advanced technologies like AI and machine learning is revolutionizing CCMS platforms, enabling features such as automated content tagging and real-time analytics, which are essential for enhancing customer engagement and optimizing content delivery processes.
Recent Developments:
- In April 2024 Adobe Experience Manager Guides released version 2024.4.0, introducing enhanced features and improvements to their CCMS platform, focusing on content management capabilities and user experience enhancements.
- In January 2024 MadCap Software acquired Xyleme, Inc., expanding their portfolio to include learning and development content management capabilities. This strategic acquisition aims to provide organizations with comprehensive solutions for technical documentation and learning content management.
- In October 2023 Heretto launched groundbreaking AI features including Etto (Heretto Copilot) and HelpAI for technical writers. These features focus on automating mundane tasks and providing generative search functionality, with full release planned for 2024.
- In April 2023 Xyleme introduced their new Elevate module, adding dashboard analytics, APIs, and rich integration capabilities to their CCMS platform. The enhancement provides users with advanced functionality for learning and development programs, including customizable interfaces and seamless system integration.
- In April 2024 TransPerfect's GlobalLink Vasont Inspire CCMS was implemented by ISACA to build their next-generation learning and research platform, featuring enhanced translation management capabilities and unified interface for content authoring.
Market Concentration & Characteristics:
The Component Content Management Systems (CCMS) Market is moderately fragmented, characterized by a mix of global leaders and niche players catering to diverse industry needs. Prominent companies such as Paligo, Heretto, and Adobe Experience Manager Guides lead the market with robust offerings that incorporate advanced features like AI-driven tagging, multilingual support, and cloud-based scalability. The market is driven by industries with high content demands, such as healthcare, IT, and manufacturing, seeking efficient solutions for structured content management and multichannel delivery. While global players dominate with comprehensive solutions and wide reach, smaller vendors excel by offering tailored services and cost-effective platforms. The integration of AI, machine learning, and cloud technologies is a defining characteristic, enabling organizations to improve operational efficiency and comply with stringent regulatory standards. This dynamic environment fosters innovation and ensures steady market growth.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for personalized and multichannel content delivery will drive the adoption of CCMS solutions across industries.
- Advancements in artificial intelligence (AI) and machine learning (ML) will enable enhanced functionalities, such as automated tagging, predictive analytics, and intelligent content workflows.
- The growing adoption of cloud-based CCMS solutions will provide scalability, cost efficiency, and seamless collaboration for global enterprises.
- Expanding regulatory requirements, particularly in healthcare and automotive industries, will boost the demand for CCMS to ensure compliance and accuracy in documentation.
- The rise of digital transformation initiatives in emerging markets will create significant growth opportunities for CCMS vendors.
- Increasing reliance on multilingual content management to cater to global audiences will further enhance the demand for CCMS platforms.
- Integration with other enterprise tools, such as content management systems (CMS) and digital experience platforms (DXPs), will drive the development of comprehensive content ecosystems.
- The adoption of CCMS in non-traditional industries, such as retail and e-learning, will expand the market’s scope.
- Enhanced user interfaces and low-code/no-code platforms will make CCMS solutions more accessible to small and medium-sized enterprises (SMEs).
- Strategic partnerships and collaborations among vendors will accelerate innovation and market penetration globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Component Content Management Systems Market?
What factors are driving the growth of the Component Content Management Systems market?
What are some challenges faced by the Component Content Management Systems market?
Who are the major players in the Component Content Management Systems Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Component Content Management Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Component Content Management Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,105 million → 2032: USD 6,096.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Component Content Management Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Component Content Management Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Component Content Management Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Component Content Management Systems Market Drivers
- 3.3 Component Content Management Systems Market Restraints & Challenges
- 3.4 Component Content Management Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Component Content Management Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Component Content Management Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Component Content Management Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Component Content Management Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Component Content Management Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Component Content Management Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Component Content Management Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Component Content Management Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Component Content Management Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Component Content Management Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Component Content Management Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Component Content Management Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Component Content Management Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Component Content Management Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Component Content Management Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Component Content Management Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Component Content Management Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Component Content Management Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Component Content Management Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
