
Market Overview:
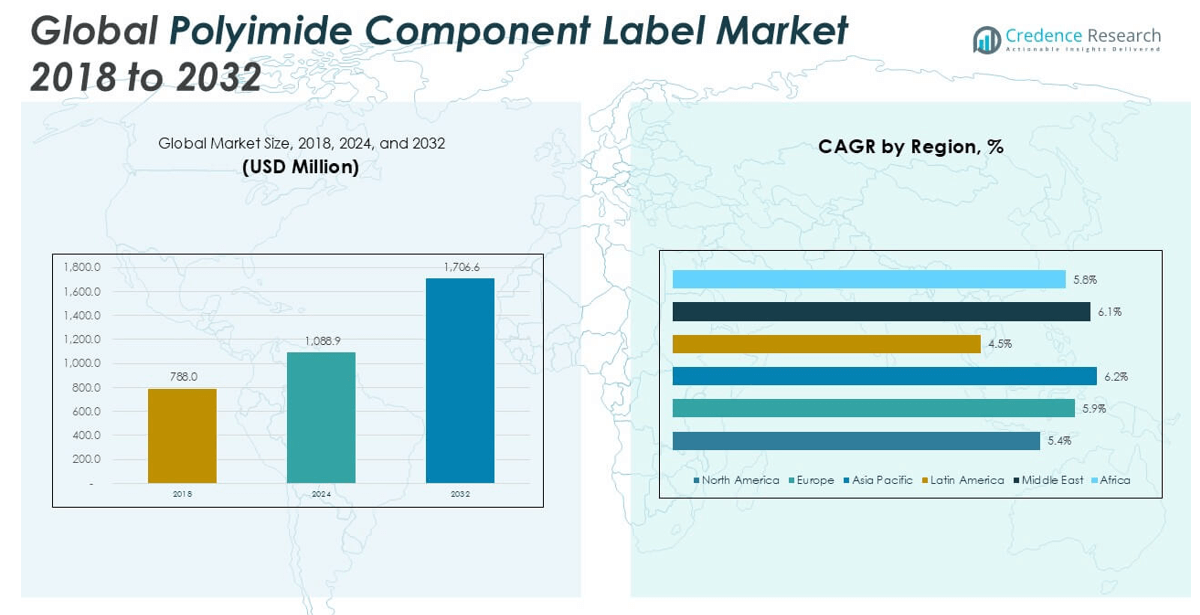
The Polyimide Component Label market size was valued at USD 788.0 million in 2018, grew to USD 1,088.9 million in 2024, and is anticipated to reach USD 1,706.6 million by 2032, at a CAGR of 5.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polyimide Component Label Market Size 2024 | USD 1,088.9 million |
| Polyimide Component Label Market, CAGR | 5.81% |
| Polyimide Component Label Market Size 2032 | USD 1,706.6 million |
The Polyimide Component Label market is led by major players such as 3M, DuPont de Nemours, Inc., Honeywell International Inc., Brady Corporation, and Avery Dennison Corporation. These companies dominate through advanced manufacturing capabilities, broad product portfolios, and strong distribution networks across key industries like electronics, automotive, and aerospace. Strategic investments in high-temperature and durable labeling technologies have reinforced their competitive positions. Asia Pacific emerges as the leading region, accounting for approximately 36.7% of the global market share in 2024, driven by rapid industrialization, robust electronics manufacturing, and expanding automotive sectors in China, Japan, South Korea, and India.
Market Insights
- The Polyimide Component Label market was valued at USD 1,088.9 million in 2024 and is projected to reach USD 1,706.6 million by 2032, growing at a CAGR of 5.81% during the forecast period.
- Market growth is primarily driven by rising demand in electronics and semiconductor industries, where high thermal stability and chemical resistance are essential for labeling sensitive components.
- A notable trend is the increasing adoption of digital printing technology, which leads the printing technology segment due to its efficiency and precision in high-performance applications.
- The market is moderately consolidated, with key players like 3M, DuPont, and Brady Corporation maintaining dominance through innovation and strategic expansion, while competition grows from regional and specialty label providers.
- Asia Pacific held the largest regional share at 36.7% in 2024, followed by Europe at 23.8%; the flexible labels segment leads by type due to its adaptability across varied industrial surfaces and harsh environments.
Market Segmentation Analysis:
By Type
In the Polyimide Component Label market, the Flexible Labels segment holds the dominant position, accounting for the largest market share in 2024. This dominance is driven by their superior adaptability to complex surfaces, lightweight structure, and high durability in harsh environments. Flexible labels are widely preferred in electronic components and circuits due to their resistance to heat, chemicals, and moisture. The increasing demand for miniaturized and flexible electronic devices in consumer electronics and medical sectors further propels the adoption of flexible polyimide labels, making this segment the most commercially viable.
- For instance, TE Connectivity’s T2K polyimide labels are manufactured with a thickness of 118 microns and can withstand 300 °C for 90 seconds without degradation.
By Printing Technology:
Among printing technologies, Digital Printing leads the market, capturing the largest share in 2024. This segment's growth is primarily attributed to its ability to deliver high-resolution, customizable, and cost-effective labeling solutions with minimal setup time. The demand for short production runs and rapid turnaround in electronics and automotive applications supports the rise of digital printing. Moreover, digital printing's compatibility with high-performance polyimide films and its precision in producing legible barcodes and identification codes enhance its relevance in critical labeling applications.
- For instance, DuPont’s Kapton® 50HN film, used in digitally printed labels, has a tensile strength at break of 172 MPa and maintains performance at 400 °C maximum service temperature.
By Application:
The Electronics segment dominates the market by application, holding the highest share in 2024. Polyimide component labels are extensively used in printed circuit boards, semiconductors, and electronic assemblies due to their high thermal stability, electrical insulation, and resistance to solvents. The growing production of consumer electronics, especially in Asia-Pacific, and the shift toward compact and high-density electronic designs have increased the need for reliable labeling solutions. As traceability, compliance, and component identification remain vital in electronics manufacturing, the demand for durable and high-performance polyimide labels continues to rise.
Market Overview
Rising Demand from Electronics and Semiconductor Industry
The increasing demand for polyimide component labels is primarily driven by their essential role in electronics and semiconductors, where labeling must withstand extreme temperatures and harsh chemicals. As the production of printed circuit boards (PCBs), semiconductors, and mobile devices grows, especially in Asia-Pacific, the need for heat-resistant and durable labeling solutions has intensified. These labels ensure traceability, identification, and compliance with global safety standards, making them indispensable in the manufacturing and testing phases of electronic components.
- For instance, DuPont’s Kapton® 200HN film demonstrates a dielectric strength of 217 kV/mm, oxygen transmission of 9.90 cc‑mm/m²‑24 hr‑atm, and moisture absorption limited to 1.8 %.
Expansion of Automotive and Aerospace Sectors
Growth in the automotive and aerospace industries is accelerating the adoption of polyimide component labels. These sectors demand high-performance materials capable of surviving vibration, high temperatures, and chemical exposure. Labels used in wiring harnesses, engine components, and control systems must retain legibility and adhesion under extreme conditions. As electric vehicles and next-generation aircraft require more sophisticated electronics, the need for robust identification systems, including polyimide labels, is expected to expand significantly, further supporting market growth.
- For instance, DuPont’s Kapton® 200KN film (50 µm thick) has a coefficient of thermal expansion closely matched to copper and secant modulus around 3.7 GPa.
Stringent Regulatory Compliance and Traceability Requirements
Tightening regulations around product traceability, safety, and quality control are pushing manufacturers to adopt high-performance labeling solutions. Polyimide labels meet stringent industrial and environmental standards, such as UL, RoHS, and REACH, and play a critical role in tracking components across the supply chain. In sectors like healthcare, defense, and electronics, accurate labeling is not only mandatory but crucial for recalls, maintenance, and auditing processes. This regulatory pressure continues to drive the demand for advanced label materials such as polyimide.
Key Trends & Opportunities
Integration of Smart Labeling Technologies
The adoption of smart labels, including RFID-enabled polyimide labels, is emerging as a significant trend. These smart labels offer enhanced traceability, real-time monitoring, and inventory management, especially in logistics-heavy sectors like aerospace and electronics. The ability to store and transmit data electronically through durable polyimide substrates opens new avenues for digital tracking and automation. As industries shift toward Industry 4.0 and smart manufacturing, this integration offers considerable opportunity for innovation and value-added services in the labeling ecosystem.
- For instance, Zebra 9600‑series RFID scanners used in industrial lines can detect transponder labels at 902‑928 MHz, process a 24‑digit EPC code within 250 ms, and reliably trigger PLC logic in under 300 ms.
Sustainability and Eco-friendly Manufacturing
There is growing emphasis on sustainable and environmentally responsible production in the labeling industry. Manufacturers are increasingly exploring recyclable and low-emission polyimide label alternatives. This trend is gaining traction among end-users looking to reduce their carbon footprint while maintaining product durability and compliance. The development of solvent-free adhesives, bio-based polymers, and cleanroom-compatible labeling processes provides new opportunities for green innovation. Companies investing in sustainable labeling solutions are likely to gain a competitive advantage in future regulatory environments.
- For instance, Caplinq’s PIT0.5S‑UT tape uses a 13 µm polyimide film laminated with 13 µm silicone adhesive (total 25 µm) and remains stable from –269 °C to 400 °C, while offering ultra-thin, solvent‑free construction.
Key Challenges
High Production and Material Costs
One of the primary challenges in the polyimide component label market is the high cost of raw materials and manufacturing processes. Polyimide films and heat-resistant adhesives require complex formulations and advanced technologies, driving up production costs. These higher costs often translate into premium-priced labels, which can limit adoption, especially among small and medium-sized enterprises. Additionally, cost-sensitive industries may opt for alternative labeling materials that offer acceptable, though lower, performance at a reduced price point.
Limited Compatibility with Certain Printing Technologies
While polyimide labels support several advanced printing techniques, they are not universally compatible with all printing technologies and inks. Some traditional or low-cost printing methods may fail to achieve adequate adhesion or resolution on polyimide surfaces. This limitation can hinder scalability and integration into existing labeling workflows, particularly in smaller production environments. As end-users seek flexible and seamless operations, the need for improved print adaptability and cross-technology compatibility remains a challenge for manufacturers.
Environmental and Disposal Concerns
Despite their durability and industrial performance, polyimide labels pose environmental concerns due to limited biodegradability and challenges in disposal or recycling. As sustainability becomes a central issue in packaging and labeling, end-users and regulators are scrutinizing the environmental impact of high-performance synthetic materials. The lack of efficient recycling processes for polyimide-based products creates long-term waste management issues. Addressing these concerns will require investment in alternative formulations and circular economy initiatives within the labeling industry.
Regional Analysis
North America:
In 2024, the North America polyimide component label market was valued at USD 230.78 million, up from USD 170.75 million in 2018, and is projected to reach USD 350.87 million by 2032, growing at a CAGR of 5.4% during the forecast period. North America accounted for approximately 21.2% of the global market share in 2024. This growth is driven by advanced electronics manufacturing, stringent labeling regulations, and increasing demand from the aerospace and automotive sectors. The U.S. leads the regional market, supported by innovation in thermal management and traceability solutions across high-reliability industrial applications.
Europe:
Europe’s polyimide component label market reached USD 259.27 million in 2024 from USD 186.51 million in 2018 and is expected to grow to USD 409.58 million by 2032, at a CAGR of 5.9%. The region held a 23.8% market share in 2024. Growth in this region is primarily supported by expanding automotive and electronics industries in Germany, France, and the UK. Additionally, the implementation of strict product identification and traceability regulations in the EU enhances label usage across manufacturing sectors. Investments in sustainable labeling materials and technologies also contribute to the region’s steady growth trajectory.
Asia Pacific:
Asia Pacific dominates the global polyimide component label market, holding the largest share of approximately 36.7% in 2024. The market grew from USD 281.93 million in 2018 to USD 399.44 million in 2024 and is forecast to reach USD 646.62 million by 2032, expanding at a CAGR of 6.2%. This robust growth is fueled by high-volume electronics production in China, South Korea, and Japan, along with rapid industrialization in India and Southeast Asia. The region’s growing automotive and semiconductor sectors, combined with favorable government initiatives and increasing export demand, continue to drive regional market expansion.
Latin America:
The Latin America market for polyimide component labels reached USD 103.99 million in 2024, increasing from USD 80.45 million in 2018 and is projected to grow to USD 147.96 million by 2032, registering a CAGR of 4.5%. The region accounted for approximately 9.6% of the global market share in 2024. Brazil and Mexico lead regional demand, driven by growth in electronics assembly and automotive components manufacturing. However, limited technological adoption and high import dependence for raw materials may temper growth. Nonetheless, increasing foreign investment and infrastructure development are gradually supporting the market’s expansion.
Middle East:
In 2024, the Middle East polyimide component label market was valued at USD 53.07 million, up from USD 37.66 million in 2018, and is expected to reach USD 85.33 million by 2032, growing at a CAGR of 6.1%. The region held a 4.9% market share globally in 2024. Market growth is supported by expanding aerospace and industrial electronics sectors in the UAE, Saudi Arabia, and Israel. Additionally, rising demand for high-temperature labeling in oil and gas infrastructure further supports adoption. Government initiatives aimed at industrial diversification are also expected to enhance long-term demand for advanced labeling solutions.
Africa:
Africa’s polyimide component label market grew from USD 30.65 million in 2018 to USD 42.31 million in 2024 and is projected to reach USD 66.21 million by 2032, at a CAGR of 5.8%. The region accounted for approximately 3.9% of the global market share in 2024. While still emerging, Africa’s electronics manufacturing and automotive sectors are gradually expanding, particularly in South Africa, Nigeria, and Egypt. Increasing urbanization and infrastructural investments are fostering industrial growth, creating new opportunities for label applications. However, limited access to high-end manufacturing technologies may continue to constrain full market potential in the near term.
Market Segmentations:
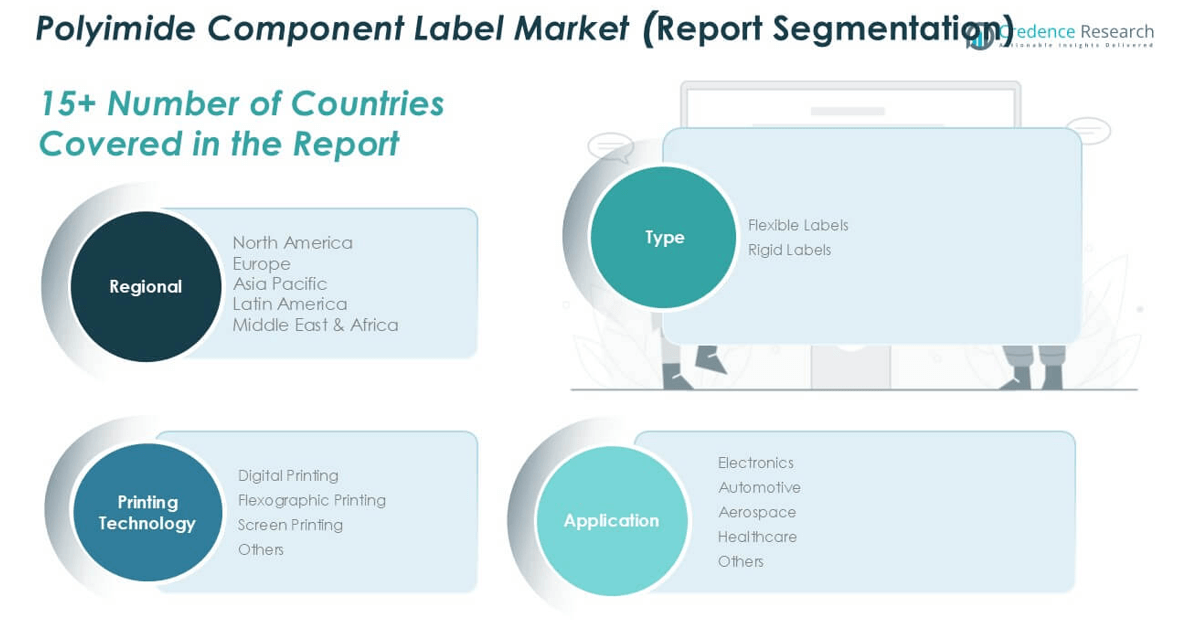
By Type:
- Flexible Labels
- Rigid Labels
By Printing Technology:
- Digital Printing
- Flexographic Printing
- Screen Printing
- Others
By Application:
- Electronics
- Automotive
- Aerospace
- Healthcare
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the polyimide component label market is characterized by the presence of several global and regional players striving to enhance their market share through innovation, strategic partnerships, and capacity expansion. Leading companies such as 3M, DuPont, Honeywell International, and Brady Corporation dominate the market with robust product portfolios, strong distribution networks, and advanced R&D capabilities. These players focus on developing high-performance, thermally stable labels tailored for critical applications in electronics, aerospace, and automotive industries. Mergers, acquisitions, and collaborations are common strategies aimed at expanding geographic reach and technological capabilities. Additionally, companies like Avery Dennison, FLEXcon, and Polyonics are investing in sustainable and smart labeling solutions to meet evolving industry requirements and environmental standards. The market also sees growing participation from niche players specializing in customized labeling, contributing to increased competition and innovation. Overall, the market is moderately consolidated, with innovation, material performance, and regulatory compliance serving as key competitive differentiators.
Key Player Analysis
- 3M
- DuPont de Nemours, Inc.
- Honeywell International Inc.
- Brady Corporation
- Henkel AG & Co. KGaA
- Avery Dennison Corporation
- CCL Industries Inc
- FLEXcon Company, Inc.
- Polyonics, Inc.
- UPM Raflatac
- LINTEC Corporation
- TE Connectivity Ltd.
- Electro Tape Specialties, Inc.
- Label-Aid Systems, Inc.
Recent Developments
- In June 2025, DuPont announced advanced interconnect innovations intended for AI and next-generation electronics, further demonstrating its leadership in the polyimide materials space for critical electronic components.
- In January 2025, DuPont highlighted advanced polyimide films, including Kapton® and Pyralux®, at DesignCon 2025. These materials, known for their thermal performance, electrical insulation, and dimensional stability, are targeted at applications in AI data centers, 5G networks, electric vehicles, and other cutting-edge electronics. The focus is on enhancing performance in demanding environments.
- In May 2024, Lintec announced a new round of R&D investment focused on developing sustainable labeling technologies, including the continued development of their polyimide label technology introduced in 2022, which offers enhanced chemical resistance. This investment aligns with Lintec's broader sustainability goals and their "LINTEC SUSTAINABILITY VISION 2030 (LSV 2030)" plan, which aims to achieve significant reductions in CO2 emissions and promote environmentally friendly products.
Market Concentration & Characteristics
The Polyimide Component Label Market exhibits moderate to high market concentration, with a few established players such as 3M, DuPont, and Brady Corporation holding significant shares due to their strong technological capabilities and global distribution networks. It features a product landscape defined by high-performance materials engineered for extreme conditions, primarily serving electronics, automotive, aerospace, and healthcare sectors. The market is characterized by stringent performance requirements, including thermal resistance, chemical stability, and compliance with industry standards. It relies heavily on innovation in materials science and printing technologies to meet evolving application demands. Entry barriers remain high due to specialized manufacturing processes and certification requirements. Demand is driven by industrial growth and the need for durable, traceable labeling solutions. It sees consistent adoption in regions with strong manufacturing bases, especially Asia Pacific and Europe
Report Coverage
The research report offers an in-depth analysis based on Type, Printing Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth due to rising demand in high-temperature applications across electronics and automotive sectors.
- Increasing adoption of electric vehicles will drive the need for durable labeling solutions with thermal and chemical resistance.
- Miniaturization of electronic devices will continue to create demand for compact, high-performance labeling materials.
- Advancements in digital and smart printing technologies will enhance customization and data tracking capabilities.
- Regulatory emphasis on product traceability and safety compliance will boost market adoption across industries.
- Growth in aerospace and defense sectors will further strengthen demand for polyimide labels in mission-critical applications.
- The Asia Pacific region will maintain its lead due to expanding electronics manufacturing and supportive government policies.
- Sustainable and recyclable labeling solutions will emerge as a key area of innovation and differentiation.
- Strategic partnerships and acquisitions will shape the competitive landscape and enable global expansion.
- Continued R&D investment will focus on enhancing label performance under extreme environmental and operational conditions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand from Electronics and Semiconductor Industry
Polyimide component labels are essential for labeling sensitive electronic components due to their high thermal stability and chemical resistance. The rapid growth in production of printed circuit boards, semiconductors, and mobile devices, especially in Asia Pacific, is intensifying the need for durable, heat-resistant labeling solutions.
Expansion of Automotive and Aerospace Sectors
Automotive and aerospace industries require labels that can withstand extreme temperatures, vibration, and chemical exposure. As electric vehicles and advanced aircraft incorporate more sophisticated electronics, the demand for robust polyimide labels for identification and traceability is increasing.
Stringent Regulatory Compliance and Traceability Requirements
Tighter regulations around product traceability, safety, and quality control are pushing manufacturers to adopt high-performance labeling solutions. Polyimide labels meet strict industrial and environmental standards, making them critical for compliance and supply chain tracking in sectors like healthcare, defense, and electronics.
Integration of Smart Labeling Technologies
The adoption of RFID-enabled and smart polyimide labels is enhancing traceability, real-time monitoring, and inventory management in logistics-heavy sectors. This trend is driven by the shift toward Industry 4.0 and smart manufacturing, opening new opportunities for digital tracking and automation.
Sustainability and Eco-friendly Manufacturing
There is growing emphasis on developing recyclable and low-emission polyimide label alternatives. End-users are seeking to reduce their carbon footprint while maintaining durability and compliance, driving innovation in solvent-free adhesives and bio-based polymers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Polyimide Component Label Market?
What factors are driving the growth of the Polyimide Component Label Market?
What are some challenges faced by the Polyimide Component Label Market?
Who are the major players in the Polyimide Component Label Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Flexible Labels
- 1.2.2 Rigid Labels
- 1.3 By Application
- 1.3.1 Electronics
- 1.3.2 Automotive
- 1.3.3 Aerospace
- 1.3.4 Healthcare
- 1.3.5 Others
- 1.4 By Printing Technology
- 1.4.1 Digital Printing
- 1.4.2 Flexographic Printing
- 1.4.3 Screen Printing
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 788.0 million → 2032: USD 1,706.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polyimide Component Label Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polyimide Component Label Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polyimide Component Label Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polyimide Component Label Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polyimide Component Label Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polyimide Component Label Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polyimide Component Label Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polyimide Component Label Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 788.0 million → 2032: USD 1,706.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polyimide Component Label Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Flexible Labels
- 12.3.7.2 Rigid Labels
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Electronics
- 12.4.7.2 Automotive
- 12.4.7.3 Aerospace
- 12.4.7.4 Healthcare
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Printing Technology - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Digital Printing
- 12.5.7.2 Flexographic Printing
- 12.5.7.3 Screen Printing
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polyimide Component Label End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polyimide Component Label Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polyimide Component Label Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polyimide Component Label Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DuPont de Nemours, Inc.
- 18.4 Honeywell International Inc.
- 18.5 Brady Corporation
- 18.6 Avery Dennison Corporation
- 18.7 Henkel AG & Co. KGaA
- 18.8 CCL Industries Inc
- 18.9 FLEXcon Company, Inc.
- 18.10 Polyonics, Inc.
- 18.11 LINTEC Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

