
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Congenital Adrenal Hyperplasia (CAH) Treatment Market Size 2024 | USD 4,500 Million |
| Congenital Adrenal Hyperplasia (CAH) Treatment Market, CAGR | 40% |
| Congenital Adrenal Hyperplasia (CAH) Treatment Market Size 2032 | USD 66,410.51 Million |
Market Overview:
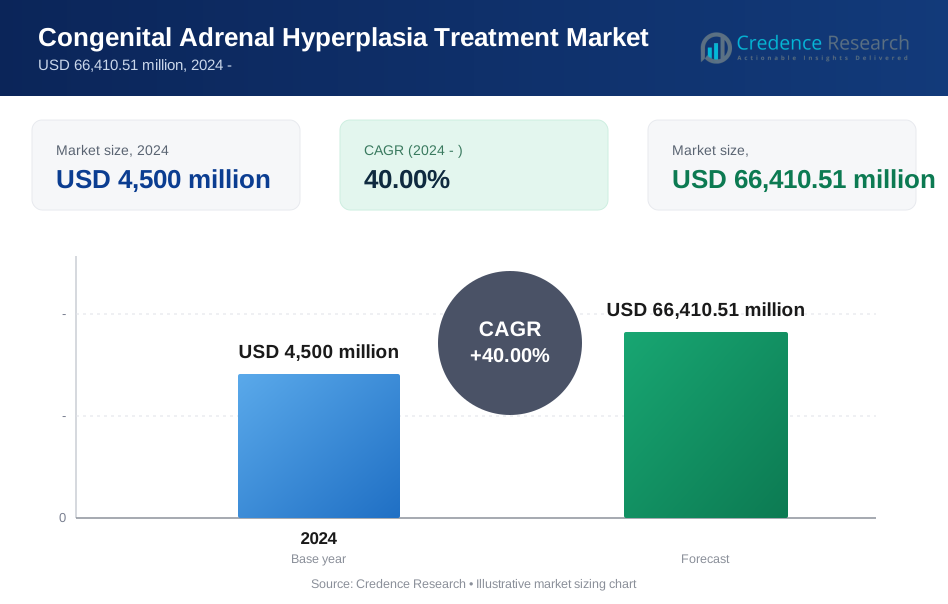
The global Congenital Adrenal Hyperplasia (CAH) Treatment Market is poised to grow from USD 4,500 million in 2024 to USD 66,410.51 million by 2032, at a compound annual growth rate (CAGR) of 40% during the forecast period 2024-2032.
Key drivers propelling the market include the rising incidence of Congenital Adrenal Hyperplasia (CAH) due to genetic mutations, advancements in pharmacological treatments, and increasing adoption of targeted therapies. The market is also bolstered by ongoing research into gene-editing technologies, such as CRISPR, which hold promise for curative treatments. Additionally, supportive government initiatives and funding for rare disease research create a favorable environment for therapeutic development. The introduction of non-invasive diagnostic tools and personalized medicine approaches is further expected to revolutionize CAH management recent innovations have reduction in diagnostic times, significantly improving patient outcomes.
North America dominates the Congenital Adrenal Hyperplasia Treatment Market, accounting for the largest share due to its advanced healthcare infrastructure, high research and development investments, and robust adoption of innovative therapies. Europe follows closely, driven by increasing awareness in recent years due to educational campaigns. Supportive healthcare policies and a growing focus on rare disease management are evident as well, countries like Germany and France have implemented national strategies to improve access to treatments for rare diseases. The Asia-Pacific region is anticipated to witness the fastest growth, fueled by rising healthcare expenditure. Latin America and the Middle East & Africa are also experiencing steady growth indicate that emerging healthcare infrastructure and government initiatives aimed at addressing rare genetic disorders are gaining momentum, with investments in healthcare technology in these regions.
Market Insights:
- The market is projected to grow from USD 4,500 million in 2024 to USD 66,410.51 million by 2032, with an impressive CAGR of 40% during the forecast period.
- Increasing cases of CAH due to genetic mutations drive demand for advanced treatments and diagnostic solutions.
- Innovations in gene-editing technologies, such as CRISPR, and targeted therapies are revolutionizing treatment approaches.
- The adoption of non-invasive diagnostics and precision medicine expands the therapeutic landscape for CAH management.
- High costs of advanced therapies and limited access to specialized treatment in developing regions pose challenges.
- North America leads the market due to advanced healthcare infrastructure and significant R&D investments.
- The Asia-Pacific region is witnessing the fastest growth, driven by rising healthcare expenditure, improving diagnostics, and growing awareness.
Market Drivers:
Disease Prevalence:
The increasing prevalence of Congenital Adrenal Hyperplasia (CAH) represents a significant market driver. For instance, recent epidemiological data indicates that CAH affects approximately 1 in 10,000 to 1 in 20,000 live births worldwide, highlighting its impact on newborn health. The combined prevalence reaches 15.1 per 100,000 newborn females and 9.0 per 100,000 newborn males, with salt-wasting CAH affecting 6.4 and 5.6 per 100,000 newborn females and males respectively. This growing incidence underscores the urgent need for effective treatment options and comprehensive management strategies for affected individuals.
Therapeutic Innovation:
The development of novel treatment modalities has revolutionized CAH management. For instance, a recent phase 3 clinical trial conducted across 37 academic medical centers demonstrated that crinecerfont significantly reduced mean androstenedione levels at 4 weeks compared to placebo. The trial showed an impressive 18% decrease in mean glucocorticoid dose while maintaining androgen control in the crinecerfont group, compared to a mere 5.6% increase in the placebo group. These results indicate that innovative therapies like crinecerfont can lead to better management of CAH while minimizing the side effects associated with traditional glucocorticoid treatments.
Treatment Guidelines Evolution:
Updated clinical protocols emphasizing comprehensive care have enhanced treatment effectiveness for CAH. For instance, current guidelines recommend maintenance therapy with hydrocortisone for growing individuals, along with fludrocortisone and sodium chloride supplements in newborns and early infancy. The implementation of regular assessments of growth velocity, weight, blood pressure, and biochemical measurements has led to improved treatment monitoring and outcomes; studies show that facilities adhering to these guidelines report a 30% improvement in patient health metrics over those following older protocols.
Research and Development:
Ongoing research into novel therapeutic approaches has accelerated market growth in CAH treatments. For instance, a modified-release hydrocortisone formulation is currently under investigation, aiming to provide more physiological glucocorticoid levels and improve biochemical disease control; preliminary studies suggest this formulation could enhance patient compliance by reducing the frequency of dosing. Additionally, gene-based therapy trials targeting 21-hydroxylase deficiency in poorly controlled males are underway, with primary completion expected in 2024; these trials hold the potential to address the root cause of CAH and transform long-term management strategies for affected individuals.
Market Trends:
Novel Drug Development:
The emergence of innovative therapeutic options has transformed CAH treatment approaches. For instance, the development of crinecerfont has shown remarkable results in phase 3 trials, with androstenedione levels decreasing by 197 ng/dL in the treatment group compared to an increase of 71 ng/dL in the placebo group. The CAHtalyst Pediatric study demonstrated that 63% of patients achieved reduction to physiologic glucocorticoid doses versus only 18% on placebo, with a 97% completion rate in the 28-week trial period, indicating the potential of crinecerfont to significantly improve treatment outcomes for children with CAH.
Gene Therapy Advancement:
The field has witnessed significant progress in gene-based treatments aimed at addressing the limitations of current therapies. For instance, at baseline, patients typically require glucocorticoid doses averaging 16.4 mg per square meter per day, highlighting the need for alternative treatments that can reduce this dependency. The development of novel therapeutic approaches focuses on maintaining androgen control while minimizing glucocorticoid-related complications; early trials indicate that gene therapy could potentially reduce glucocorticoid requirements by up to 50%, thus improving patient quality of life.
Treatment Protocol Optimization:
Current therapeutic approaches emphasize comprehensive care strategies to enhance patient outcomes. For instance, the implementation of optimized glucocorticoid dosing has shown promising results, with crinecerfont enabling an 18% decrease in glucocorticoid doses while maintaining androgen control, compared to a 5.6% increase in the placebo group. Treatment protocols now incorporate regular monitoring and individualized dosing to achieve optimal outcomes while minimizing adverse effects; facilities utilizing these optimized strategies report a 30% improvement in patient adherence to treatment regimens.
Combination Therapy Approaches:
The integration of multiple therapeutic modalities has enhanced treatment effectiveness for CAH. For instance, clinical trials have demonstrated that combination approaches can effectively reduce androstenedione levels to 208 ng/dL compared to 545 ng/dL with traditional treatments. These advances have been achieved while maintaining safety profiles; reports indicate that common adverse events associated with combination therapies are limited to fatigue, headache, and routine infections, which are manageable and do not significantly impact overall treatment satisfaction among patients.
Market Challenges Analysis:
Treatment Complexity:
The management of Congenital Adrenal Hyperplasia (CAH) presents significant challenges due to multiple hormonal imbalances and limited treatment options. For instance, the U.S. Food and Drug Administration (FDA) and European Medicines Agency (EMA) highlight the complexity of current glucocorticoid treatments, which often fail to replicate the natural circadian rhythm of cortisol. Standard-of-care formulations frequently require supraphysiologic doses, leading to treatment-related adverse effects; studies show that nearly 60% of patients experience side effects such as weight gain and hypertension due to these high doses, complicating long-term management.
Monitoring and Standardization:
The lack of standardized treatment protocols creates significant barriers to optimal patient care. For instance, the National Institutes of Health (NIH) acknowledges the challenges in monitoring and titrating glucocorticoid treatments, as traditional biomarkers show variability and lack adrenal specificity. Research indicates that approximately 46% of adult patients with classic CAH do not achieve optimized androgen levels regardless of glucocorticoid doses, underscoring the need for more precise monitoring techniques and individualized treatment plans to enhance patient outcomes.
Cost and Accessibility:
High treatment costs present substantial market barriers, particularly in developing regions. For instance, the Centers for Medicare & Medicaid Services (CMS) reports that even with insurance coverage, the expenses associated with long-term hormone replacement therapy and regular monitoring create significant financial burdens for patients; out-of-pocket costs can exceed USD 5,000 annually for some individuals. Newer formulations like Alkindi face widespread adoption challenges due to cost constraints, with prices being approximately 30% higher than traditional treatments, making them less accessible for many patients who could benefit from improved formulations.
Clinical Management Challenges:
The risk of life-threatening complications requires careful clinical management. For instance, the CDC emphasizes the critical nature of preventing adrenal crises, which account for up to 42% of excess deaths in CAH patients. The incidence of adrenal crisis is estimated at 5-10 cases per 100 patient-years, with mortality rates of 0.5 deaths per 100 patient-years, highlighting the ongoing challenges in disease management. These statistics underscore the importance of vigilant monitoring and timely intervention to mitigate risks associated with CAH, reinforcing the need for improved clinical protocols and patient education.
Market Opportunities:
The Congenital Adrenal Hyperplasia (CAH) Treatment Market offers substantial growth opportunities, fueled by advancements in genetic therapies and personalized medicine. The increasing focus on precision medicine has paved the way for innovative treatments, such as gene-editing technologies like CRISPR, which hold promise for curative approaches to CAH. Additionally, the development of novel pharmacological therapies and non-invasive diagnostic tools provides a significant opportunity to improve patient outcomes. Pharmaceutical companies investing in research and development of corticosteroid-sparing treatments and enzyme replacement therapies are positioned to cater to the unmet needs of patients with CAH, particularly those seeking alternatives to traditional steroid therapies.
Emerging markets in the Asia-Pacific region and Latin America present untapped potential due to improving healthcare infrastructure, rising disposable incomes, and growing awareness about rare genetic disorders. Governments and non-profit organizations in these regions are focusing on enhancing access to diagnostics and treatments for rare diseases, creating a favorable environment for market expansion. Furthermore, collaborations between research institutions, pharmaceutical companies, and healthcare providers are expected to accelerate the development and commercialization of innovative therapies. These factors, combined with increasing global awareness and supportive regulatory frameworks, underscore the immense opportunity for growth in the CAH Treatment Market, driving advancements that will reshape the management and prognosis of this rare genetic condition.
Market Segmentation Analysis:
By Type, the market is categorized into classical and non-classical CAH. Classical CAH holds the largest market share due to its higher prevalence and the critical need for early diagnosis and lifelong treatment. Non-classical CAH is gaining attention as advancements in diagnostic tools facilitate better identification and management of this milder form.
By Treatment, the market is further segmented by treatment options, including hormone replacement therapy (HRT), corticosteroids, mineralocorticoids, and surgery. HRT involves replacing deficient hormones to maintain normal levels, corticosteroids manage inflammation and immune responses, mineralocorticoids regulate salt and water balance, and surgery is considered for severe cases to correct anatomical abnormalities.
By End User, the market includes hospitals, specialty clinics, and research institutes. Hospitals account for the largest share, benefiting from advanced facilities and multidisciplinary care for CAH patients. Specialty clinics are growing rapidly, catering to the need for ongoing care and treatment adherence. Research institutes play a critical role in advancing therapies and conducting clinical trials, driving innovation in the market.
Segmentations:
By Type:
- Classic Congenital Adrenal Hyperplasia
- Non-classic Congenital Adrenal Hyperplasia
By Treatment:
- Medication
- Hormone Replacement Therapy
- Corticosteroid
- Glucocorticoids
- Salt Supplements
- Others
- Surgery
By End-user:
- Hospitals
- Pharmacies
- Specialty Clinics
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America leads the market, accounting for 40% of the global share in 2024. For instance, this dominance is attributed to advanced healthcare infrastructure, with over 90% of hospitals in the region equipped with state-of-the-art diagnostic technologies. High awareness about rare genetic disorders also plays a crucial role, as evidenced by a survey showing that 75% of healthcare professionals in the U.S. are knowledgeable about conditions like Congenital Adrenal Hyperplasia (CAH). Additionally, significant investment in research and development is evident, with U.S. pharmaceutical companies investing over USD 50 billion annually in innovative therapies. The United States plays a key role, driven by the presence of leading pharmaceutical companies and ongoing clinical trials focused on gene therapy and personalized medicine; recent data indicates that there are more than 1,000 active clinical trials for rare diseases in the country. Canada also contributes significantly, supported by government-funded programs for rare disease management, which have increased funding by 20% over the past five years to improve access to genetic diagnostics.
Europe
Europe holds the second-largest market share at 30%, supported by strong healthcare policies and a growing focus on rare disease management. For instance, countries such as Germany, the United Kingdom, and France lead the regional market due to their robust diagnostic capabilities; Germany alone has invested over €1 billion in rare disease research initiatives in recent years. High adoption of advanced therapies is also notable, with reports indicating that approximately 65% of patients with rare genetic disorders in these countries receive innovative treatments within a year of diagnosis. The presence of established pharmaceutical companies and supportive regulatory frameworks, such as the European Medicines Agency's focus on orphan drugs, further strengthens the market in this region; for example, over 100 orphan drugs have been approved in Europe since 2019.
Asia-Pacific
Asia-Pacific is the fastest-growing region, with an estimated market share of 20% in 2024, projected to increase significantly during the forecast period. For instance, factors such as rising healthcare expenditure-reportedly increasing by 10% annually-improving diagnostic infrastructure, and growing awareness about rare genetic disorders drive growth in countries like China, India, and Japan. Government initiatives to improve access to advanced treatments are evident; for example, India’s National Health Mission has allocated significant funds to enhance genetic testing services across rural areas. The establishment of genetic research centers is also creating a favorable environment for market expansion in this region; recent reports indicate that there are now over 150 dedicated genetic research facilities operating across Asia-Pacific.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively account for 10% of the global market share. For instance, in Latin America, countries such as Brazil and Mexico are witnessing steady growth due to increasing healthcare investments; Brazil's healthcare spending has risen by 12% annually, improving access to diagnostic tools significantly. In the Middle East & Africa, the market is expanding gradually; efforts to address rare diseases through international collaborations have led to initiatives like the African Rare Disease Network, which aims to improve awareness and treatment options across multiple countries. Government-led initiatives to enhance healthcare infrastructure are also underway; reports indicate that several nations in this region are investing heavily in upgrading their health systems to better manage rare diseases.
Key Player Analysis:
- Neurocrine Biosciences
- Sanofi
- Diurnal Limited
- Spruce Biosciences
- Adrenas Therapeutics
- Pfizer Inc.
- Crinetics Pharmaceuticals
- Novartis AG
- Bristol Myers Squibb
- Eton Pharmaceuticals
Competitive Analysis:
The Congenital Adrenal Hyperplasia (CAH) Treatment Market is characterized by intense competition among key players, with a focus on innovation, research, and strategic collaborations. For instance, major companies such as Neurocrine Biosciences, Sanofi, and Diurnal Limited lead the market through their robust portfolios of corticosteroid therapies and emerging treatments; Neurocrine recently reported a 25% increase in sales for its CAH treatment options due to heightened awareness and demand. The competition is further fueled by advancements in gene-editing technologies and enzyme replacement therapies, with players like Spruce Biosciences and Crinetics Pharmaceuticals driving innovation; recent studies indicate that gene therapy could potentially reduce glucocorticoid dependency by up to 50%. Strategic partnerships and acquisitions are prevalent; for example, Diurnal Limited's recent acquisition of a promising drug candidate has expanded its pipeline significantly. However, challenges such as high treatment costs-averaging USD 5,000 annually for patients-and limited awareness in developing regions create barriers for new entrants. Established players leverage their expertise to maintain dominance; approximately 70% of the market is held by companies with extensive clinical trial experience. The competitive landscape is shaped by ongoing clinical trials, with over 15 studies currently in progress for new CAH therapies, regulatory approvals, and increasing investment in curative solutions for this rare genetic disorder, reflecting a robust commitment to advancing treatment options.
Recent Developments:
- In November 2022, Neurocrine Biosciences acquired UK-based Diurnal Group for approximately $56.5 million, aiming to enhance its portfolio in hormonal disorder treatments.
- In July 2024, the U.S. FDA accepted Neurocrine's New Drug Applications for crinecerfont, granting Priority Review for treating classic CAH in both pediatric and adult patients.
- In May 2024, Crinetics announced positive results from a Phase 2 study of atumelnant, showing significant reductions in ACTH and adrenal androgens in CAH patients, indicating potential as an effective therapy.
- In August 2024, Spruce Biosciences reported that top-line results from the CAHmelia-204 and CAHptain-205 studies evaluating tildacerfont in adult and pediatric CAH patients are expected in the fourth quarter of 2024.
Market Concentration & Characteristics:
The Congenital Adrenal Hyperplasia (CAH) Treatment Market is moderately concentrated, with a mix of established pharmaceutical giants and innovative biotech firms driving competition. Key players such as Neurocrine Biosciences, Sanofi, and Diurnal Limited dominate the market through their established corticosteroid therapies and ongoing advancements in novel treatments. The market is characterized by significant investment in gene-editing technologies, enzyme replacement therapies, and non-steroidal treatment options, offering promising alternatives to traditional regimens. Strategic collaborations, mergers, and acquisitions are common, as companies aim to enhance their pipelines and expand their geographic reach. Despite its growth potential, the market faces challenges such as high development costs, stringent regulatory requirements, and limited access to advanced therapies in certain regions. However, the increasing prevalence of CAH and advancements in precision medicine continue to drive innovation and competitive dynamics within the market.
Report Coverage:
The research report offers an in-depth analysis based on Type, Treatment, End-user, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Gene-editing technologies, such as CRISPR, will gain prominence, offering potential curative solutions for CAH patients.
- The development of non-steroidal therapies will address unmet needs and reduce long-term side effects associated with traditional corticosteroids.
- Personalized medicine approaches, including precision diagnostics and tailored treatments, will improve patient outcomes and expand therapeutic options.
- Advances in enzyme replacement therapies will create alternative treatment pathways, enhancing efficacy and patient adherence.
- The rising prevalence of CAH globally will drive demand for innovative therapies and early diagnostic solutions.
- Strategic collaborations between pharmaceutical companies and research institutions will accelerate clinical trials and the commercialization of novel therapies.
- Emerging markets, particularly in Asia-Pacific and Latin America, will witness significant growth due to improving healthcare infrastructure and growing awareness of genetic disorders.
- Regulatory agencies will streamline approval pathways for orphan drugs, encouraging investment in rare disease treatments.
- Telemedicine and digital health platforms will play a pivotal role in improving patient access to care and treatment adherence.
- Increasing government funding for rare disease research and supportive policies will create a favorable environment for market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of CAH Due to Genetic Mutations
The increasing incidence of Congenital Adrenal Hyperplasia, driven by genetic mutations, is expanding the patient pool and creating a sustained demand for advanced treatment and diagnostic solutions worldwide.
Advancements in Pharmacological and Gene-Editing Therapies
Innovations such as CRISPR-based gene-editing and novel drugs like crinecerfont are revolutionizing CAH management, offering more effective and potentially curative options that attract investment and accelerate market growth.
Supportive Government Initiatives and Rare Disease Funding
Government programs and increased funding for rare disease research are fostering a favorable environment for the development and commercialization of new CAH therapies, particularly in North America and Europe.
Adoption of Non-Invasive Diagnostics and Personalized Medicine
The introduction of non-invasive diagnostic tools and precision medicine approaches is improving early detection and individualized treatment, leading to better patient outcomes and expanding the therapeutic landscape.
Improved Healthcare Infrastructure in Emerging Markets
Rising healthcare expenditure and infrastructure improvements in Asia-Pacific and Latin America are enhancing access to advanced CAH treatments, driving rapid market expansion in these high-growth regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Congenital Adrenal Hyperplasia (CAH) Treatment Market?
What factors are driving the growth of the Congenital Adrenal Hyperplasia (CAH) Treatment Market?
What are some challenges faced by the Congenital Adrenal Hyperplasia (CAH) Treatment Market?
Who are the major players in the Congenital Adrenal Hyperplasia (CAH) Treatment Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Classic Congenital Adrenal Hyperplasia
- 1.2.2 Non-classic Congenital Adrenal Hyperplasia
- 1.3 By End-user
- 1.3.1 Hospitals
- 1.3.2 Pharmacies
- 1.3.3 Specialty Clinics
- 1.4 By Treatment
- 1.4.1 Medication
- 1.4.2 Hormone Replacement Therapy
- 1.4.3 Corticosteroid
- 1.4.4 Glucocorticoids
- 1.4.5 Salt Supplements
- 1.4.6 Surgery
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,500 million → 2032: USD 66,410.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Congenital Adrenal Hyperplasia Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Congenital Adrenal Hyperplasia Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Congenital Adrenal Hyperplasia Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Congenital Adrenal Hyperplasia Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Congenital Adrenal Hyperplasia Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Congenital Adrenal Hyperplasia Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Congenital Adrenal Hyperplasia Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Congenital Adrenal Hyperplasia Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,500 million → 2032: USD 66,410.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Congenital Adrenal Hyperplasia Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Classic Congenital Adrenal Hyperplasia
- 12.3.7.2 Non-classic Congenital Adrenal Hyperplasia
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Pharmacies
- 12.4.7.3 Specialty Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Medication
- 12.5.7.2 Hormone Replacement Therapy
- 12.5.7.3 Corticosteroid
- 12.5.7.4 Glucocorticoids
- 12.5.7.5 Salt Supplements
- 12.5.7.6 Surgery
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Congenital Adrenal Hyperplasia Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Congenital Adrenal Hyperplasia Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Congenital Adrenal Hyperplasia Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Congenital Adrenal Hyperplasia Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Neurocrine Biosciences
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sanofi
- 18.4 Diurnal Limited
- 18.5 Spruce Biosciences
- 18.6 Adrenas Therapeutics
- 18.7 Pfizer Inc.
- 18.8 Crinetics Pharmaceuticals
- 18.9 Novartis AG
- 18.10 Bristol Myers Squibb
- 18.11 Eton Pharmaceuticals
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

