
Corneal Topographers Market Overview:
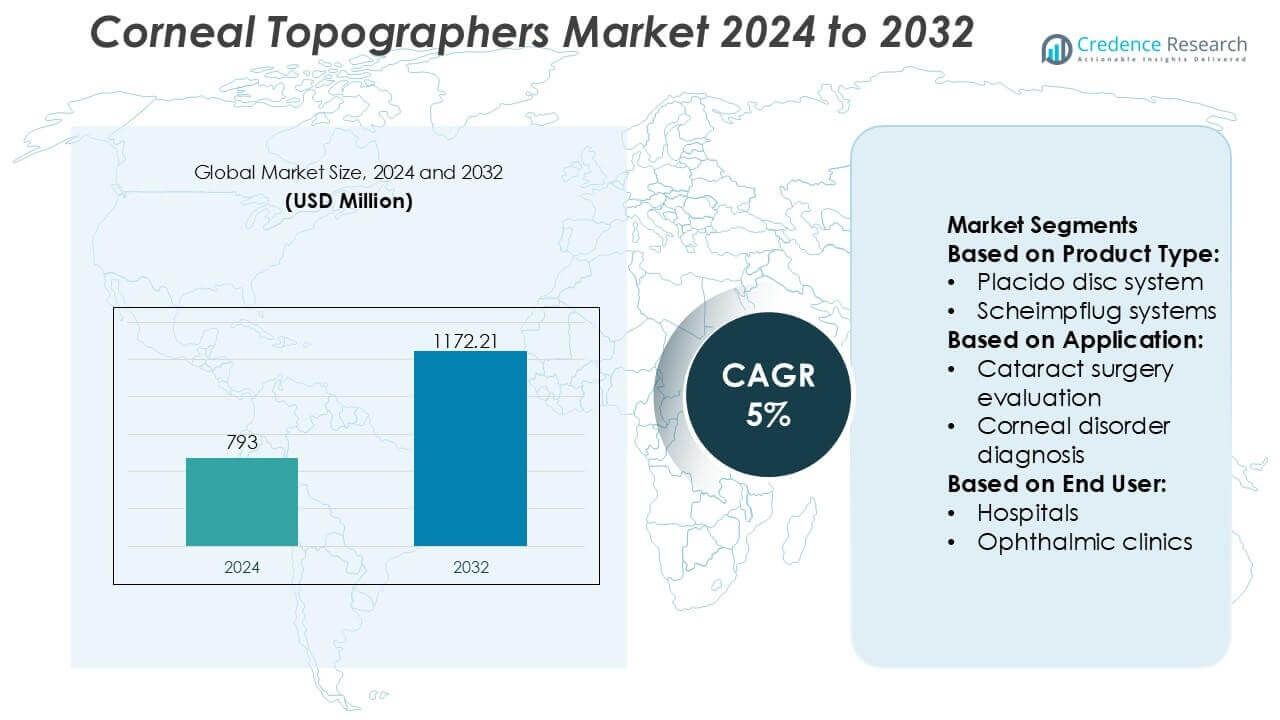
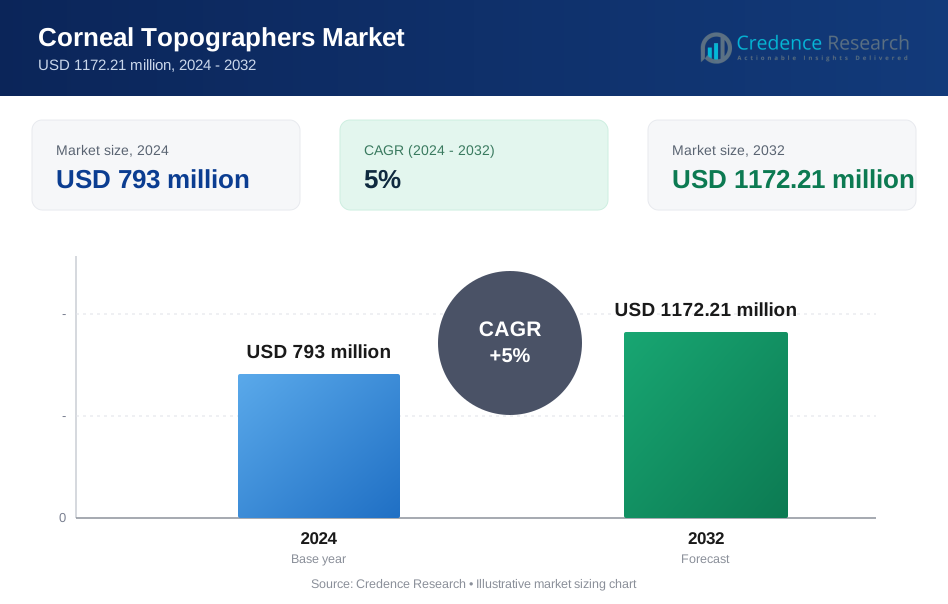
Corneal Topographers Market size was valued USD 793 million in 2024 and is anticipated to reach USD 1172.21 million by 2032, at a CAGR of 5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Corneal Topographers Market Size 2024 | USD 793 million |
| Corneal Topographers Market, CAGR | 5% |
| Corneal Topographers Market Size 2032 | USD 1172.21 million |
Corneal Topographers Market Insights
- Market growth is driven by rising refractive and cataract surgery volumes, increasing keratoconus screening, and strong demand for high-resolution corneal mapping and AI-enabled diagnostic accuracy in clinical practice.
- Key trends include integration of topography with surgical planning software, adoption of multimodal topography–tomography systems, and growing preference for workflow-efficient platforms in high-volume ophthalmic clinics.
- Competitive dynamics remain moderately consolidated, with leading players differentiating through software analytics, imaging precision, regulatory compliance, and long-term service support, while mid-tier players focus on cost-effective systems.
- Regionally, North America leads with a 38% market share, while Asia-Pacific shows fastest growth; by segment, Placido disc systems remain dominant with an estimated share of about 45% due to clinical familiarity and cost efficiency.
Corneal Topographers Market Segmentation Analysis:
By Product Type
The corneal topographers market by product type is led by Placido disc systems, which account for approximately 42% market share due to their widespread adoption in routine corneal curvature assessment and refractive screening. These systems are favored for their cost efficiency, fast data acquisition, and high repeatability in anterior corneal surface mapping. Scheimpflug systems follow, driven by their ability to generate three-dimensional corneal tomography and posterior surface data, supporting advanced diagnostics. Scanning slit systems maintain a niche presence, primarily used in academic and specialty settings requiring detailed corneal thickness profiling.
- For instance, Presbia utilizes Placido-disc–based corneal mapping, a gold standard for assessing corneal surface regularity. These systems capture data at approximately 22,000 discrete reflection points per scan (consistent with your "over 20,000" figure).
By Application
By application, refractive surgery evaluation represents the dominant sub-segment with nearly 34% market share, supported by rising volumes of LASIK and other vision-correction procedures globally. Accurate pre-operative corneal mapping is critical to surgical planning and risk mitigation, driving sustained demand. Corneal disorder diagnosis holds a significant share due to increasing prevalence of keratoconus and corneal ectasia, while cataract surgery evaluation benefits from growing premium intraocular lens adoption. Contact lens fitting also contributes steadily, as topography-guided fitting improves comfort, visual outcomes, and long-term patient compliance.
- For instance, AJL Ophthalmic’s corneal implants and diagnostic solutions are used alongside advanced topographic evaluation protocols that detect corneal thickness changes as small as 5–10 micrometers, supporting timely clinical intervention and post-implant follow-up in keratoconus management programs documented in company clinical use reports.
By End-User
Among end users, ophthalmic clinics dominate the market with an estimated 46% share, driven by high patient throughput, specialization in refractive and diagnostic eye care, and faster adoption of advanced diagnostic technologies. Clinics prioritize compact, user-friendly systems that integrate seamlessly into clinical workflows. Hospitals follow, supported by comprehensive ophthalmology departments and surgical volumes, while ambulatory surgery centers gain traction with the expansion of outpatient eye procedures. Other end users, including academic and research institutions, contribute modestly through training and clinical research activities.
Key Growth Drivers
Rising Prevalence of Refractive Errors and Corneal Disorders
The growing global burden of refractive errors, keratoconus, and other corneal irregularities is a primary driver for the corneal topographers market. Increasing screen exposure, aging populations, and lifestyle-related visual strain continue to elevate diagnostic demand. Corneal topographers play a critical role in early detection, disease staging, and longitudinal monitoring of corneal conditions, enabling clinicians to make precise, data-driven decisions. Their ability to generate detailed curvature, elevation, and thickness maps supports accurate diagnosis, strengthens clinical confidence, and drives consistent adoption across ophthalmic practices.
- For instance, San Diego Eye Bank’s tissue-recovery network and processing systems supported a major research study in which human retinal samples it supplied were used for molecular analyses involving immunoblot assays with specific markers such as phosphorylated RIP1 (Ser166) and RIP3 (Thr231/Ser232), demonstrating the utility of its donated tissues in advanced neurodegenerative research models.
Expansion of Refractive and Cataract Surgery Volumes
Rising demand for refractive and premium cataract surgeries significantly accelerates the adoption of corneal topographers. Surgeons increasingly rely on advanced corneal mapping to optimize preoperative planning, assess corneal stability, and select appropriate intraocular lenses. Accurate topographic data reduces surgical risk, improves visual outcomes, and enhances patient satisfaction. As elective eye procedures grow in both developed and emerging markets, clinics and hospitals continue to invest in reliable topography systems as essential diagnostic infrastructure.
- For instance, its Aurovue hydrophobic intraocular lens is engineered with a refractive index of 1.47 and enhanced optical design that minimizes chromatic aberration and facilitates controlled, flexible implantation during cataract surgery, advancing visual acuity performance in demanding surgical workflows.
Technological Advancements in Corneal Imaging Systems
Continuous innovation in imaging technologies strongly supports market growth. Modern corneal topographers integrate Placido-disc, Scheimpflug, and hybrid imaging modalities to deliver higher resolution, faster acquisition, and improved repeatability. Enhanced software analytics, automated reporting, and seamless integration with electronic medical records improve clinical workflow efficiency. These advancements lower operator dependency and expand usability across varied clinical settings, encouraging upgrades from legacy systems and supporting sustained replacement demand.
Key Trends & Opportunities
Integration of Multi-Modal and AI-Enabled Diagnostics
A key trend in the corneal topographers market is the integration of multi-modal imaging combined with artificial intelligence–driven analytics. AI-assisted pattern recognition enhances the detection of subtle corneal abnormalities and supports earlier diagnosis of progressive disorders. This trend improves diagnostic consistency across operators and creates opportunities for decision-support tools in refractive screening, postoperative monitoring, and disease progression analysis, particularly in high-volume ophthalmic centers.
- For instance, keratoconus earlier by leveraging topographic indices across >4,000 mapped corneal data points per eye combined with optical coherence tomography (OCT) elevation data, demonstrating improved sensitivity to early ectatic changes documented in clinical machine-learning workflows.
Growing Adoption in Emerging Healthcare Markets
Emerging economies present strong growth opportunities due to expanding ophthalmic infrastructure and increasing access to eye care services. Rising awareness of vision correction options and investments in private eye clinics support demand for advanced diagnostic equipment. Corneal topographers are increasingly adopted as standard-of-care tools in these regions, driven by improving reimbursement environments, growing medical tourism, and the expansion of specialty ophthalmology networks.
- For instance, The PRECISION7® 7-day contact lens utilizes the ACTIV-FLO® System, a sustained-release technology that replenishes moisture to provide 16 hours of comfort throughout a one-week replacement cycle.
Shift Toward Compact and Clinic-Friendly Systems
Manufacturers are increasingly focusing on compact, user-friendly corneal topographers designed for smaller clinics and ambulatory settings. Portable footprints, simplified interfaces, and faster examination times align with the needs of high-throughput practices. This trend supports wider penetration beyond large hospitals and creates opportunities for manufacturers to address underserved segments such as independent ophthalmic clinics and optometry centers.
Key Challenges
High Equipment Costs and Budget Constraints
The relatively high upfront cost of advanced corneal topography systems remains a key challenge, particularly for small clinics and facilities in cost-sensitive markets. Budget limitations can delay purchasing decisions or force reliance on older diagnostic technologies. Additionally, ongoing expenses related to software upgrades, maintenance, and calibration may further restrict adoption, especially where reimbursement for diagnostic procedures remains limited.
Need for Skilled Operation and Data Interpretation
Effective use of corneal topographers requires trained personnel capable of accurate image acquisition and clinical interpretation. Variability in operator expertise can affect data quality and diagnostic reliability. In regions facing shortages of skilled ophthalmic professionals, this challenge may limit optimal utilization of advanced systems. Addressing training gaps and simplifying interpretation through automation remains essential for broader market penetration.
Regional Analysis
North America
North America leads the corneal topographers market with an estimated 38% market share, supported by advanced ophthalmic infrastructure and high adoption of premium diagnostic technologies. Strong demand arises from large volumes of refractive and cataract surgeries, early uptake of AI-assisted corneal mapping, and widespread availability of skilled ophthalmologists. The United States dominates regional revenues due to routine pre- and post-operative corneal assessment standards, while Canada contributes steadily through modern eye-care facilities. Continuous investments by clinics in high-resolution and multimodal topography systems further reinforce North America’s leadership position.
Europe
Europe accounts for approximately 27% of the global corneal topographers market, driven by strong clinical adoption across Germany, France, the UK, Italy, and Spain. The region benefits from well-established public healthcare systems, rising screening for keratoconus, and growing refractive surgery volumes. European ophthalmic centers emphasize diagnostic accuracy and regulatory-compliant devices, supporting steady replacement demand for advanced topography platforms. Increased awareness of early corneal disorders and cross-border medical services also stimulate market growth, while Eastern Europe shows gradual expansion as access to specialized ophthalmic diagnostics improves.
Asia-Pacific
Asia-Pacific represents around 23% market share and is the fastest-growing regional market for corneal topographers. Growth is fueled by expanding ophthalmology infrastructure in China, India, Japan, and South Korea, alongside rising prevalence of myopia and corneal disorders. Rapid urbanization, increasing disposable income, and growing adoption of refractive surgeries drive demand for cost-effective yet technologically advanced systems. Government initiatives to improve eye-care access and the expansion of private ophthalmic chains further accelerate uptake, positioning Asia-Pacific as a key future growth engine.
Latin America
Latin America holds close to 7% of the global market, supported by improving access to specialized eye-care services in Brazil, Mexico, and Argentina. The region shows steady adoption of corneal topographers as private clinics expand refractive and cataract surgery offerings. Increasing awareness of corneal disease diagnosis and gradual modernization of ophthalmic equipment contribute to market growth. However, price sensitivity and uneven healthcare access across countries limit rapid penetration, resulting in moderate but consistent demand for mid-range and refurbished diagnostic systems.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% market share, with growth concentrated in the Gulf Cooperation Council countries and select African urban centers. Demand is driven by investments in advanced healthcare infrastructure, rising medical tourism, and increasing prevalence of diabetes-related ocular complications. Premium ophthalmology clinics in the Middle East adopt high-end corneal topography systems, while Africa shows emerging demand supported by international healthcare initiatives. Despite infrastructure gaps in some areas, gradual expansion of specialized eye-care services supports long-term market development.
Corneal Topographers Market Segmentations:
By Product Type:
- Placido disc system
- Scheimpflug systems
By Application:
- Cataract surgery evaluation
- Corneal disorder diagnosis
By End User:
- Hospitals
- Ophthalmic clinics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the corneal topographers market players such as , AJL Ophthalmic S.A., San Diego Eye Bank, Aurolab, KeraMed, Inc., Alcon Inc., DIOPTEX, Florida Lions Eye Bank, CorneaGen. The corneal topographers market features a moderately consolidated competitive landscape shaped by technological innovation, clinical accuracy, and strong service networks. Manufacturers primarily compete on high-resolution imaging, advanced corneal mapping algorithms, and software platforms that support refractive surgery planning and early diagnosis of corneal disorders. Continuous upgrades in AI-assisted analysis, multimodal imaging integration, and user-friendly interfaces enhance product differentiation. Companies also emphasize regulatory compliance, after-sales support, and clinician training to strengthen long-term relationships with hospitals and ophthalmic clinics. Strategic collaborations with research institutions and eye-care centers accelerate validation and adoption of new systems. Overall, competitive intensity remains steady, with innovation, reliability, and cost-effectiveness serving as the key determinants of market positioning and global expansion.
Key Player Analysis
- Presbia PLC
- AJL Ophthalmic S.A.
- San Diego Eye Bank
- Aurolab
- KeraMed, Inc.
- Alcon Inc.
- DIOPTEX
- Florida Lions Eye Bank
- CorneaGen
- Massachusetts Eye and Ear
Recent Developments
- In February 2025, OCULUS launched the Myopia Software Package for Pentacam AXL Wave, merging axial length and corneal tomography for integrated management. The new software is designed to offer optometrists unparalleled accuracy, ease, and safety in their myopia management, comprehensive screening.
- In December 2024, EssilorLuxottica signs an agreement to acquire Espansione Group for accelerating its growth in the med-tech space. EssilorLuxottica agreed to acquire Espansione Group, adding non-invasive ophthalmic treatment devices.
- In September 2023, GitHub's Innovation Graph is an open data platform providing interactive insights into public software development trends and the global impact of developers, particularly for researchers and policymakers.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of AI-driven corneal analysis will increase to support earlier and more accurate detection of corneal disorders.
- Integration of corneal topographers with refractive and cataract surgery planning systems will become standard practice.
- Demand will rise for multimodal devices combining topography, tomography, and pachymetry in a single platform.
- Portable and compact corneal topographers will gain traction in outpatient clinics and ambulatory settings.
- Software upgrades with cloud-based data storage and remote access will improve clinical workflow efficiency.
- Growing prevalence of myopia and keratoconus will sustain long-term diagnostic demand across age groups.
- Emerging markets will favor cost-effective systems with scalable functionality and local service support.
- Regulatory emphasis on diagnostic accuracy will encourage replacement of legacy imaging systems.
- Collaboration between manufacturers and ophthalmic research centers will accelerate technology validation.
- Increased patient awareness of preventive eye care will support routine corneal screening adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Refractive Errors and Corneal Disorders
Increasing rates of myopia, keratoconus, and other corneal irregularities are driving demand for advanced diagnostic tools like corneal topographers. These devices enable early detection and precise monitoring, supporting better clinical outcomes and expanding their adoption in routine eye care.
Expansion of Refractive and Cataract Surgery Volumes
The global increase in elective vision correction and premium cataract surgeries necessitates accurate preoperative corneal mapping. Corneal topographers are essential for surgical planning, risk mitigation, and optimal lens selection, making them a critical investment for clinics and hospitals.
Technological Advancements in Corneal Imaging Systems
Continuous innovation, such as integration of Placido-disc and Scheimpflug imaging, AI-driven analytics, and multimodal platforms, enhances diagnostic accuracy and workflow efficiency. These advancements encourage upgrades from legacy systems and broaden the appeal to a wider range of clinical settings.
Growing Adoption in Emerging Healthcare Markets
Expanding ophthalmic infrastructure, rising awareness of eye health, and increasing access to private eye care in emerging economies are fueling demand for cost-effective and technologically advanced corneal topographers. Improved reimbursement and medical tourism further support market growth in these regions.
Shift Toward Compact and Clinic-Friendly Systems
Manufacturers are developing portable, user-friendly corneal topographers tailored for high-throughput clinics and ambulatory settings. This trend enables broader market penetration, especially among independent practices and smaller healthcare facilities seeking efficient diagnostic solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Corneal Topographers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Corneal Topographers Market projected to grow between 2024 and 2032?
Which Corneal Topographers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Corneal Topographers Market?
Who are the leading companies in the Corneal Topographers Market?
Which region commanded the largest share of the Corneal Topographers Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Ophthalmic clinics
- 1.2.2 Hospitals
- 1.2.3 Ambulatory surgery centers
- 1.2.4 Academic and research institutions
- 1.3 By Application
- 1.3.1 Refractive surgery evaluation
- 1.3.2 Corneal disorder diagnosis
- 1.3.3 Cataract surgery evaluation
- 1.3.4 Contact lens fitting
- 1.4 By Product Type
- 1.4.1 Placido disc system
- 1.4.2 Scheimpflug systems
- 1.4.3 Scanning slit systems
- 1.4.4 Hybrid/multimodal systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 793 million → 2032: USD 1172.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Corneal Topographers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Corneal Topographers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Corneal Topographers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Corneal Topographers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Corneal Topographers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Corneal Topographers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Corneal Topographers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Corneal Topographers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 793 million → 2032: USD 1172.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Corneal Topographers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Ophthalmic clinics
- 12.3.7.2 Hospitals
- 12.3.7.3 Ambulatory surgery centers
- 12.3.7.4 Academic and research institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Refractive surgery evaluation
- 12.4.7.2 Corneal disorder diagnosis
- 12.4.7.3 Cataract surgery evaluation
- 12.4.7.4 Contact lens fitting
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Placido disc system
- 12.5.7.2 Scheimpflug systems
- 12.5.7.3 Scanning slit systems
- 12.5.7.4 Hybrid/multimodal systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Corneal Topographers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Corneal Topographers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Corneal Topographers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Corneal Topographers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Alcon Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Presbia PLC
- 18.4 AJL Ophthalmic S.A.
- 18.5 Aurolab
- 18.6 KeraMed, Inc.
- 18.7 DIOPTEX
- 18.8 CorneaGen
- 18.9 EssilorLuxottica
- 18.10 OCULUS
- 18.11 Topcon Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

