
Market Overview
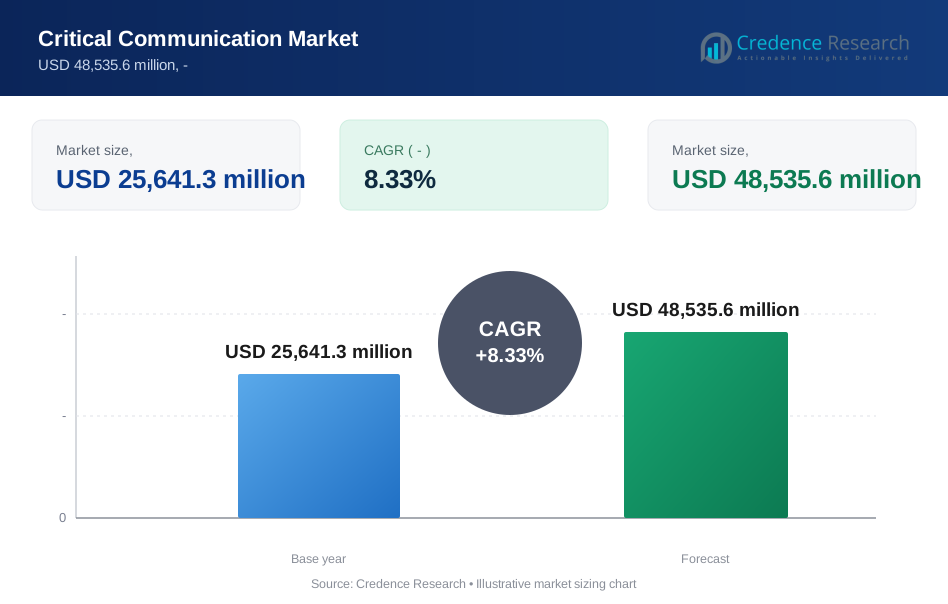
The Critical Communication Market size was valued at USD 15,780.1 million in 2018, increased to USD 25,641.3 million in 2024, and is anticipated to reach USD 48,535.6 million by 2032, at a CAGR of 8.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Critical Communication Market Size 2024 | USD 25,641.3 million |
| Critical Communication Market, CAGR | 8.33% |
| Critical Communication Market Size 2032 | USD 48,535.6 million |
The critical communication market is driven by key players such as Motorola Solutions Inc., Ericsson, Nokia, Huawei, AT&T Inc., L3Harris Technologies, Inc., Inmarsat, JVCKENWOOD Corporation, Tait Communications, Mentura Group, and Telstra. Motorola Solutions Inc. and L3Harris Technologies hold strong positions due to their comprehensive product portfolios and continuous advancements in LTE-based solutions. Nokia, Ericsson, and Huawei contribute significantly with their broadband and next-generation communication technologies. Regionally, Asia Pacific leads the market, accounting for 19.4% of the global market share in 2018, driven by rapid infrastructure development and increasing public safety investments in countries like China, Japan, and India. North America and Europe follow closely, supported by mature public safety frameworks and the early adoption of advanced communication systems. These leading players and regions collectively shape the competitive and growth dynamics of the global critical communication market.

Market Insights
- The critical communication market was valued at USD 15,780.1 million in 2018, reached USD 25,641.3 million in 2024, and is projected to reach USD 48,535.6 million by 2032, growing at a CAGR of 8.33% during the forecast period.
- Growing demand for secure, reliable, and real-time communication in public safety, transportation, and energy sectors is a key market driver, supported by government investments in upgrading emergency response networks.
- The market is witnessing a strong trend towards the adoption of LTE-based and broadband critical communication systems, offering enhanced data capabilities and multimedia support over traditional LMR systems.
- The competitive landscape is shaped by leading players such as Motorola Solutions Inc., Nokia, Ericsson, Huawei, and L3Harris Technologies, focusing on product innovation and LTE integration, while high infrastructure costs and spectrum allocation challenges restrain market growth.
- Asia Pacific holds the largest regional share at 19.4% in 2018, while the hardware segment leads by product due to the increasing demand for durable communication devices.
Market Segmentation Analysis:
By Product:
The product segment of the critical communication market is categorized into hardware, software, and services. Among these, the hardware segment dominates the market, accounting for a significant share owing to the high demand for reliable and robust communication devices such as two-way radios and base stations. The increasing need for uninterrupted and secure communication in emergency services and mission-critical operations continues to drive hardware adoption. Additionally, advancements in device durability and network compatibility contribute to the sustained dominance of the hardware sub-segment across various industries.
- For instance, Motorola Solutions Inc. delivered over 3 million APX radios globally, known for their durability and interoperability with both legacy and advanced communication networks.
By Technology
In terms of technology, the Land Mobile Radio (LMR) segment holds the largest market share due to its widespread deployment in public safety and emergency response sectors. LMR systems are valued for their reliability, instant push-to-talk capabilities, and coverage in remote areas, which are crucial in critical situations. The growing need for seamless communication in disaster management and law enforcement has further solidified LMR’s position as the leading technology. However, Long-Term Evolution (LTE) is gaining traction for its high-speed data transmission, supporting multimedia applications and broader connectivity.
- For instance, L3Harris Technologies deployed more than 500,000 P25 LMR units across North America for public safety agencies.
By End User
Across the end-user segment, public safety and government agencies represent the largest share of the critical communication market. These organizations prioritize dependable, fast, and secure communication solutions for first responders, police, firefighting units, and disaster management teams. The increasing frequency of natural disasters, security threats, and large-scale public events has significantly driven the demand for critical communication systems within this sub-segment. Moreover, substantial government investments to upgrade emergency communication infrastructure and integrate advanced technologies further bolster the growth of this dominant end-user group.
Market Overview
Increasing Demand for Public Safety Communication
The rising focus on public safety and disaster response is significantly driving the critical communication market. Government agencies and emergency services require reliable, instant, and secure communication systems to manage crises efficiently. Growing urbanization, frequent natural disasters, and escalating security threats have compelled countries to invest in modernizing their communication infrastructure. Advanced solutions like LTE-enabled networks and digital LMR systems are being rapidly deployed to enhance communication capabilities in mission-critical scenarios, supporting the increasing need for public safety across the globe.
- For instance, Ericsson supported the implementation of the FirstNet public safety network in the U.S., which now connects over 5 million emergency responders across 20,000 agencies.
Technological Advancements in Communication Networks
Continuous technological advancements in critical communication systems are a major growth driver. The integration of LTE, 5G readiness, IP-based solutions, and multimedia-enriched services is transforming the landscape, enabling high-speed data transfer, video streaming, and real-time situational awareness. Manufacturers are focusing on developing compact, durable, and interoperable devices that support both legacy systems and next-generation networks. These innovations not only improve coverage and connectivity but also support multi-agency collaboration, driving adoption across sectors such as transportation, energy, and public safety.
- For instance, Huawei’s eLTE broadband trunking solution, deployed in over 100 global projects, enables video-based emergency response with end-to-end network reliability.
Rising Adoption Across Industrial Sectors
The critical communication market is witnessing growing adoption in industries beyond public safety, such as transportation, mining, and energy & utilities. These sectors rely on robust communication systems to maintain operational safety, manage remote workforces, and ensure process efficiency in hazardous environments. For instance, oil and gas operations in remote locations require seamless communication for emergency management and routine coordination. The need for reliable, latency-free communication to support industrial automation and workforce safety is expected to sustain the market's growth trajectory.
Key Trends & Opportunities
Shift Towards Broadband and LTE-Based Solutions
The transition from traditional LMR to broadband and LTE-based solutions presents significant growth opportunities in the critical communication market. LTE offers higher data speeds, broader coverage, and supports multimedia applications, enabling agencies to enhance situational awareness through video, location tracking, and real-time data sharing. Public safety agencies are increasingly investing in LTE-enabled networks, opening avenues for vendors to offer integrated, next-generation critical communication solutions that bridge the gap between voice-centric systems and data-driven operations.
- For instance, AT&T’s LTE-based FirstNet has achieved nationwide coverage across the U.S., with more than 4,500 public safety agencies actively utilizing the network’s mission-critical push-to-talk services.
Growing Integration of IoT and AI in Critical Communications
The integration of IoT and AI technologies is reshaping the critical communication landscape by enabling predictive analytics, intelligent network management, and automated emergency responses. IoT sensors can trigger immediate alerts in hazardous environments, while AI-driven analytics improve decision-making and incident management. This convergence supports real-time monitoring, enhances system reliability, and drives the demand for intelligent, data-driven communication solutions. The adoption of these technologies presents key opportunities for market players to deliver value-added, future-ready products.
- For instance, Nokia’s AI-powered AVA cognitive services platform has been deployed in over 150 networks to automate fault prediction and network optimization, enhancing emergency communication reliability.
Key Challenges
High Infrastructure and Deployment Costs
One of the primary challenges in the critical communication market is the high cost of deploying and maintaining advanced communication networks. Building infrastructure that ensures extensive coverage, system redundancy, and cybersecurity requires substantial capital investment. Budget constraints, particularly in developing countries and small-scale industries, often hinder the timely adoption of these systems. Additionally, the complexity of integrating new technologies with existing legacy systems further increases the overall deployment cost.
Spectrum Availability and Regulatory Barriers
Limited spectrum availability and varying regulatory frameworks across regions pose significant barriers to market expansion. Critical communication systems require dedicated, interference-free spectrum bands to function effectively. However, the allocation and management of such spectrum are strictly regulated and differ from country to country, delaying network deployments. Moreover, public safety agencies often face challenges in acquiring spectrum licenses, leading to operational constraints and reduced efficiency in communication networks.
Interoperability Issues with Legacy Systems
Interoperability between modern communication technologies and legacy systems remains a persistent challenge. Many organizations, particularly public safety agencies, still rely on older LMR networks that are not fully compatible with newer broadband or LTE-based systems. This creates fragmented communication environments that can hinder coordination during multi-agency responses. Developing solutions that ensure seamless connectivity across diverse platforms and devices is essential to overcoming this challenge and ensuring the efficiency of critical communication operations.
Regional Analysis
North America
North America held a significant position in the critical communication market, valued at USD 3,646.79 million in 2018, and is projected to reach USD 9,707.11 million by 2032, expanding at a CAGR of 7.2% during the forecast period. The region accounted for approximately 14.8% of the global market share in 2018 and is driven by strong investments in public safety, government initiatives, and early adoption of advanced communication technologies. Increasing demand from emergency response services, defense sectors, and industrial safety applications continues to propel market growth across the United States and Canada.
Europe
Europe accounted for a substantial share in the critical communication market, valued at USD 4,153.33 million in 2018, growing to an anticipated USD 13,162.84 million by 2032, at a CAGR of 8.6%. The region represented approximately 16.5% of the global market share in 2018, supported by stringent regulatory policies on public safety and the rapid modernization of communication infrastructures. Extensive deployment of digital LMR systems and increasing investments in broadband-based critical communications, particularly in countries such as Germany, the UK, and France, continue to strengthen Europe’s position in the global market.
Asia Pacific
Asia Pacific emerged as the largest regional market in 2018 with a valuation of USD 4,805.05 million, contributing approximately 19.4% of the global market share. The market is forecasted to reach USD 16,016.74 million by 2032, registering the highest CAGR of 8.9% during the forecast period. Rapid urbanization, growing public infrastructure, and increased government focus on disaster management and emergency services are the key drivers in this region. Countries like China, Japan, and India are leading the adoption of LTE-based critical communication systems, boosting market expansion across industrial and public safety applications.
Latin America
The critical communication market in Latin America was valued at USD 1,775.27 million in 2018, capturing around 7.2% of the global market share, and is expected to reach USD 5,503.93 million by 2032, growing at a CAGR of 8.4%. The market benefits from increasing investments in upgrading emergency response networks, particularly in Brazil and Mexico. The adoption of modern communication technologies in transportation, energy, and mining sectors further supports regional growth. Additionally, the rising need for efficient disaster management systems due to the region’s vulnerability to natural calamities continues to fuel market demand.
Middle East
The Middle East critical communication market was valued at USD 852.13 million in 2018, accounting for approximately 3.4% of the global market share. It is projected to reach USD 2,674.31 million by 2032, progressing at a CAGR of 8.5%. Growing investments in smart city projects and security infrastructure, particularly in the UAE and Saudi Arabia, are enhancing the demand for reliable and secure communication systems. The region’s focus on modernizing public safety networks and increasing deployment of LTE-based communication platforms are further driving market growth across critical sectors, including oil and gas.
Africa
Africa's critical communication market was valued at USD 547.57 million in 2018, representing approximately 2.2% of the global market share. The market is expected to reach USD 1,470.63 million by 2032, expanding at a CAGR of 7.3%. Market growth in Africa is primarily supported by government-led public safety initiatives and increasing demand for improved communication infrastructure in mining and energy sectors. While market penetration is still developing, several African nations are gradually investing in emergency communication systems, with a focus on enhancing disaster response capabilities and supporting industrial safety in remote and high-risk areas.

Market Segmentations:
By Product
- Hardware
- Software
- Services
By Technology
- Land Mobile Radio (LMR)
- Long-Term Evolution (LTE)
- Group Call System Enablers (GCSE)
- Enhanced Multimedia Broadcast/Multicast Service (eMBMS)
- Others
By End User
- Public Safety and Government Agencies
- Transportation
- Energy and Utilities
- Mining
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The critical communication market is highly competitive, with major players focusing on technological advancements, strategic partnerships, and product innovation to strengthen their market positions. Companies such as Motorola Solutions Inc., Ericsson, Nokia, Huawei, and AT&T Inc. dominate the landscape, offering comprehensive portfolios that include hardware, software, and LTE-enabled solutions tailored for mission-critical applications. These industry leaders are heavily investing in next-generation broadband technologies, seamless interoperability, and integrated platforms that support multi-agency communication. Additionally, firms like L3Harris Technologies, Inmarsat, and JVCKENWOOD Corporation are enhancing their global presence through mergers, acquisitions, and regional expansions. The market also features niche players such as Tait Communications, Mentura Group, and Telstra, which focus on customized solutions for specific industries and regional markets. Continuous innovation, high reliability, and stringent regulatory compliance remain key competitive factors, driving companies to develop future-ready systems that meet the evolving demands of public safety, transportation, and industrial sectors.
Key Player Analysis
- Motorola Solutions Inc.
- Ericsson
- Nokia
- Huawei
- AT&T Inc
- L3Harris Technologies, Inc.
- Inmarsat
- JVCKENWOOD Corporation
- Tait Communications
- Mentura Group
- Telstra
Recent Developments
- In June 2025, during the Critical Communications World (CCW) event in Brussels, Ericsson introduced a new range of antennas specifically developed for Public Protection and Disaster Relief (PPDR) networks. These antennas are engineered to deliver secure, reliable coverage tailored to mission-critical communication needs.
- In January 2023, Airbus and M1 launched the first 5G aerial standalone trial in Singapore, marking a significant advancement in technology. This collaboration aimed to explore the capabilities of 5G in applications such as Unmanned Aerial Vehicles (UAVs), aerial surveillance, and enhanced communications. The trial underscored Singapore's leadership in adopting innovative technological solutions.
- In April 2022, Ericsson acquired Genaker, a company specializing in Mission Critical Push-to-Talk (MCPTT) solutions. This acquisition was made to bolster Ericsson's end-to-end portfolio of mission-critical offerings, according to Ericsson. Genaker, based in Barcelona, Spain, focuses on delivering MC-PTT solutions, which are crucial for public safety and other mission-critical applications.
- In February 2022, Radisys released its 5G IoT Software Suite for organizations and telecommunications providers to facilitate the deployment and management of IoT applications across 5G networks. This suite takes advantage of 5G technology's high speed, low latency, and huge connectivity capabilities to cater to the demanding requirements of IoT use ca
Market Conentration & Characteristics
The Critical Communication Market demonstrates a moderately concentrated structure, with a few dominant players controlling a significant portion of the global market. Key companies, including Motorola Solutions Inc., Ericsson, Nokia, Huawei, and L3Harris Technologies, maintain strong competitive positions through extensive product portfolios, advanced technology, and established customer relationships. It is characterized by high entry barriers due to substantial infrastructure costs, strict regulatory requirements, and the need for proven system reliability. The market favors companies with the ability to offer integrated, mission-critical solutions across hardware, software, and LTE-based systems. Demand for robust, real-time, and secure communication continues to shape product development and strategic partnerships. It supports long-term contracts, particularly in public safety and industrial sectors, which limits frequent supplier changes and increases customer retention. The market shows strong regional concentration in Asia Pacific, North America, and Europe, where governments and enterprises prioritize public safety investments and digital communication upgrades. Competition focuses on innovation, system interoperability, and expanding LTE capabilities.
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The critical communication market will experience steady growth driven by increasing demand for secure and reliable communication in public safety and emergency services.
- Adoption of LTE and broadband technologies will accelerate, offering faster data transmission and enhanced multimedia support.
- Integration of artificial intelligence and IoT will improve real-time monitoring, predictive analytics, and automated emergency responses.
- The market will see rising investments in upgrading legacy communication systems to advanced digital platforms.
- Asia Pacific will remain the leading region due to rapid urbanization, infrastructure development, and increasing public safety initiatives.
- Industries such as transportation, mining, and energy will expand their use of critical communication systems to improve operational safety.
- Interoperability solutions will gain importance to ensure seamless communication across diverse devices and networks.
- The need for highly durable, compact, and interoperable hardware will continue to drive product development.
- Spectrum allocation and regulatory challenges will influence market expansion, especially in developing regions.
- Strategic partnerships and technological innovation will remain key focus areas for market leaders to strengthen their global presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Critical Communication market in 2023 and 2032?
What are the key drivers of growth in the Critical Communication market?
What technologies are driving innovation in the Critical Communication market?
Who are the key players in the Critical Communication market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Critical Communication Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Critical Communication Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 25,641.3 million → forecast year: USD 48,535.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Critical Communication Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Critical Communication Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Critical Communication Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Critical Communication Market Drivers
- 3.3 Critical Communication Market Restraints & Challenges
- 3.4 Critical Communication Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Critical Communication Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Critical Communication Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Critical Communication category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Critical Communication Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Critical Communication Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Critical Communication market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Critical Communication Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Critical Communication Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Critical Communication Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Critical Communication (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Critical Communication Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Critical Communication Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Critical Communication Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Critical Communication Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Critical Communication Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Critical Communication Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Critical Communication Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Critical Communication Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Critical Communication Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
