
Satellites, radomes and chip packages define demand
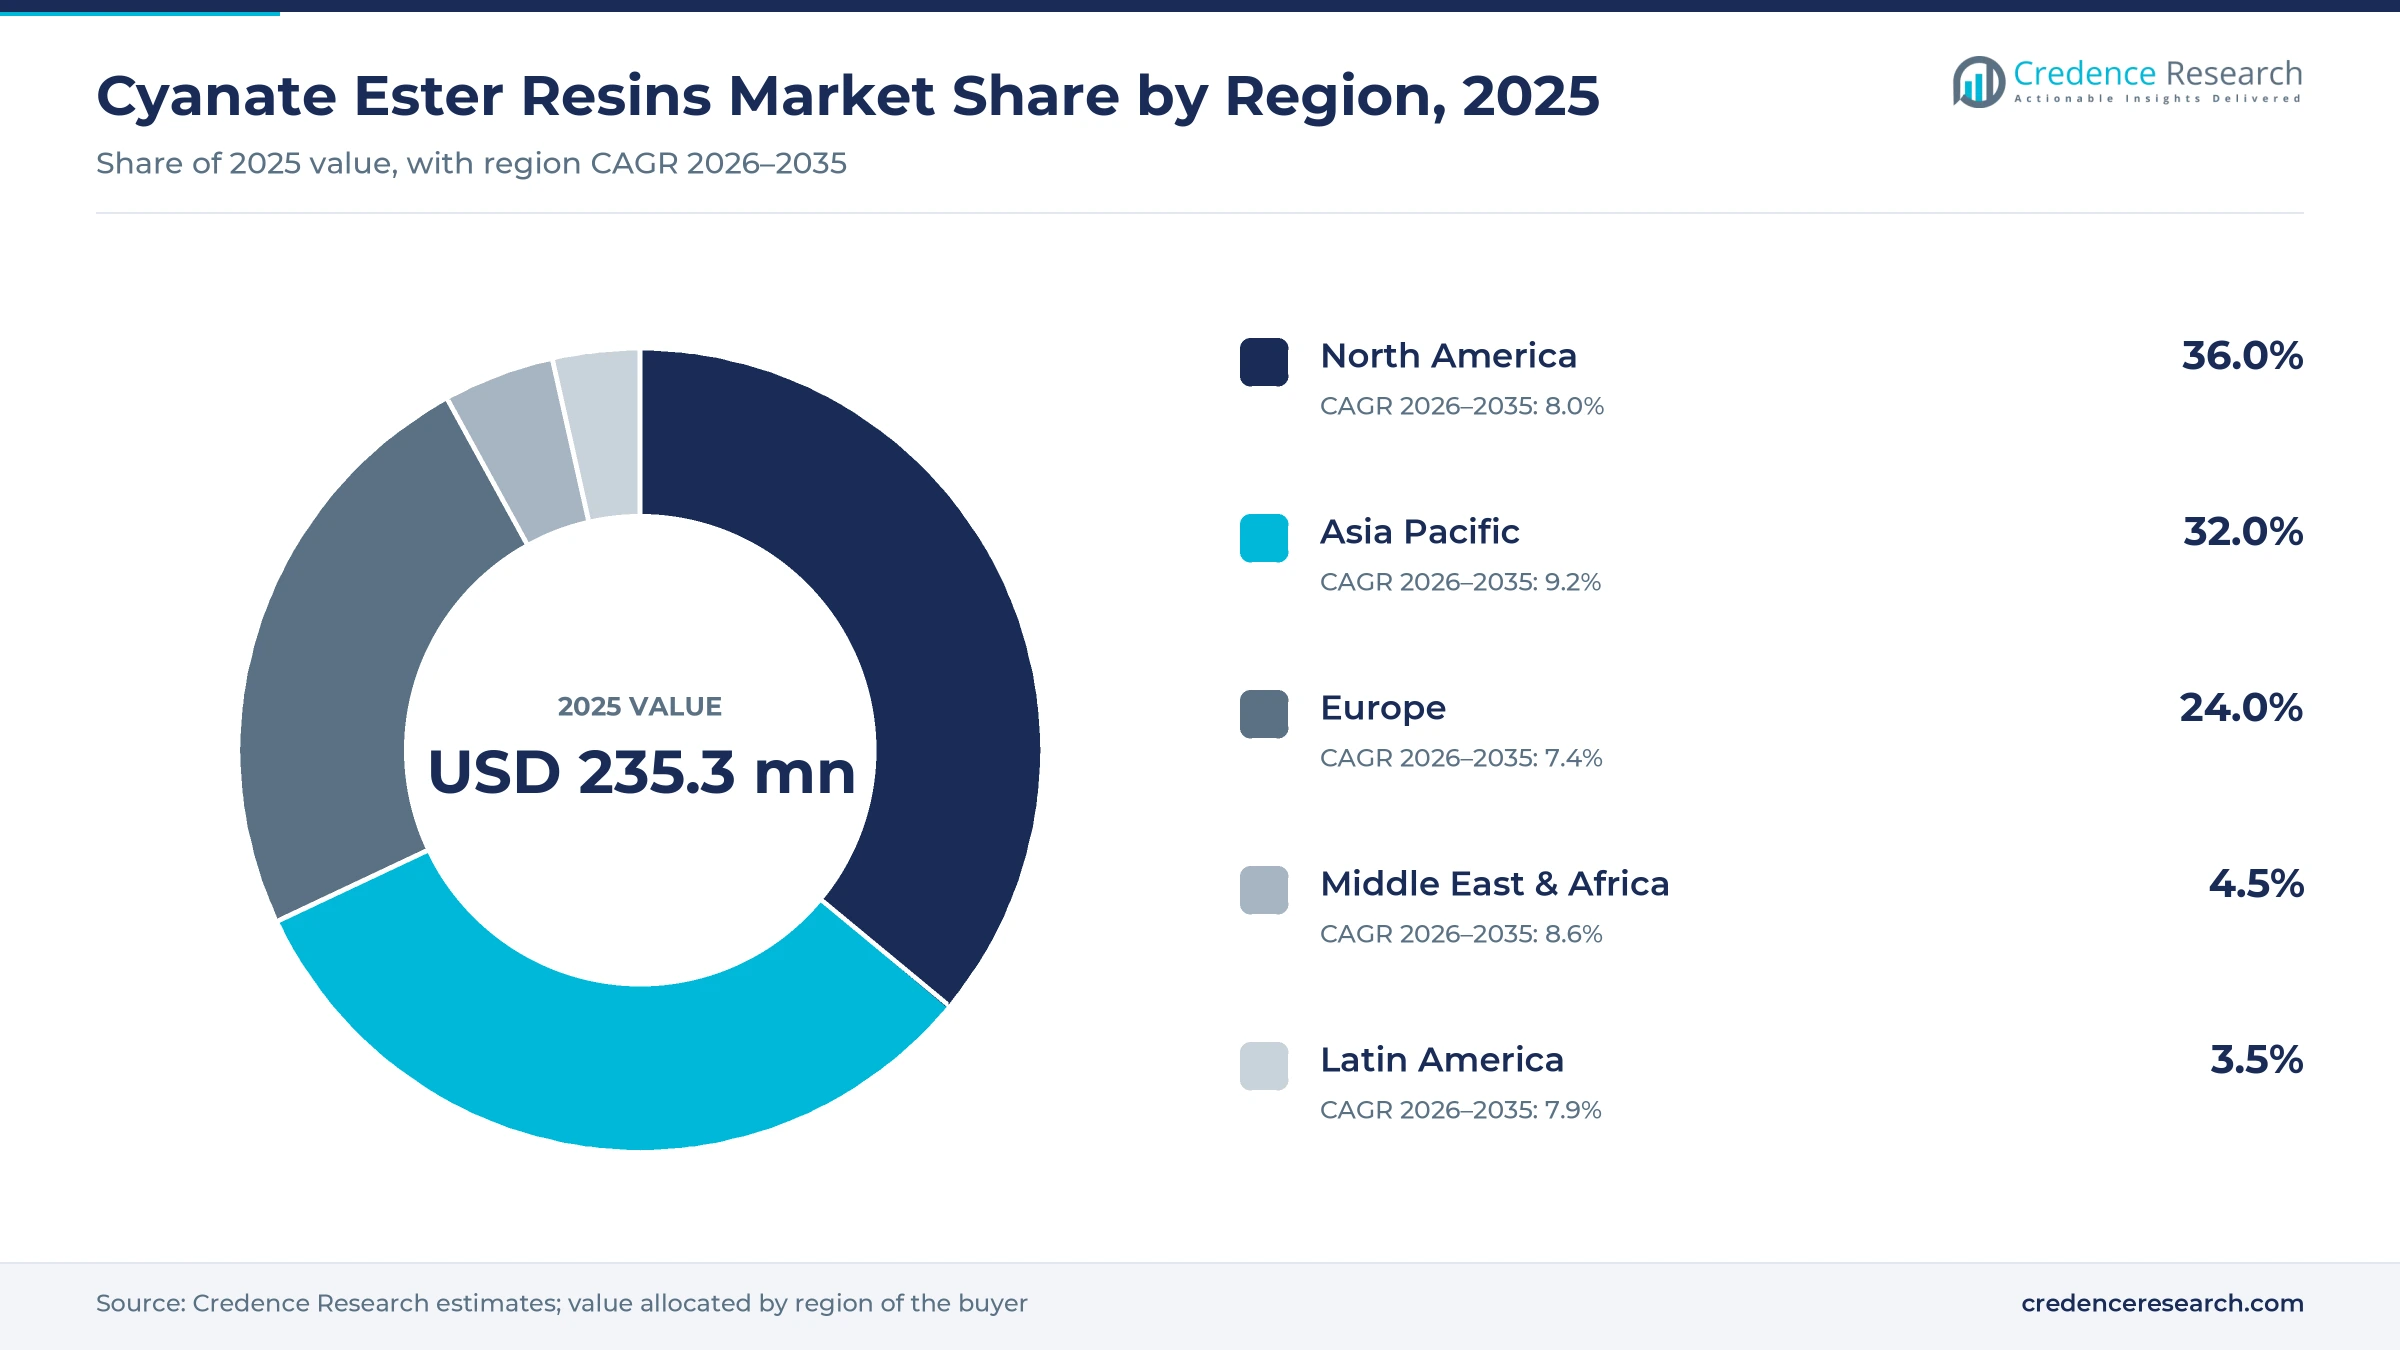
The global cyanate ester resins market was valued at USD 235.3 million in 2025 and is projected to increase from USD 254.9 million in 2026 to USD 522.4 million by 2035, registering a CAGR of 8.30% during 2026–2035. Demand comes from satellite and launcher structure makers, radome and antenna builders, missile programs and the laminate makers that supply semiconductor package substrates and high-frequency circuit boards. North America held the largest regional share, 36.0% in 2025, because U.S. constellation operators and defense space programs buy most qualified cyanate ester prepreg. Asia Pacific is the fastest-growing region at 9.2% a year, as Japanese and Thai capacity for BT packaging materials expands with AI server demand. Low moisture uptake, low outgassing in vacuum and a stable dielectric constant explain why buyers accept a resin that costs far more than epoxy. Cyanogen chloride, the toxic feedstock, keeps production in a few qualified plants and remains the main supply restraint.
Which resins and buyers does the estimate count?
The estimate counts cyanate ester monomers, prepolymers and formulated cyanate ester resin systems, valued at the point where the resin is sold to prepreg makers, laminate producers, adhesive formulators and part fabricators. Cyanate ester sold into bismaleimide-triazine blends for package substrates is counted at its resin value.
Prepreg, laminate and finished part value sits outside the estimate, as do epoxy, bismaleimide and polyimide resins that compete for the same hot or radio-frequency parts. Space and defense buyers purchase through program-specific qualifications that can run for years, while electronics buyers order on supply contracts tied to laminate output.
Cyanate Ester Resins Market Insights
- The market is valued at USD 235.3 million in 2025 and is projected to reach USD 522.4 million by 2035, growing at an 8.30% CAGR on satellite and chip package demand.
- North America led with 36.0% of 2025 value, because constellation operators and U.S. defense space programs buy most qualified cyanate ester prepreg.
- Aerospace & Defense held 47.0% of 2025 value, while Electrical & Electronics grows fastest at 9.0% a year on packaging substrate demand.
- A record 4,510 objects were launched into space in 2025, up from the previous high of 2,903 in 2023, according to U.N. data.
- Mitsubishi Gas Chemical completed a plant in Thailand in November 2025 that doubles the site's output of BT materials for semiconductor packages.
Solid dicyanates lead while liquid grades grow fastest
Why do solid dicyanates lead while liquid grades grow fastest?
Based on resin type, the market is categorized into bisphenol A cyanates, bisphenol E cyanates, novolac cyanates and others, which include bisphenol M grades and blended systems. Bisphenol A Cyanates led with 44.0% of 2025 value because the solid dicyanate is the cheapest route to a 250 C class network, and Zhejiang Kinglyuan, a Chinese manufacturer, lists a bisphenol A cyanate monomer for circuit boards and radar housings. Bisphenol E Cyanates grow fastest at 9.4% a year as fabricators move to liquid processing, and Huntsman lists its low-viscosity AroCy L-10 for filament winding, resin transfer molding and pultrusion.
Why do composites lead while adhesives grow fastest?
Based on application, the market is categorized into composites, adhesives, coatings and others, mainly moldings and encapsulants. Composites led with 60.0% of 2025 value because prepregs for satellite panels, radomes and launcher parts, plus glass-reinforced laminate for package substrates, absorb most resin. Hexcel's HexPly 954-3 cyanate matrix shows the space case, with a total mass loss of 0.20% in ASTM E595 outgassing tests. Adhesives grow fastest at 8.9% a year as chip adhesives gain use, and Huntsman lists AroCy grades for electronic chip adhesives and encapsulants.
Why does aerospace and defense lead while electronics grows fastest?
Based on end-use industry, the market is categorized into aerospace and defense, electrical and electronics, automotive and others such as sporting goods and wind energy. Aerospace & Defense led with 47.0% of 2025 value because qualified prepregs and adhesives sell at high prices per kilogram, and Toray calls its RS-3 cyanate ester prepreg an industry standard for satellite structure. Electrical & Electronics grows fastest at 9.0% a year as package substrate demand rises, since Mitsubishi Gas Chemical announced in November 2026 a further Thai expansion citing demand from data centers, servers and FC-BGA substrates.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Resin Type | Bisphenol A Cyanates | 44.0% | Bisphenol E Cyanates | 9.4% |
| By Application | Composites | 60.0% | Adhesives | 8.9% |
| By End-use Industry | Aerospace & Defense | 47.0% | Electrical & Electronics | 9.0% |
Qualified grades sell far above commodity thermosets
Cyanate ester pricing depends far more on qualification status and lot size than on monomer cost. A laboratory reagent pack of bisphenol A dicyanate lists at several hundred Australian dollars for 10 grams, which shows how thin small-lot supply is. Industrial buyers pay per kilogram on multiyear supply agreements, and a resin qualified on a satellite or missile program rarely changes, which protects supplier margins. Suppliers do not publish contract prices, so the industrial ranges below are Credence Research estimates and carry wide error bands.
| Product or reference | Typical price or fee | Basis |
|---|---|---|
| 2,2-Bis(4-cyanatophenyl)propane reagent, 10 g | AUD 378 list price | TCI Australia listing, November 2026 |
| Industrial cyanate ester monomer or prepolymer, drum lots | About USD 60-150 per kg | Credence Research estimate from specialty thermoset pricing and monomer cost structure |
| Space-qualified cyanate ester carbon prepreg | About USD 200-600 per kg | Credence Research estimate from fiber grade, resin content and program volumes |
| Aerospace epoxy resin for comparison | About USD 15-40 per kg | Credence Research estimate from aerospace epoxy system pricing |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Constellations, missile tracking and AI chips lift volumes
Satellite constellations need low-outgassing structure resins
Satellite structures are the most valuable outlet for cyanate esters, because panels, antenna reflectors and optical benches must hold shape in vacuum and through thermal cycling. A record 4,510 objects were launched into space in 2025, up from the previous high of 2,903 in 2023, according to U.N. data reported by Yale Environment 360. SpaceX reached 10,000 Starlink satellites simultaneously in orbit on March 17, 2026, Spaceflight Now reported. Toray describes its RS-3 cyanate ester prepreg as an industry standard for satellite structure, with a dry glass transition onset of 254 C. Prepreg suppliers already qualified on constellation buses gain most, because operators rarely requalify a material once production starts.
Missile-tracking satellites and radomes lift defense demand
Defense space programs add steady demand for cyanate ester prepreg and adhesives, since sensor satellites and radomes need stable dielectric and dimensional properties. The Space Development Agency awarded about USD 3.5 billion in December 2025 for 72 Tranche 3 tracking layer satellites, Spaceflight Now reported. Toray sells its BTCy-1 cyanate ester prepreg as an industry standard for satellite structures and radomes, with low moisture absorption and a low dielectric constant. Huntsman lists its bisphenol M based AroCy XU 378 for microwave antennas and radomes, which ties missile and satellite demand to makers of aircraft radomes. Suppliers with defense-qualified plants in the United States benefit from domestic sourcing rules.
AI chip packages pull cyanate chemistry into substrates
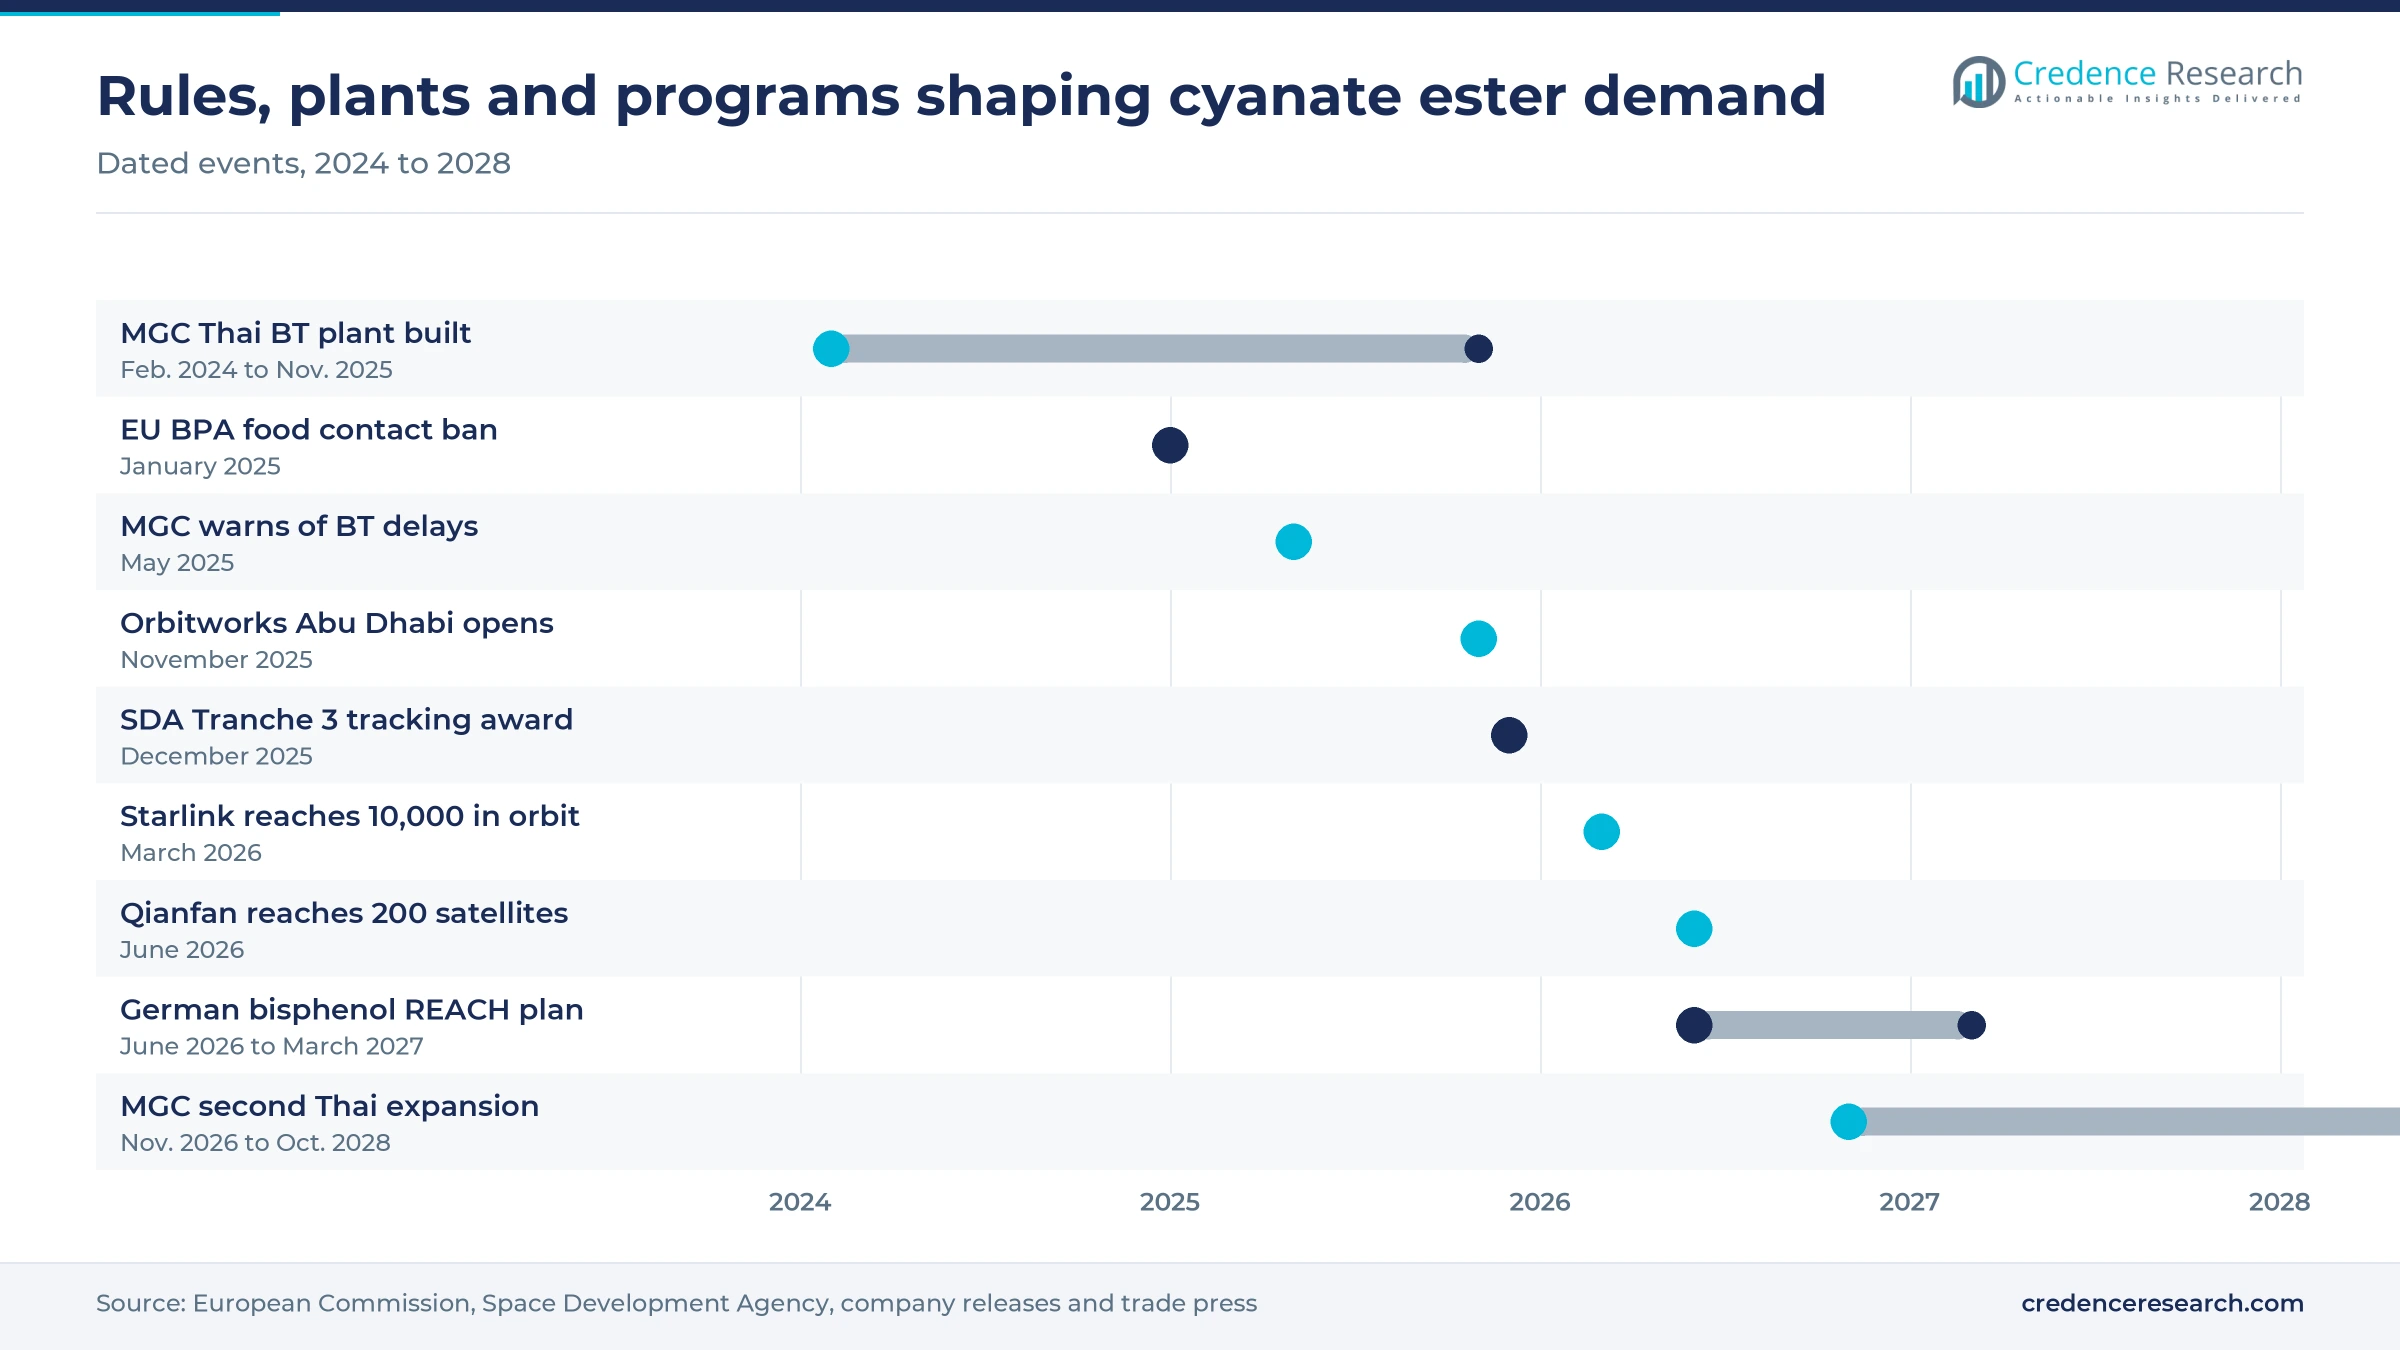
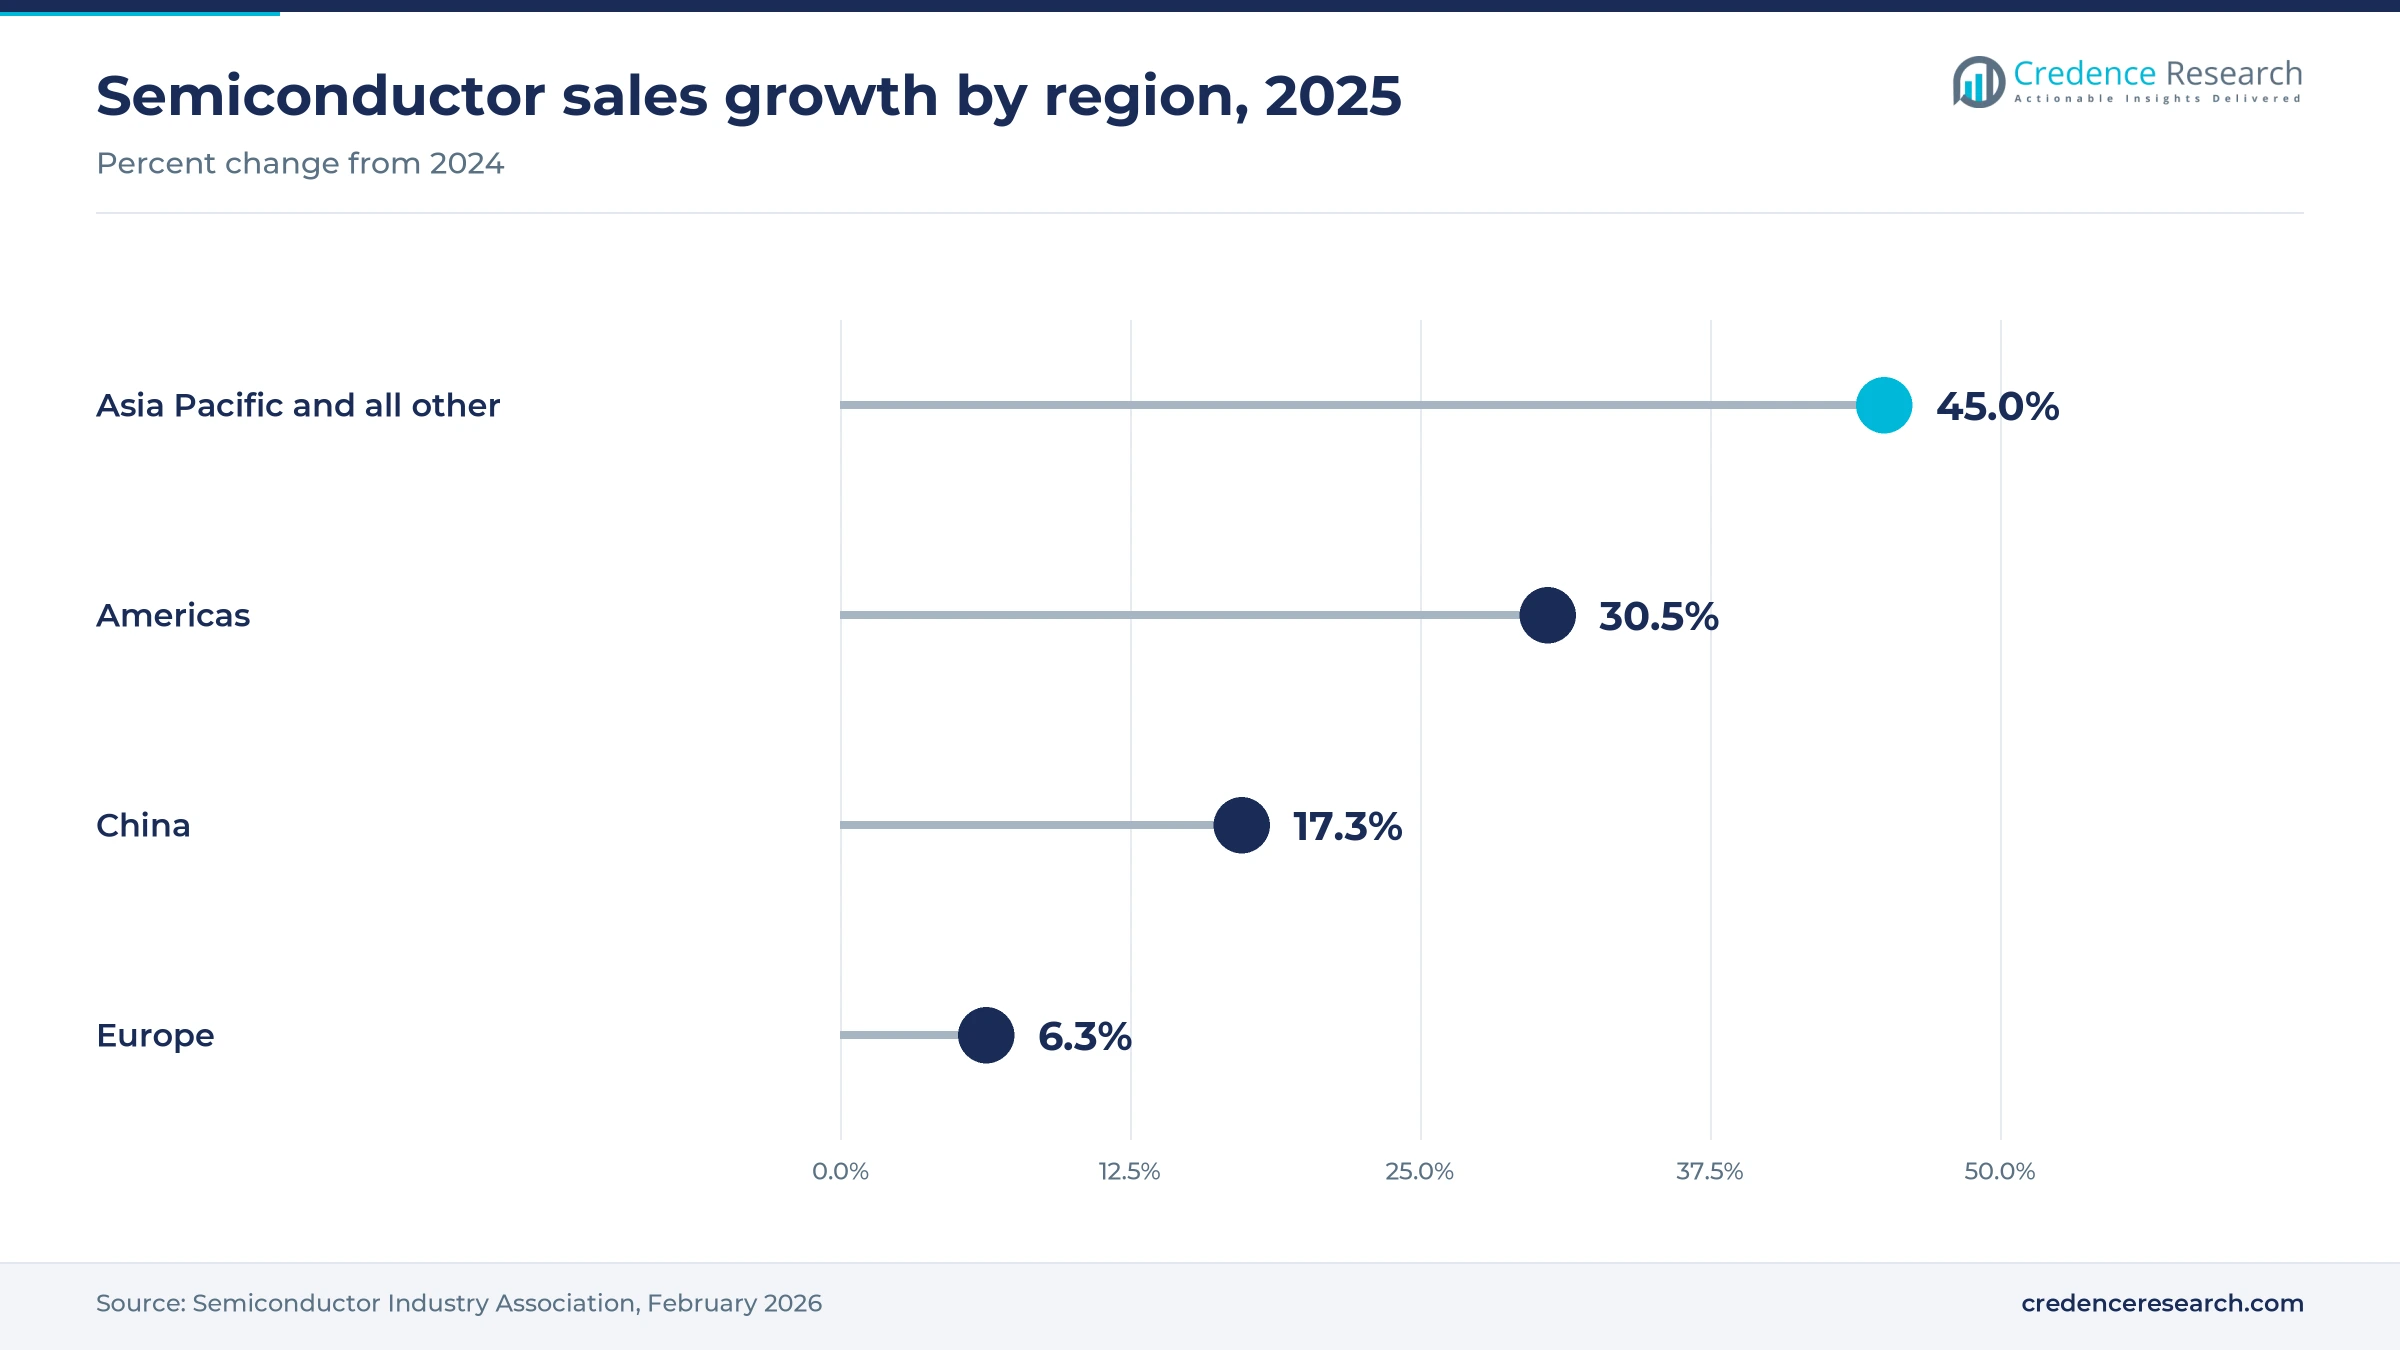
Semiconductor packaging is the largest volume outlet, because bismaleimide-triazine laminates built on cyanate ester chemistry hold dimensions at solder reflow temperatures. Global semiconductor sales rose 25.6% to USD 791.7 billion in 2025, the Semiconductor Industry Association reported. Mitsubishi Gas Chemical, the largest supplier of BT substrate raw materials according to Tom's Hardware, finished a new plant in Thailand in November 2025 that doubles the site's capacity for BT materials used in semiconductor packages. The company linked the investment to demand from AI, 5G, 6G and IoT devices. Resin demand in this segment follows laminate output, so suppliers integrated into laminates capture more of the value.
Higher aircraft build rates add radome and hot-zone parts
Commercial aircraft output supports demand for cyanate esters in radomes, antennas and parts near engines, although epoxy still makes up most airframe composite structure. Airbus delivered 793 commercial aircraft in 2025, Boeing delivered 600, its strongest year since 2018, and Embraer delivered 233 commercial and executive jets. Cyanate esters remain a small share of aerospace composites, so the build-rate effect is real but modest, and it favors suppliers already qualified on current narrowbody and business jet programs. Buyers of cyanate ester resins for radomes should expect longer lead times as these rates climb, because qualified prepreg lines are shared with space work.
Liquid grades, Asian dual bases and hot-zone parts
Fabricators shift toward liquid bisphenol E grades
Fabricators are shifting toward low-viscosity bisphenol E grades and out-of-autoclave prepregs to cut cycle time and reduce exposure to bisphenol A rules, creating openings across infusion and filament wound parts. An EU ban on bisphenol A in food contact materials entered into force on Jan. 20, 2025, with most transition periods ending on July 20, 2026, which does not cover composites but raises scrutiny of the chemistry. German authorities plan a REACH restriction on environmentally harmful bisphenols, with the proposal expected by March 12, 2027, Norway's environment agency reported in June 2026. Toray's RS-3C cures by vacuum bag and oven, while Huntsman positions AroCy L-10 for resin transfer molding. Suppliers with liquid grades gain, while makers that rely on bisphenol A feedstock need to track the German proposal.
Electronics suppliers shift toward dual-base Asian supply
Electronics material suppliers are shifting toward dual production bases in Asia to protect customers from single-site outages, creating openings for resin makers able to supply both sites. Mitsubishi Gas Chemical described its Japan and Thailand structure as a business continuity measure for BT materials. In November 2026 the company announced a further Thai expansion with new prepreg equipment, construction from April 2027 and operations from October 2028, Indian Chemical News reported. Chinese chemical maker Zhejiang Kinglyuan lists a dicyclopentadiene cyanate ester for circuit board materials, which points to local substitution in copper-clad laminates for Chinese board shops.
High-temperature parts open room beyond bismaleimide
Parts that operate between 250 C and 300 C offer an opening for cyanate esters, because bismaleimide loses mass at those temperatures and polyimides are hard to process. Arxada presented Primaset HTM-100 at CAMX 2024 with a glass transition up to 306 C, and the company reports far lower mass loss than bismaleimide in long heat aging. Phthalonitrile resins compete at the top of the range, and Cambium said its ApexShield 1000 phthalonitrile system sharply reduces the infiltration cycles needed for carbon-carbon parts. Engine nacelle, missile and tooling makers can therefore weigh two alternatives to bismaleimide and polyimide for hot parts.
Gulf and Chinese satellite plants open new buyer groups
New satellite factories outside the United States and Europe create buyer groups that have not yet locked in material qualifications. Orbitworks opened a facility in Abu Dhabi in November 2025 that can build up to 50 satellites a year, The National reported. China's Qianfan constellation reached 200 satellites in orbit in June 2026, and Qianfan and Guowang together aim for more than 10,000 satellites. Makers of small satellites in these programs need low-outgassing prepreg and adhesive for buses and antennas, so suppliers that qualify early, or license local prepreg partners, can win long supply positions before local material qualifications harden.
Toxic feedstock rules and long cure cycles limit entry
Cyanogen chloride rules keep production in a few plants
Cyanate ester production starts from cyanogen chloride, a toxic gas that sets high safety and permit costs. The Chemical Weapons Convention lists cyanogen chloride as a Schedule 3 toxic chemical, so plants above set thresholds must declare production and accept inspections. New entrants face long permitting and capital outlays, which concentrates monomer supply in a small number of permitted plants and leaves buyers exposed to single-plant outages.
Glass cloth and laminate shortages delay electronics orders
Electronics demand depends on glass cloth and laminate capacity as much as on resin supply. In May 2025 Mitsubishi Gas Chemical told customers that BT material shipments would face heavy delays because of shortages of low-expansion glass cloth, copper-clad laminate and prepreg, Tom's Hardware reported. Makers of NAND controllers and memory packages were most exposed, because suppliers gave priority to AI accelerator substrates. Resin volumes can stall even when chip demand is strong.
High cure and post-cure temperatures raise part costs
Cyanate esters need hotter and longer cure cycles than most aerospace epoxies, which raises energy, tooling and autoclave costs. Hexcel lists a standard two-hour cure at 177 C for HexPly 954-3, and a post-cure at 232 C lifts its glass transition from 206 C to 258 C. Small fabricators without high-temperature ovens or tools are most exposed, and many choose epoxy for parts that do not need vacuum stability or dielectric performance.
Widebody production weakness limits commercial volume
Commercial aerospace demand for high-performance resins softened on widebody programs in 2025. Airbus delivered only 36 A330 and 57 A350 widebodies in 2025, against 607 A320 family jets, according to its delivery release. Resin suppliers tied to widebody radome and interior parts are most exposed, since narrowbody growth adds fewer cyanate ester parts per aircraft. A recovery depends on airframers raising widebody production rates as they have planned.
North America leads as Asia Pacific grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 84.7 | 36.0% | 8.0% |
| Asia Pacific | 75.3 | 32.0% | 9.2% |
| Europe | 56.5 | 24.0% | 7.4% |
| Middle East & Africa | 10.6 | 4.5% | 8.6% |
| Latin America | 8.2 | 3.5% | 7.9% |
North America leads on constellation and defense buying
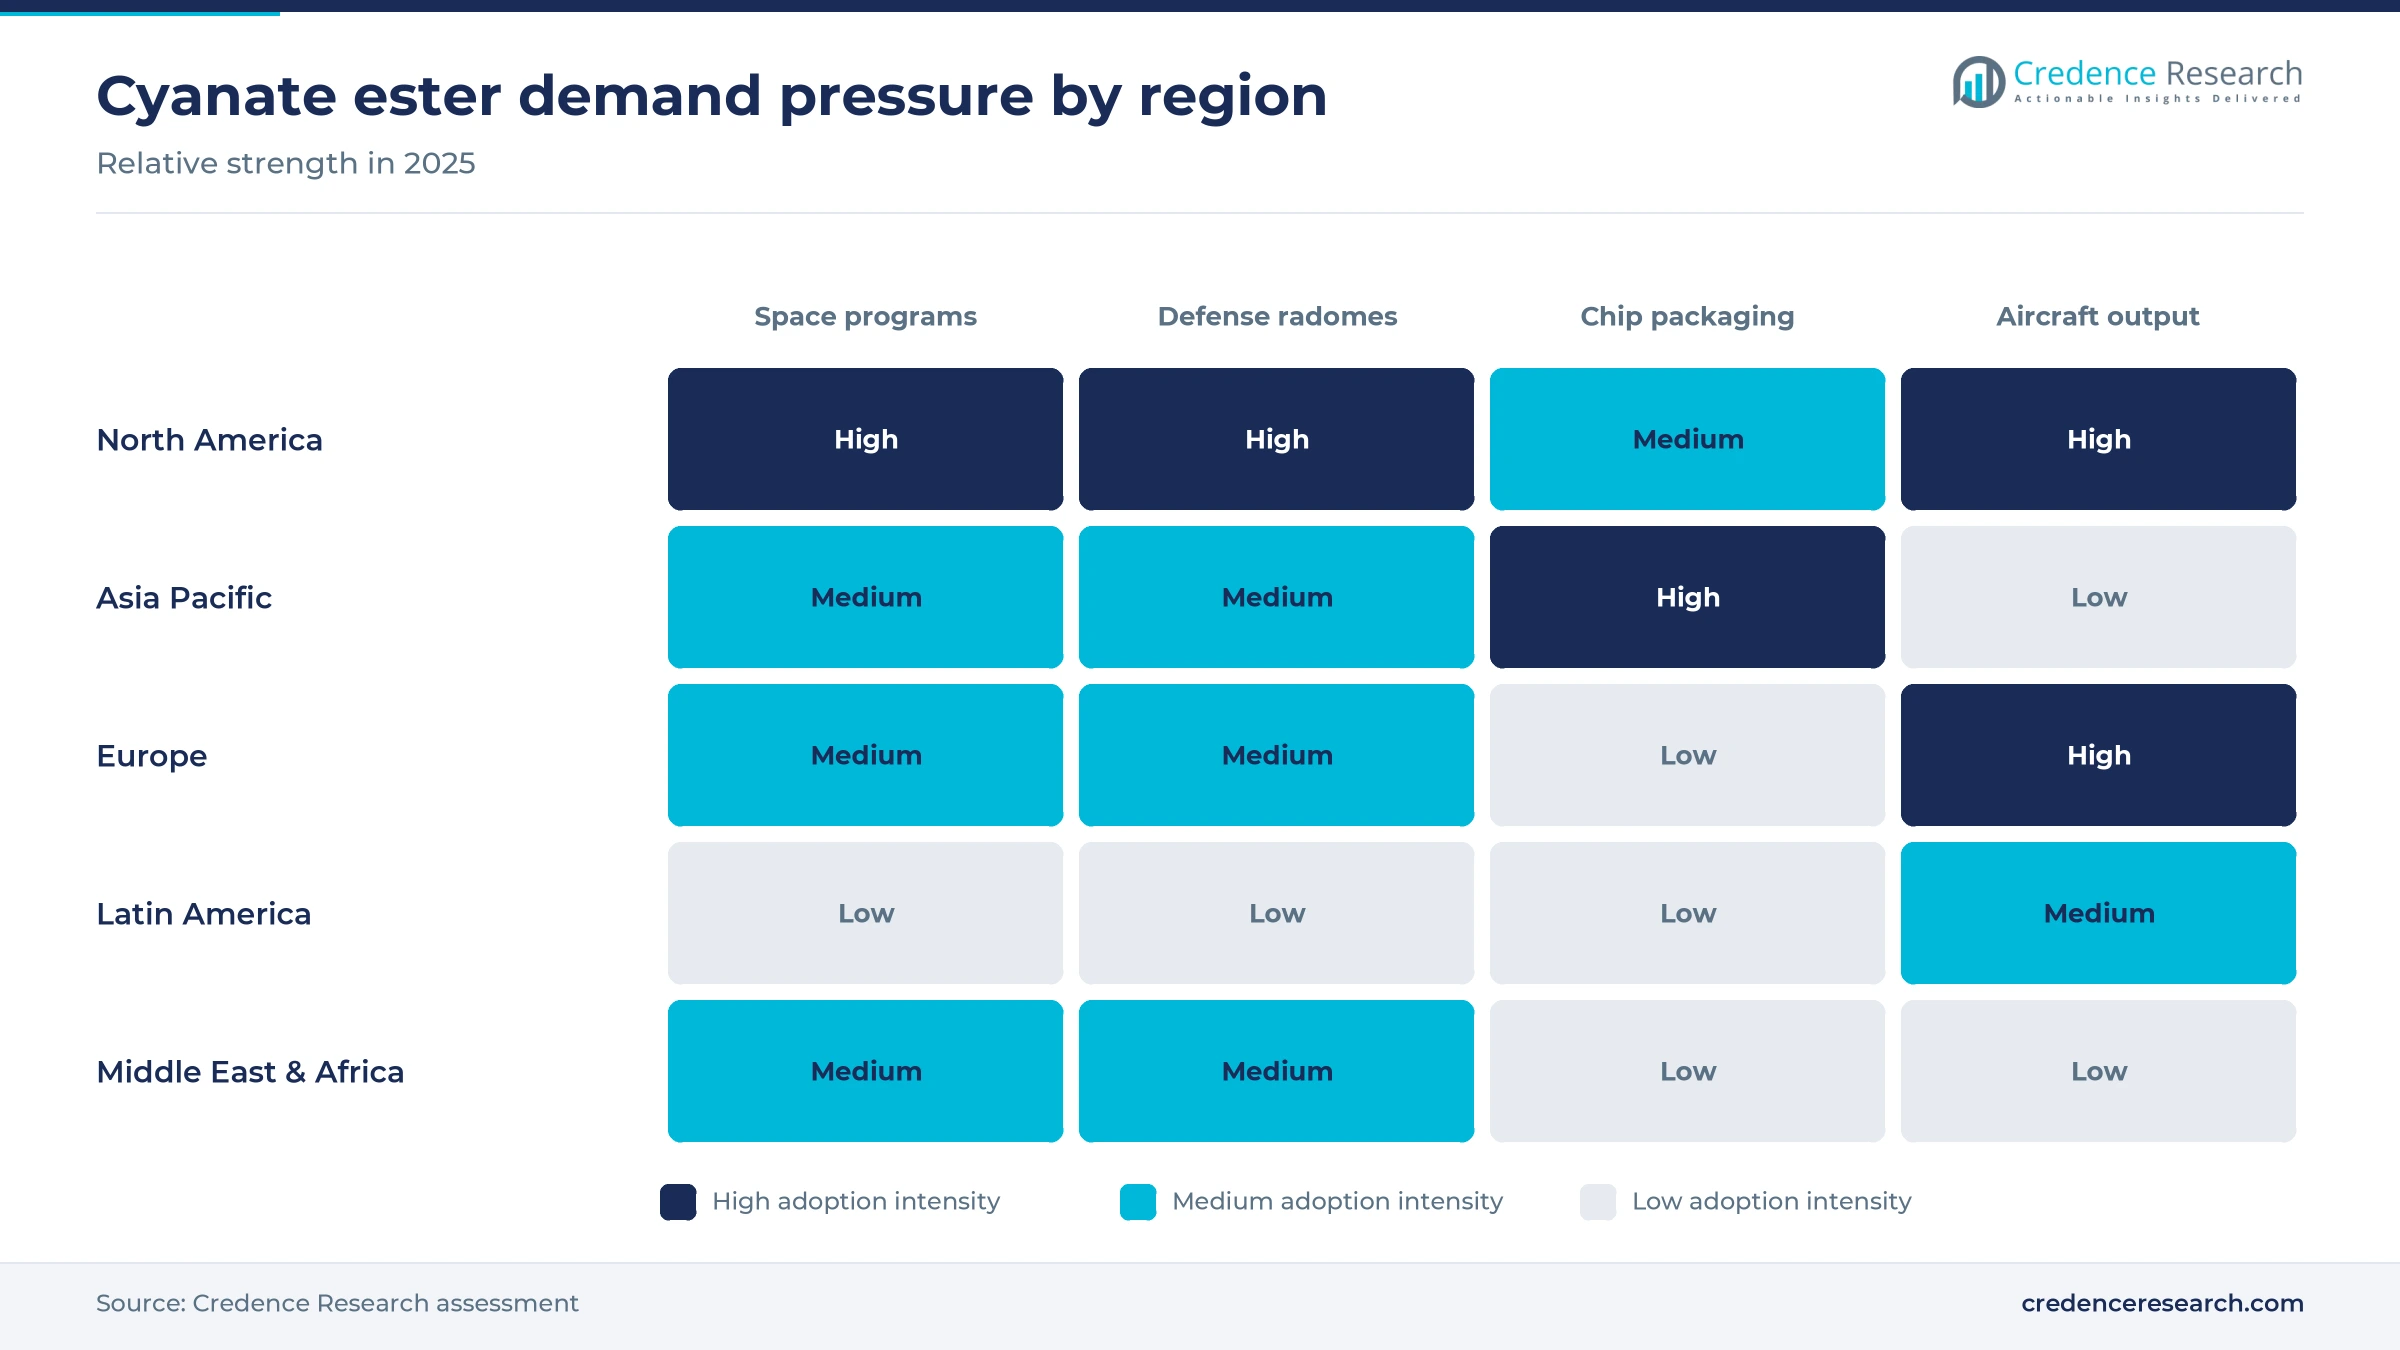
North America held 36.0% of 2025 value and grows at 8.0% a year, because U.S. constellation builders, the Space Development Agency and missile programs account for most purchases of space-qualified prepreg. The tracking layer award described above keeps defense demand visible to the end of the decade. Semiconductor sales in the Americas rose 30.5% in 2025, according to the industry association data noted earlier, which supports high-frequency board demand. Toray Advanced Composites has planned a 50% capacity expansion at its Morgan Hill, California, campus, according to CompositesWorld.
Asia Pacific grows fastest on packaging substrates
Asia Pacific held 32.0% of 2025 value and grows fastest at 9.2% a year, because package substrate and laminate makers in Japan, Taiwan, South Korea, Thailand and China buy most electronics-grade cyanate chemistry. Semiconductor sales in the Asia Pacific and all other group rose 45.0% in 2025, while China grew 17.3% and Japan fell 4.7%. Mitsubishi Gas Chemical's Thai capacity anchors supply, and Chinese constellation programs add space demand.
Europe relies on aircraft output and Swiss resin supply
Europe held 24.0% of 2025 value and grows at 7.4% a year, the slowest rate, because demand rests on aircraft and space programs while electronics output is small. Airbus's 2025 delivery total noted above, spread across 91 customers, supports radome and antenna work in the region. Swiss supplier Arxada presented its cyanate ester-based Primaset HTM-100 at CAMX 2024 with a glass transition of up to 306 C, CompositesWorld reported. European semiconductor sales rose only 6.3% in 2025, which limits laminate demand.
Latin America depends on Brazilian aircraft programs
Latin America held 3.5% of 2025 value and grows at 7.9% a year, because demand centers on Brazilian aircraft and defense programs rather than local resin production. Embraer delivered 78 commercial and 155 executive jets in 2025, up from 73 and 130 a year earlier, according to ch-aviation. No regional cyanate ester production was identified, so buyers import prepreg and resin, and this share carries a wide error range.
Middle East & Africa builds from new satellite plants
Middle East & Africa held 4.5% of 2025 value and grows at 8.6% a year, because Gulf states are adding satellite assembly and defense electronics capacity from a small base. The Orbitworks facility in Abu Dhabi noted above handles satellites of up to 500 kilograms. Public data on regional resin use are thin, so this estimate relies on program announcements rather than trade or consumption statistics.
Thai BT capacity and tracking satellites mark 2025-2026
| Development | Status and market relevance |
|---|---|
| In November 2025, MGC Electrotechno (Thailand), a Mitsubishi Gas Chemical subsidiary, completed a new plant in Rayong that doubles its capacity for BT materials used in semiconductor packages. | Completed construction; commercial operation was scheduled for December 2025, subject to confirmation, which adds packaging substrate resin demand in Asia. |
| In November 2025, Orbitworks, formed by Marlan Space and Loft Orbital, opened a satellite manufacturing facility in Abu Dhabi able to build up to 50 satellites a year. | Operational launch; the first of 10 Altair constellation satellites is expected in the second half of 2026, creating a new regional prepreg buyer. |
| In December 2025, the Space Development Agency awarded about USD 3.5 billion to Lockheed Martin, L3Harris, Rocket Lab and Northrop Grumman for 72 Tranche 3 tracking layer satellites. | Contract award; launches are slated from fiscal 2029, so material orders for structures and antennas follow over the next three years. |
| In June 2026, China's Qianfan constellation reached 200 satellites in orbit after two Long March launches on June 4 and June 5. | Deployment milestone; the constellation plan supports continued demand for space structure materials from Chinese suppliers. |
| In November 2026, Mitsubishi Gas Chemical announced a further expansion at its Thai subsidiary, adding prepreg equipment for copper-clad laminates and inspection capacity. | Plan; construction is scheduled from April 2027 and operations from October 2028, with demand tied to FC-BGA substrates for servers. |
Liquid monomers, triazine networks and oven-cure prepregs
- Liquid bisphenol E monomers flow at room temperature, which lets fabricators use infusion, filament winding and resin transfer molding instead of hot-melt prepreg.
- Novolac cyanate networks form dense triazine rings with glass transitions that can exceed 300 C, which suits hot structure, tooling and parts that replace metal.
- Bismaleimide-triazine blends combine cyanate ester with bismaleimide to give laminates the heat and dimensional stability that package substrates need during solder reflow.
- Oven-cure cyanate ester prepregs cure under vacuum bag without an autoclave, which lowers capital needs for satellite panel and radome makers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
A few monomer makers feed qualified prepreg suppliers
Competition turns on qualification history, outgassing and dielectric data, and secure feedstock rather than on price. Mitsubishi Gas Chemical leads electronics through BT materials made in Japan and Thailand. Huntsman sells the AroCy range of bisphenol E, bisphenol M and novolac cyanate esters, while Arxada, formerly part of Lonza Group, sells Primaset resins from Switzerland. Hexcel and Toray Advanced Composites are the best-known suppliers of space-qualified cyanate ester prepreg, and Park Aerospace sells RadarWave prepregs with a cyanate ester option for radomes. Chinese manufacturers such as Zhejiang Kinglyuan list bisphenol A and dicyclopentadiene cyanate monomers for circuit board materials. Buyers usually qualify one monomer source and one prepreg source per program, so switching suppliers takes years and favors incumbents with long flight heritage. The seven companies profiled below cover monomers, formulated resins and prepregs.
How is the supply side organized and where do margins sit?
Supply of cyanate ester resins runs in two distinct tiers. A small group of monomer and resin makers, led by Mitsubishi Gas Chemical, Huntsman and Arxada with several Chinese producers, makes the cyanate ester itself, because handling cyanogen chloride needs permitted plants. Prepreg and laminate makers such as Hexcel, Toray Advanced Composites and Park Aerospace turn the resin into qualified materials for space, defense and electronics buyers. Entry barriers sit in feedstock permits, outgassing and program qualifications, and customer approval cycles. Margins are highest on space-qualified prepreg and specialty grades, and lowest on bisphenol A resin sold into laminates.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Mitsubishi Gas Chemical Company, Inc. | Electronics resin leader | Makes cyanate ester and BT resin materials for semiconductor package substrates |
| Huntsman Corporation | Resin specialist | Sells AroCy bisphenol E, bisphenol M and novolac cyanate ester resins |
| Arxada AG | Resin specialist | Sells Primaset cyanate ester-based and other thermoset resins for composites and electronics |
| Hexcel Corporation | Prepreg supplier | Sells HexPly 954 cyanate matrix prepregs for space structures |
| Toray Industries, Inc. (Toray Advanced Composites) | Prepreg supplier | Sells RS-3 cyanate ester prepregs for satellites, radomes and missiles |
| Park Aerospace Corp. | Prepreg specialist | Sells RadarWave radome prepregs with epoxy or cyanate ester matrix |
| Zhejiang Kinglyuan Pharmaceutical Co., Ltd. | Local manufacturer, China | Lists bisphenol A and dicyclopentadiene cyanate resins for boards and radar housings |
Qualification, not tonnage, decides supplier value
Credence Research's view is that supplier value in this market comes from qualification positions rather than tonnage. A resin written into a satellite bus, missile radome or substrate specification tends to stay for the life of the program, so the next five years of constellation and tracking satellite awards will set supplier shares well into the 2030s. Electronics will add most of the volume, but at lower prices and with laminate capacity as the gate. Buyers should secure second sources where cyanogen chloride supply depends on a single plant, and suppliers with liquid grades are best placed for out-of-autoclave work.
Earlier estimate rolled forward and tested on volumes
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested against an estimate of cyanate ester tonnage in space, defense and electronics uses multiplied by typical resin prices. Regional and segment shares are Credence Research estimates based on satellite and defense programs, aircraft deliveries, semiconductor sales and resin plant locations. Sources include U.N. and European Commission data, the Chemical Weapons Convention annex, company releases and trade press. No interviews or surveys were conducted for this update of the estimate.
Space and packaging demand carry growth to 2035
Growth to 2035 depends on how many satellites move from awards into production and on how fast package substrate capacity expands in Asia. The base case assumes constellation launches stay near 2025 levels, the Thai capacity ramps as planned and widebody output recovers slowly. Bisphenol E and other liquid grades should gain share as fabricators adopt oven cure and infusion. Feedstock permits will keep supply concentrated, so qualified suppliers should hold pricing power even as Chinese producers expand in electronics grades.
Space budgets and packaging capacity set the range of outcomes
The spread of outcomes depends mainly on how fast constellation and defense satellite programs move from awards to production, and on whether glass cloth and laminate capacity keeps pace with AI package demand. Electronics can add volume quickly, while space demand adds value per kilogram. A delay in tracking satellite production or a pause in server builds would lower growth, and new Gulf and Chinese satellite plants are the main upside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 6.5% | USD 449.2 million | Defense satellite schedules slip and AI server builds pause after 2027 |
| Base | 8.30% | USD 522.4 million | Constellation launches hold near 2025 levels and Thai packaging capacity ramps as planned |
| Upside | 9.5% | USD 576.8 million | Gulf and Chinese satellite plants qualify cyanate ester prepreg and widebody rates recover |
Frequently Asked Questions
How big is the cyanate ester resin market?
Which end-use industry holds the largest share?
Which region leads the cyanate ester resins market?
Who are the main cyanate ester resin suppliers?
Why are cyanate ester thermosets used in satellites?
How do phthalonitrile resins compare with cyanate esters?
What restrains the cyanate ester resins market?
How fast does the bisphenol E segment grow?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Resin Type
- 1.2.1 Bisphenol A Cyanates
- 1.2.2 Bisphenol E Cyanates
- 1.2.3 Novolac Cyanates
- 1.2.4 Others (Bisphenol M and Blends)
- 1.3 By Application
- 1.3.1 Composites
- 1.3.2 Adhesives
- 1.3.3 Coatings
- 1.3.4 Others (Moldings and Encapsulants)
- 1.4 By End-use Industry
- 1.4.1 Aerospace & Defense
- 1.4.2 Electrical & Electronics
- 1.4.3 Automotive
- 1.4.4 Others (Sporting Goods, Wind Energy)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 235.3 million → 2035: USD 522.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cyanate Ester Resins Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cyanate Ester Resins Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cyanate Ester Resins Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cyanate Ester Resins Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cyanate Ester Resins Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cyanate Ester Resins Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cyanate Ester Resins Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cyanate Ester Resins Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 235.3 million → 2035: USD 522.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cyanate Ester Resins Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Resin Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bisphenol A Cyanates
- 12.3.7.2 Bisphenol E Cyanates
- 12.3.7.3 Novolac Cyanates
- 12.3.7.4 Others (Bisphenol M and Blends)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Composites
- 12.4.7.2 Adhesives
- 12.4.7.3 Coatings
- 12.4.7.4 Others (Moldings and Encapsulants)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aerospace & Defense
- 12.5.7.2 Electrical & Electronics
- 12.5.7.3 Automotive
- 12.5.7.4 Others (Sporting Goods, Wind Energy)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cyanate Ester Resins End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cyanate Ester Resins Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cyanate Ester Resins Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cyanate Ester Resins Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mitsubishi Gas Chemical Company, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Huntsman Corporation
- 18.4 Arxada AG
- 18.5 Hexcel Corporation
- 18.6 Toray Industries, Inc. (Toray Advanced Composites)
- 18.7 Park Aerospace Corp.
- 18.8 Zhejiang Kinglyuan Pharmaceutical Co., Ltd.
- 18.9 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

