
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
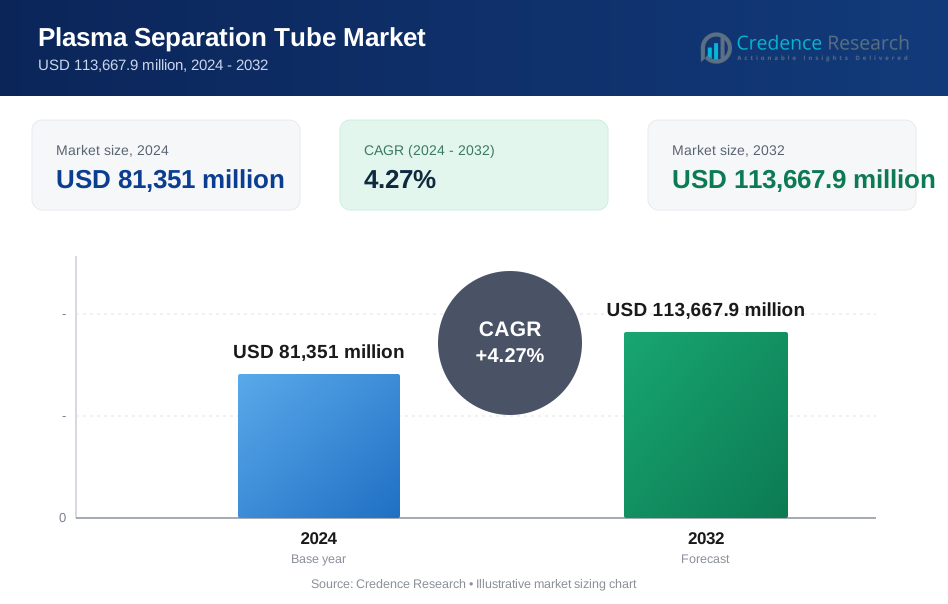
| Plasma Separation Tube Market Size 2024 | USD 81,351 million |
| Plasma Separation Tube Market, CAGR | 4.27% |
| Plasma Separation Tube Market Size 2032 | USD 113,667.9 million |
Market Overview
The polyurethane precursor market is projected to grow from USD 81,351 million in 2024 to USD 113,667.9 million by 2032, registering a compound annual growth rate (CAGR) of 4.27% during the forecast period.
The polyurethane precursor market is experiencing steady growth driven by rising demand across diverse end-use industries such as automotive, construction, electronics, and furniture. Increased emphasis on energy-efficient buildings is propelling the use of polyurethane-based insulation materials, while the automotive sector leverages its lightweight and durable properties to improve fuel efficiency. Growth in consumer electronics and appliances is also fueling demand for polyurethane foams and adhesives. Sustainability trends are influencing manufacturers to develop bio-based and low-emission precursors, aligning with regulatory pressure for environmentally friendly products. Technological advancements in production processes and innovations in formulation are enhancing product performance and expanding application scope. The market is further supported by urbanization, infrastructure development, and rising disposable incomes in emerging economies. Additionally, the growing popularity of smart homes and green construction is promoting the use of high-performance polyurethane materials. These factors collectively contribute to a positive market outlook, positioning polyurethane precursors as critical components in next-generation material solutions.
The polyurethane precursor market shows strong geographical diversity, with Asia Pacific leading at 46% market share, driven by rapid industrialization and infrastructure growth across China, India, and Southeast Asia. North America holds 24%, supported by technological innovation and high adoption in construction and automotive sectors. Europe accounts for 18%, emphasizing sustainability, strict regulations, and green building initiatives, particularly in Germany and France. The Rest of the World, comprising Latin America, the Middle East, and Africa, holds 12%, showing gradual expansion through industrial development. Key players in the market include BASF SE, Dow Chemical Company, Covestro AG, Huntsman Corporation, Wanhua Chemical Group, Shell Plc, Recticel NV/SA, Perstorp AB, Arkema SA, Arcad Chemicals, Lubrizol Corp., and Evonik Industries. These companies compete through innovation, sustainability initiatives, and strategic partnerships to enhance their global footprint and meet evolving industry requirements.
Market Insights
- The polyurethane precursor market is projected to grow from USD 81,351 million in 2024 to USD 113,667.9 million by 2032, at a CAGR of 4.27%, driven by broad industrial demand.
- Strong growth in construction and insulation applications, especially in developing economies, is boosting demand for polyurethane-based high-performance materials.
- Lightweight and durable polyurethane components support rising automotive production and electric vehicle adoption, enhancing energy efficiency and comfort.
- Technological innovation and bio-based material development are expanding application scope and improving compliance with environmental regulations.
- Regulatory pressure on VOC emissions and isocyanate use challenges producers to reformulate products, increasing R&D and compliance costs.
- Asia Pacific leads the market with 46% share, followed by North America at 24%, Europe at 18%, and Rest of the World at 12%, reflecting strong global demand.
- Key players such as BASF SE, Covestro AG, Dow, Huntsman Corporation, and Wanhua Chemical compete through innovation, strategic partnerships, and sustainability-focused solutions
Market Drivers
Rising Demand from the Construction and Insulation Industry
The polyurethane precursor market benefits significantly from the global focus on energy efficiency and sustainable construction. Governments are enforcing strict building codes that promote the use of high-performance insulation materials, and polyurethane-based systems meet these needs effectively. It delivers superior thermal insulation, moisture resistance, and structural strength. Builders and architects prefer polyurethane solutions in residential and commercial projects. The construction boom in developing economies adds further momentum. This trend consistently drives market expansion.
- For instance, Covestro’s polyurethane (PUR) and polyisocyanurate (PIR) foams have been demonstrated to provide 30–50% better thermal performance compared to conventional materials such as glass or stone wool, supporting compliance with new energy codes in buildings.
Automotive Sector Push for Lightweight and Durable Materials
The automotive industry is a key growth driver for the polyurethane precursor market. Automakers aim to reduce vehicle weight to improve fuel efficiency and meet emission standards. It supports this shift by offering lightweight, durable components for seats, interior panels, and suspension bushings. Vehicle manufacturers rely on polyurethane’s vibration resistance and comfort-enhancing features. Increased vehicle production and demand for electric vehicles sustain momentum. The industry's evolving priorities strengthen long-term market demand.
- For instance, Ford has adopted aluminum-intensive bodies for the F-150, cutting the vehicle’s weight by over 700 pounds to enhance fuel efficiency and reduce emissions.
Technological Advancements and Material Innovation
Material innovations and improvements in polyurethane chemistry continue to enhance performance, flexibility, and environmental safety. The polyurethane precursor market benefits from advancements that make formulations more adaptable to different temperatures, substrates, and applications. It helps industries meet specific performance and regulatory needs while maintaining cost-effectiveness. Research in bio-based alternatives also supports the sustainability transition. Companies investing in R&D gain competitive advantage. This wave of innovation accelerates product adoption across sectors.
Expansion of Consumer Goods and Appliance Markets
Rising disposable incomes and lifestyle shifts are boosting demand for consumer goods, furniture, and home appliances. The polyurethane precursor market finds ample opportunity in these segments due to its versatility and comfort-enhancing properties. It plays a key role in flexible foams, coatings, and adhesives used in everyday products. Manufacturers prioritize materials that improve durability and user experience. Demand from Asia-Pacific markets is especially robust. These dynamics sustain upward market growth.
Market Trends
Growing Preference for Bio-Based and Low-VOC Polyurethane Solutions
Sustainability goals and environmental regulations are shaping product development in the polyurethane precursor market. Manufacturers are shifting toward bio-based raw materials to reduce reliance on fossil fuels and lower carbon emissions. It aligns with rising consumer demand for eco-friendly materials in packaging, construction, and furniture. Low-VOC formulations are gaining traction due to indoor air quality concerns. Regulatory bodies continue to favor products that minimize environmental impact. This trend is prompting innovation across the value chain.
- For instance, BASF offers non-toxic, low-emission polyurethane solutions for automotive interiors that significantly lower VOC and odor emissions, enhancing air quality inside vehicles while maintaining high performance and durability.
Rising Integration in Electric Vehicles and Battery Components
The growing adoption of electric vehicles is creating new demand patterns in the polyurethane precursor market. It supports EV manufacturing through thermal insulation, structural adhesives, and lightweight interior components. Polyurethane-based materials help enhance energy efficiency and improve safety in battery enclosures. The shift toward EV platforms increases the need for thermally stable and flame-retardant solutions. OEMs are optimizing materials to support vehicle range and performance. These evolving technical needs are driving segment-specific innovations.
- For instance, Covestro’s Desmodur® and Desmophen® polyurethane-based thermal interface materials (TIMs) are used in battery housings to enhance heat transfer from cells to cooling devices, supporting faster charging and reducing fire risk by isolating overheated cells.
Increased Application of Rigid Foams in Cold Chain and Refrigeration
Rising demand for efficient cold chain logistics and refrigeration systems is strengthening the use of rigid polyurethane foams. The polyurethane precursor market benefits from its excellent insulation properties, which help reduce energy consumption. It plays a critical role in commercial refrigeration, HVAC systems, and refrigerated transport. Retail and pharmaceutical sectors rely on stable temperature control. Expanding food delivery services and vaccine storage needs intensify this demand. The trend supports steady long-term market growth.
Advanced Manufacturing Techniques Enhancing Product Performance
Modern production methods such as precision dosing, digital formulation control, and automation are transforming polyurethane precursor manufacturing. The polyurethane precursor market is evolving toward higher consistency and customizability. It allows producers to optimize formulations for specific uses like footwear, automotive trims, or medical equipment. These techniques reduce material waste, lower costs, and improve quality control. Manufacturers are investing in equipment upgrades to meet growing quality standards. The shift is reinforcing reliability and scale in production.
Market Challenges Analysis
Stringent Environmental Regulations and Health Concerns
Tightening global regulations on volatile organic compounds (VOCs) and toxic isocyanates present a key challenge for the polyurethane precursor market. It faces increasing scrutiny due to potential health risks associated with chemical exposure during manufacturing and application. Regulatory compliance requires costly reformulation and the use of safer substitutes, which can raise production costs. Manufacturers must invest in safety measures and emissions control systems to meet legal requirements. This slows down adoption in certain regions. Shifting toward greener alternatives remains complex and resource-intensive.
Volatility in Raw Material Prices and Supply Chain Disruptions
Fluctuations in crude oil prices and supply chain uncertainties significantly affect the polyurethane precursor market. It relies on petrochemical derivatives like toluene diisocyanate (TDI) and methylene diphenyl diisocyanate (MDI), which are subject to price swings. Unpredictable logistics, trade restrictions, and geopolitical tensions further strain the availability of raw materials. This creates uncertainty in production planning and pricing strategies for manufacturers. Smaller players may struggle to maintain stable operations. Market growth is sensitive to global economic and supply dynamics.
Market Opportunities
Expansion of Green Building and Sustainable Construction Projects
The shift toward energy-efficient buildings and sustainable infrastructure presents strong opportunities for the polyurethane precursor market. It supports advanced insulation materials that meet green building standards such as LEED and BREEAM. Developers are adopting polyurethane-based products for superior thermal resistance, moisture control, and longevity. Rising urbanization and government incentives for eco-friendly construction are accelerating this trend. Demand is growing in both developed and emerging economies. This creates favorable conditions for market expansion.
Rising Penetration in Healthcare and Medical Device Applications
Growing use of polyurethane materials in medical devices and healthcare products creates new opportunities for the polyurethane precursor market. It enables soft, flexible, and biocompatible components used in wound dressings, surgical drapes, and medical foams. Increased healthcare investments and aging populations drive demand for safe and effective materials. Manufacturers can tailor polyurethane formulations to meet stringent regulatory and performance standards. The segment offers high margins and long-term stability. Innovation in medical-grade precursors strengthens this growth area.
Market Segmentation Analysis:
By Type
The polyurethane precursor market is segmented by type into foams, coatings, adhesives, elastomers, and sealants. Foams dominate the segment due to their wide use in insulation, cushioning, and structural applications. It finds strong demand in construction, furniture, and automotive sectors. Coatings and adhesives follow closely, supported by the need for durable, protective, and bonding materials in industrial and consumer goods. Elastomers and sealants contribute steadily, especially in automotive, footwear, and electronics applications, offering flexibility and wear resistance.
- For instance, BASF’s Elastopor® foam is specifically engineered for insulation in refrigerators and freezers, with technical data showing thermal conductivity as low as 0.022 W/m·K, making it a leading choice for energy-efficient appliances.
By Application
By application, the polyurethane precursor market is divided into flexible foam, rigid foam, thermoplastic polyurethane (TPU), and thermosetting polyurethane. Flexible foam holds the largest share due to its use in bedding, seating, and packaging. Rigid foam is growing rapidly, supported by demand for high-performance insulation in buildings and refrigeration systems. Thermoplastic polyurethane is gaining interest for its recyclability and versatility across electronics, automotive, and sportswear sectors. Thermosetting polyurethane continues to serve critical roles in structural and coating solutions where durability is essential.
- For instance, Tempur-Pedic, a leading mattress manufacturer, utilizes high-resilience polyurethane foam in its premium mattresses, which are designed to offer pressure relief and support for over 10 years of use.
Segments:
Based on Type:
- Foams
- Coatings
- Adhesives
- Elastomers
- Sealants
Based on Application
- Flexible Foam
- Rigid Foam
- Thermoplastic Polyurethane
- Thermosetting Polyurethane
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia Pacific
Asia Pacific holds the largest share of the polyurethane precursor market, accounting for 46% of the global revenue. Rapid urbanization, infrastructure growth, and rising automotive production drive strong demand across China, India, Japan, and Southeast Asia. It benefits from the expansion of residential and commercial construction, along with growing consumer markets for furniture, appliances, and footwear. The presence of key manufacturers and low production costs strengthen regional competitiveness. Governments are also supporting industrial growth through favorable policies. This region remains the primary growth engine for the market.
North America
North America captures 24% of the global polyurethane precursor market, driven by demand in construction, automotive, and industrial applications. The region prioritizes energy efficiency, which fuels adoption of polyurethane insulation materials in both residential and commercial sectors. It also supports innovation in sustainable and bio-based products to meet regulatory standards. The United States leads with strong R&D capabilities and established manufacturing infrastructure. Growth in electric vehicles further supports material innovation and market expansion. The region continues to show steady demand for high-performance applications.
Europe
Europe represents 18% of the global polyurethane precursor market and focuses heavily on sustainability and regulatory compliance. The region promotes low-emission and recyclable polyurethane materials across construction, automotive, and packaging sectors. It benefits from stringent energy regulations and investment in green buildings. Germany, France, and Italy lead demand through strong industrial bases and innovation ecosystems. The market aligns with circular economy goals and environmental standards. Manufacturers in the region emphasize quality, efficiency, and environmental performance.
Rest of the World
The Rest of the World accounts for 12% of the global polyurethane precursor market, with growing activity in Latin America, the Middle East, and Africa. It sees increasing demand from emerging economies investing in infrastructure, housing, and consumer goods. Economic development and industrialization support gradual market expansion. It remains an evolving landscape with untapped potential.
Key Player Analysis
- Arcad Chemicals
- Shell Plc
- Recticel NV/SA
- Huntsman Corporation
- Arkema SA
- BASF SE
- Lubrizol Corp.
- Covestro AG
- Wanhua Chemical Group Co., Ltd.
- Perstorp AB
- Evonik Industries
- Dow Chemical Company
Competitive Analysis
The polyurethane precursor market is characterized by intense competition among global chemical manufacturers focused on innovation, capacity expansion, and sustainability. Key players such as BASF SE, Dow Chemical Company, Covestro AG, and Huntsman Corporation lead the market with broad product portfolios and advanced R&D capabilities. It remains highly consolidated, with major firms investing in bio-based alternatives and low-emission formulations to align with regulatory trends. Companies like Wanhua Chemical Group and Shell Plc strengthen their global presence through strategic partnerships and localized production. Emerging players such as Arcad Chemicals and Perstorp AB contribute with specialized offerings and regional expertise. The market also sees active competition in pricing and customization to meet the diverse needs of automotive, construction, and consumer goods industries. Continuous innovation and responsiveness to sustainability demands shape competitive dynamics. Companies differentiate through performance, compliance, and technical support, keeping the competitive landscape dynamic and innovation-driven.
Recent Developments
- In March 2025, Evonik unveiled a new range of mass-balanced and bio-based additives—including TEGO® Foamex 812 eCO and TEGO® Wet 580 Terra—at the European Coatings Show, enhancing its portfolio of sustainable solutions for polyurethane-based coatings, adhesives, and inks.
- In April 2025, Covestro introduced Desmopan FLY, a high-performance thermoplastic polyurethane (TPU) series developed for supercritical fluid (SCF) injection molding, offering uniform foam structures and improved recyclability for applications like footwear, electronics, and furniture.
- In October 2024, Abu Dhabi National Oil Company (ADNOC) confirmed its acquisition of Covestro in a USD 16.3 billion deal, aiming to expand its global footprint in the polyurethane precursor market while accelerating Covestro’s growth in sustainable material technologies.
Market Concentration & Characteristics
The polyurethane precursor market demonstrates moderate to high market concentration, with a few dominant global players accounting for a significant share of total revenue. Companies such as BASF SE, Dow Chemical Company, Covestro AG, and Huntsman Corporation lead through vertical integration, broad product portfolios, and established global distribution networks. It is characterized by intensive R&D activity, strong focus on performance optimization, and increasing investment in bio-based and low-emission technologies. Market participants compete on innovation, cost-efficiency, regulatory compliance, and customization capabilities. The presence of both multinational corporations and specialized regional suppliers creates a dynamic yet consolidated competitive environment. Entry barriers remain high due to capital-intensive production, strict environmental regulations, and complex formulation requirements. Buyers in end-use industries prioritize long-term supplier relationships, technical support, and reliability, further reinforcing the hold of established companies. The polyurethane precursor market remains resilient to economic shifts due to its diversified applications across construction, automotive, electronics, and consumer goods.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for bio-based polyurethane precursors will continue to rise due to environmental regulations and sustainability goals.
- Construction and infrastructure growth in emerging economies will drive consistent demand for rigid and flexible foams.
- Electric vehicle adoption will increase the use of lightweight and durable polyurethane components in automotive applications.
- Advancements in manufacturing technologies will improve product consistency, efficiency, and application-specific customization.
- The market will see growing investment in low-VOC and non-toxic alternatives to meet health and safety standards.
- Consumer preference for energy-efficient and green buildings will support steady uptake of polyurethane insulation materials.
- The appliance and furniture industries will boost demand for high-comfort foams and coatings.
- Strategic partnerships and regional expansion will help key players strengthen their global market presence.
- Volatility in petrochemical prices may lead companies to diversify raw material sources and enhance supply chain resilience.
- Continued R&D will expand the scope of polyurethane applications across medical, electronics, and industrial sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Polyurethane precursor market?
What are the key segments within the Polyurethane precursor market
What are some challenges faced by the Polyurethane precursor market?
Who are the major players in the Polyurethane precursor market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Plasma Separation Tube Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Plasma Separation Tube Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 81,351 million → 2032: USD 113,667.9 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Plasma Separation Tube Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Plasma Separation Tube Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Plasma Separation Tube Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Plasma Separation Tube Market Drivers
- 3.3 Plasma Separation Tube Market Restraints & Challenges
- 3.4 Plasma Separation Tube Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Plasma Separation Tube Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Plasma Separation Tube Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Plasma Separation Tube category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Plasma Separation Tube Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Plasma Separation Tube Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Plasma Separation Tube market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Plasma Separation Tube Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Plasma Separation Tube Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Plasma Separation Tube Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Plasma Separation Tube (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Plasma Separation Tube Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Plasma Separation Tube Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Plasma Separation Tube Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Plasma Separation Tube Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Plasma Separation Tube Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Plasma Separation Tube Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Plasma Separation Tube Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Plasma Separation Tube Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Plasma Separation Tube Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
