
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
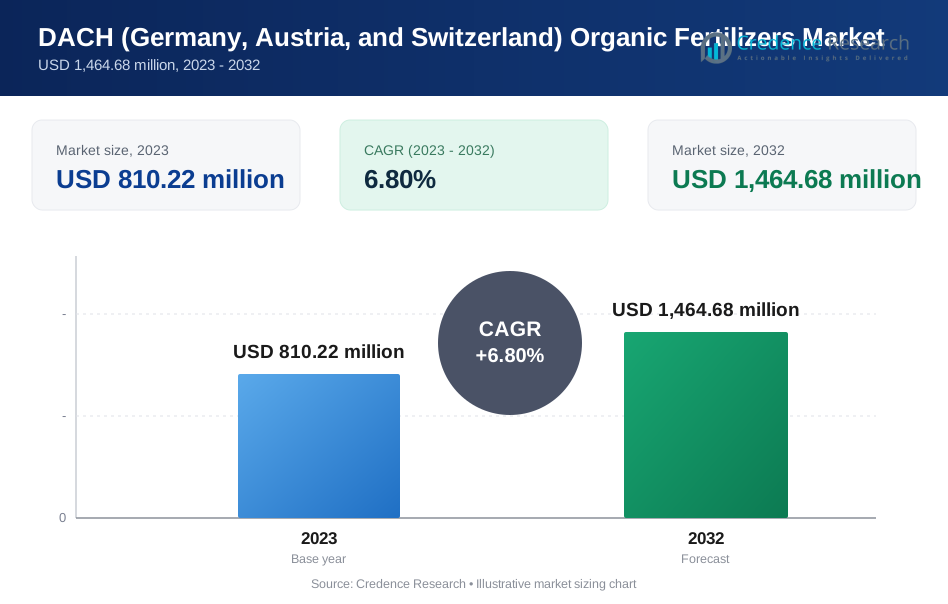
| DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Size 2023 | USD 810.22 million |
| DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market, CAGR | 6.80% |
| DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Size 2032 | USD 1,464.68 million |
Market Overview
The DACH region, encompassing Germany, Austria, and Switzerland, is witnessing significant growth in the organic fertilizers market, driven by a surge in organic farming practices and heightened environmental consciousness. The DACH Organic Fertilizers Market is projected to grow from USD 810.22 million in 2023 to an estimated USD 1,464.68 million by 2032, with a compound annual growth rate (CAGR) of 6.80% from 2024 to 2032. This robust growth trajectory highlights the increasing adoption of sustainable agricultural practices in the region, supported by favorable government policies and growing consumer preference for organic produce.
Market dynamics are strongly influenced by several key drivers and prevailing trends. Increasingly, stringent regulations regarding chemical fertilizers, coupled with governmental support for organic agriculture, are major drivers of the market. Additionally, there is a rising trend of using bio-based products, which not only improve soil fertility but also reduce environmental impact. This shift is further bolstered by the growing awareness among farmers and consumers about the benefits of organic products, which is steering the market toward more sustainable agricultural practices.
Geographically, Germany holds the largest share of the DACH Organic Fertilizers Market, attributed to its well-established agricultural sector and high consumer demand for organic food products. Austria and Switzerland also contribute significantly, with each country exhibiting increased investments in organic farming. Prominent players in the market include Biofert Manufaktur GmbH, DCM Group, and Fertikal N.V., who are expanding their presence through strategic alliances and product innovation. These companies focus on delivering high-quality, sustainable solutions to meet the evolving needs of the organic agriculture sector in the DACH region.
Market Drivers
Regulatory Support and Environmental Policies:
In the DACH region, stringent environmental regulations and policies strongly encourage the adoption of organic farming practices. For instance, Governments in these countries have implemented a variety of incentives and subsidies to promote sustainable agriculture, including financial support for farmers transitioning from conventional to organic farming. These policies are designed to reduce the environmental footprint of agricultural practices by limiting the use of chemical fertilizers and pesticides, thereby driving demand for organic fertilizers. The proactive stance of these governments in environmental conservation significantly propels the market forward.
Increasing Demand for Organic Produce:
There is a growing consumer preference for organic food products in the DACH region, driven by heightened awareness of health and environmental issues. For instance, consumers are increasingly informed about the benefits of organic foods, including their lack of chemical residues and their higher nutritional value compared to conventionally grown produce. This shift in consumer preferences has led to an expansion in the area under organic cultivation, thereby boosting the demand for organic fertilizers necessary to sustain these farming practices. Retailers and food service providers are also expanding their organic offerings, which further stimulates the market.
Technological Advancements in Organic Fertilizer Production:
Technological innovation plays a crucial role in the development of effective and efficient organic fertilizers. For instance, companies in the DACH region are investing in research and development to produce advanced organic fertilizers that offer enhanced soil fertility and are more cost-effective. These advancements include the development of customized nutrient mixes suited to specific soil types and crop needs, as well as improved methods for the stabilization and application of these fertilizers. Such innovations make organic fertilizers more appealing to farmers by increasing crop yields and simplifying application processes.
Expansion of Distribution Channels:
The availability of organic fertilizers has increased significantly due to the expansion of distribution channels. Manufacturers are partnering with agri-retailers, online platforms, and cooperatives to ensure wide accessibility and convenience for end users. This expansion not only helps in penetrating deeper into the market but also in educating farmers about the benefits of organic products. Enhanced distribution strategies are crucial in reaching small and mid-sized farms, which represent a significant portion of the agricultural landscape in the DACH region.
Market Trends
Rise of Bio-based and Plant-derived Products:
There is a noticeable shift towards bio-based and plant-derived fertilizers in the DACH region. For instance, these products are perceived as more sustainable and environmentally friendly compared to their synthetic counterparts. They are derived from natural sources such as plant residues, seaweed, and animal waste, which are rich in nutrients and beneficial for soil health.
Technological Integration in Fertilizer Application:
Technological advancements are increasingly being integrated into the application of organic fertilizers. For instance, precision agriculture techniques, including drone technology and IoT-based sensors, are used to assess soil health and optimize fertilizer application. This trend not only enhances the efficiency of fertilizer use but also minimizes waste and environmental impact.
Local Sourcing and Production:
There is a growing trend towards local sourcing and production of organic fertilizers, driven by the desire to reduce carbon footprints and support local economies. For instance, farmers and manufacturers are collaborating more closely to produce and utilize local organic waste as a primary resource for fertilizer production, promoting a circular economy within the agricultural sector.
Regenerative Agriculture Practices:
Regenerative agricultural practices that restore soil health and enhance biodiversity are gaining traction in the DACH region. For instance, these practices often incorporate the use of organic fertilizers as a key component to improve soil structure, increase water retention, and encourage beneficial microbial activity. This trend is closely aligned with broader environmental sustainability goals.
Customization and Specialty Products:
There is increasing demand for customized and specialty organic fertilizers tailored to specific crops and soil conditions. Manufacturers are responding by offering products that cater to niche markets, such as organic vineyards or specialty crop growers, providing them with solutions that meet unique agricultural requirements.
Educational Initiatives and Awareness Campaigns:
Manufacturers and agricultural bodies are investing in educational initiatives to raise awareness among farmers about the benefits of organic fertilizers. Workshops, seminars, and field demonstrations are common, aimed at promoting best practices and showcasing the efficacy of organic products.
Growing Institutional Support:
Institutional support for organic farming, including research funding and policy advocacy, is a key trend in the DACH region. Governments and non-governmental organizations are actively promoting organic farming through various initiatives, which in turn boosts the market for organic fertilizers.
Market Restraints and Challenges
Higher Product Costs:
One of the primary challenges in the organic fertilizers market is the higher cost of these products compared to conventional chemical fertilizers. Organic fertilizers are often more expensive due to the costs associated with the sourcing of natural materials and the processes involved in manufacturing. This price difference can deter farmers, especially small to medium-sized enterprises, from adopting organic products, impacting market penetration.
Limited Awareness and Technical Knowledge:
Although awareness about the benefits of organic fertilizers is growing, there remains a significant gap in comprehensive knowledge among some segments of the farming community. The lack of technical understanding about the application rates, timing, and methods suitable for organic fertilizers can hinder their effective use, thereby restraining market growth. Moreover, the results of using organic fertilizers are not immediately visible as they are with chemical alternatives, which can discourage continued use among new adopters.
Performance Variability:
The effectiveness of organic fertilizers can vary significantly depending on the source materials and production processes. Unlike synthetic fertilizers, which have standardized nutrient contents, organic fertilizers can have inconsistent nutrient levels. This variability can lead to unpredictability in performance, making it difficult for farmers to rely solely on these products for their nutrient management practices.
Regulatory and Certification Challenges:
The organic market is highly regulated, and obtaining certification for organic fertilizers can be a lengthy and costly process. The stringent standards required to meet organic certification can be a significant hurdle for new entrants and smaller producers. Additionally, the regulatory landscape can vary significantly between Germany, Austria, and Switzerland, complicating compliance and distribution efforts across the region.
Supply Chain and Logistical Issues:
Establishing a robust supply chain for organic fertilizers is challenging due to the perishability and bulkiness of these products. Efficient storage, handling, and transportation are critical to maintain product quality and effectiveness, which can add to operational costs and complexities. These logistical challenges can restrict the availability of organic fertilizers, especially in remote or less accessible farming areas.
Market Segmentation Analysis
By Source
Plant-based organic fertilizers, sourced from compost, crop residue, and other plant materials, are favored for their sustainability and minimal environmental impact, providing rich nutrients that enhance soil structure. Meanwhile, animal-based fertilizers, including products like manure and bone meal, are highly regarded for their robust content of essential nutrients such as nitrogen, phosphorus, and potassium. Additionally, mineral organic fertilizers, such as rock phosphate and green sand, play a crucial role in supplying specific minerals to the soil, thereby boosting crop yield and quality. Together, these diverse sources of organic fertilizers contribute to a holistic approach to agriculture in the DACH region, catering to various soil and crop needs.
By Crop Type
The DACH region's organic fertilizer market serves several key agricultural segments, each benefiting distinctly from the use of organic products. Cereals and grains, extensively cultivated across the area, rely on organic fertilizers to enhance soil fertility sustainably without depleting natural resources. Oilseeds and pulses benefit from fertilizers tailored to their specific nutrient needs, promoting healthier growth and improving nutritional content. In the fruits and vegetables segment, the quality and taste of produce are significantly influenced by the method of fertilization, with organic options appealing strongly to health-conscious consumers. Additionally, the market catizes to a variety of other crops, including ornamental plants and specialty crops, which require customized fertilization approaches to meet their unique growing conditions.
By Nutrition
Organic fertilizers with varying concentrations of organic substances cater to different soil health requirements. Fertilizers containing up to 60% organic substance are highly potent, ideal for soils lacking in organic matter, significantly enhancing soil health. Those with 40% to 60% organic substance offer balanced soil maintenance, providing a steady, optimal supply of organic matter without risking over-saturation. Meanwhile, fertilizers with 20% to 40% organic substance are perfect for regular maintenance, suited for well-managed soils that benefit from periodic nutrient replenishment, ensuring sustained soil vitality and crop health.
By Form
Dry organic fertilizers, available in forms like powders and granules, are favored for their ease of storage and transportation, making them ideal for farmers who need durable, slow-release nutrient solutions. Conversely, liquid organic fertilizers are sought after for their simplicity in application and rapid effectiveness, particularly excelling in fast nutrient absorption through leaves or roots. Together, these formats cater to diverse agricultural needs, offering flexibility in how nutrients are delivered to crops.
Segments
Based on Source
- Plant
- Animal
- Mineral
Based on Crop Type
- Cereals and Grains
- Oilseeds and Pulses
- Fruits and Vegetables
- Others
Based on Nutrition
- Presence of organic substance up to 60%
- Presence of organic substance from 40% to 60%
- Presence of organic substance from 20% to 40%
Based on Form
- Dry
- Liquid
Regional Analysis
Germany (55%):
Holding approximately 55% of the market share, Germany is the leader in the DACH Organic Fertilizers Market. The country's dominance is underpinned by a well-established organic farming sector and strong consumer demand for organic products. Germany has a robust regulatory framework supporting sustainable agricultural practices, which significantly encourages the use of organic fertilizers. The extensive network of organic farms and the widespread awareness among German farmers about the benefits of organic fertilizers further solidify its leading position in the market.
Austria (25%):
Austria accounts for about 25% of the market share. The country has experienced substantial growth in the use of organic fertilizers, driven by government initiatives promoting organic agriculture. Austria boasts a high rate of land under organic cultivation relative to its total agricultural area, one of the highest in Europe. This commitment to organic farming is a key factor propelling the demand for organic fertilizers. Austrian farmers are particularly keen on enhancing soil health and biodiversity, which aligns with the increasing adoption of environmentally friendly farming practices.
Key players
- Symborg SL
- Angibaud
- Novozymes A/S
- ILSA S.p.A.
- Italpollina S.P.A.
Competitive Analysis
In the competitive landscape of the DACH Organic Fertilizers Market, key players like Symborg SL, Angibaud, Novozymes A/S, ILSA S.p.A., and Italpollina S.P.A. are actively enhancing their market positions through innovation and strategic partnerships. These companies focus on developing high-efficiency, sustainable organic fertilizers that cater to the specific needs of diverse agricultural practices. For instance, Novozymes A/S leverages advanced biotechnological techniques to produce microorganism-based products that significantly boost crop yields while maintaining soil health. Similarly, Italpollina S.P.A. emphasizes the integration of scientific research and natural ingredients to offer environmentally friendly solutions. The competitive dynamics are further intensified by collaborations with local farms and research institutes, aiming to tailor products that are both effective and eco-conscious. These strategies not only strengthen their market presence but also contribute to the overall growth and sustainability of the organic fertilizers sector in the DACH region.
Recent Developments
In July 2023, Yara successfully launched its first water-soluble fertilizer facility in China, marking a significant step in its strategy to enhance sustainable agricultural practices in the region. This new facility is part of Yara China's broader initiative to provide tailored solutions that meet the specific needs of local crops, emphasizing Yara's commitment to sustainability and innovation. The establishment of this facility not only strengthens Yara's presence in the Chinese market but also supports the company's global strategy to advance environmentally friendly farming technologies.
In November 2023, K+S Aktiengesellschaft announced a partnership with Elixir Group to construct a new factory in Prahovo, eastern Serbia. This facility is designed to produce 50,000 tonnes of crystalline water-soluble fertilizer, specifically monoammonium phosphate (MAP), annually. The collaboration aims to leverage the expertise of both companies to enhance the supply of high-quality fertilizers in the region, thus supporting agricultural productivity and sustainability. This strategic move underscores K+S Aktiengesellschaft's commitment to expanding its manufacturing capabilities and its footprint in the global fertilizer market.
In June 2022, Fertoz acquired Excel Industries in a strategic move to bolster its offerings in the North American organic and regenerative agriculture sectors. This partnership is centered on the development of a specialized fertilizer pellet product, rich in essential nutrients such as NPK. With an investment of USD 1.28 million, Fertoz plans to establish a manufacturing plant capable of producing 80,000 tons of these nutrient-rich pellets annually. This initiative is a testament to Fertoz's commitment to innovation and its focus on supporting sustainable agricultural practices through tailored, nutrient-specific solutions.
On January 31, 2023, Sumitomo Chemical announced the acquisition of FBSciences Holdings, Inc., a prominent U.S.-based company specializing in biostimulants and naturally-derived agricultural materials. This strategic acquisition is set to expand Sumitomo Chemical's portfolio in the biostimulants market, furthering its commitment to sustainable agricultural solutions. By integrating FBSciences' innovative technologies and products, Sumitomo Chemical aims to enhance its global presence and provide farmers worldwide with eco-friendly and effective agricultural solutions. This move highlights Sumitomo Chemical's strategy to become a leader in sustainable agriculture, meeting the growing demand for environmentally conscious farming practices.
Market Concentration and Characteristics
The DACH Organic Fertilizers Market exhibits a moderate to high level of market concentration, with a handful of prominent players dominating the scene, reflecting significant consolidation, especially in sectors involving advanced technological inputs and large-scale production capabilities. These key players, including both large multinational corporations and strong local companies, drive innovation and set market trends through competitive strategies like mergers, acquisitions, and extensive R&D investments. The market is characterized by its focus on sustainability and compliance with stringent European Union regulations on organic farming. This regulatory environment influences product formulations and market entry strategies, ensuring that products meet high safety and environmental standards. Additionally, the market benefits from robust distribution networks that enhance product accessibility across Germany, Austria, and Switzerland, facilitating the steady growth of the organic fertilizers sector in the region.
Report Coverage
The research report offers an in-depth analysis based on Source, Crop Type, Nutrition and Form. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The DACH Organic Fertilizers Market is poised to benefit from the continued expansion of organic farming, driven by increasing consumer demand for organic products and supportive governmental policies.
- Advancements in fertilizer technology, including the development of targeted nutrient delivery systems, are expected to improve the efficacy and appeal of organic fertilizers.
- Stricter environmental regulations are anticipated to phase out harmful chemical fertilizers, pushing more farmers towards organic alternatives.
- New entrants are likely to join the market, encouraged by the growing demand and potential for innovation in organic fertilizer formulations.
- Increased consumer awareness about the environmental and health benefits of organic products will further drive market growth.
- Sustainability initiatives and circular economy principles are expected to influence the production and sourcing of raw materials, promoting the use of local and waste-derived inputs.
- Enhanced collaboration between agricultural researchers, governments, and industry players will facilitate the development of more efficient and sustainable organic fertilizers.
- As the quality and effectiveness of DACH-produced organic fertilizers gain recognition, export opportunities to other regions are likely to increase.
- The integration of digital tools in agriculture, such as precision farming technologies, will enhance the application efficiency of organic fertilizers, reducing waste and optimizing results.
- The rise of vertical farming and urban agriculture could open new markets for specialized organic fertilizers suited to these innovative farming methods.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the DACH Organic Fertilizers Market?
What are the key drivers of the DACH Organic Fertilizers Market?
Which country holds the largest market share in the DACH Organic Fertilizers Market?
What are the major challenges facing the DACH Organic Fertilizers Market?
How are technological advancements impacting the DACH Organic Fertilizers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 810.22 million → 2032: USD 1,464.68 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Drivers
- 3.3 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Restraints & Challenges
- 3.4 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, DACH (Germany, Austria, and Switzerland) Organic Fertilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. DACH (Germany, Austria, and Switzerland) Organic Fertilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the DACH (Germany, Austria, and Switzerland) Organic Fertilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 DACH (Germany, Austria, and Switzerland) Organic Fertilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in DACH (Germany, Austria, and Switzerland) Organic Fertilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New DACH (Germany, Austria, and Switzerland) Organic Fertilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa DACH (Germany, Austria, and Switzerland) Organic Fertilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. DACH (Germany, Austria, and Switzerland) Organic Fertilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
