
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
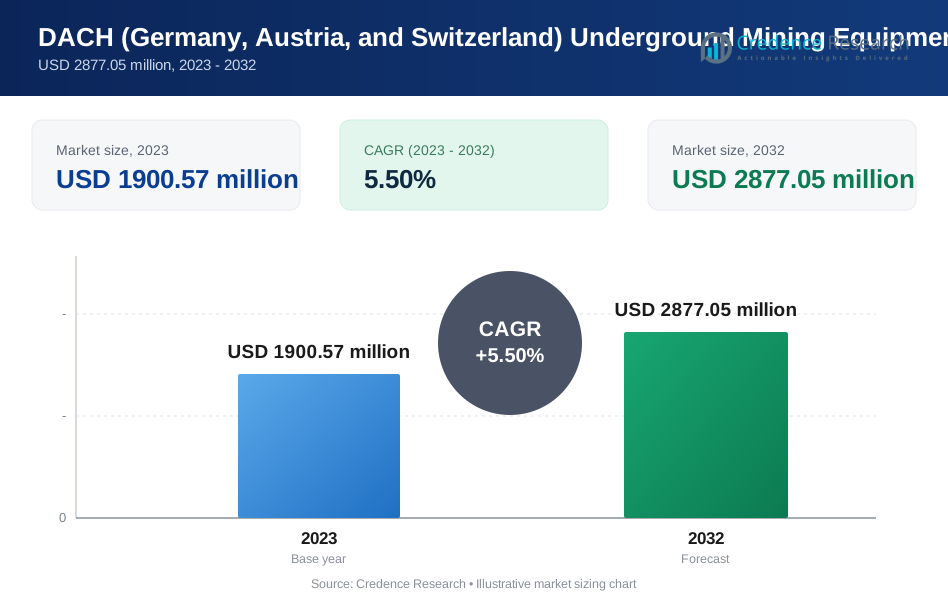
| DACH Underground Mining Equipment Market Size 2023 | USD 1900.57 million |
| DACH Underground Mining Equipment Market, CAGR | 5.50% |
| DACH Underground Mining Equipment Market Size 2032 | USD 2877.05 million |
Market Overview
The DACH Underground Mining Equipment Market is projected to grow from USD 1900.57 million in 2023 to an estimated USD 2877.05 million by 2032, with a compound annual growth rate (CAGR) of 5.50% from 2024 to 2032. The market’s expansion is driven by the increasing demand for mining operations and technological advancements that are enhancing mining efficiency and safety.
Several factors are driving the market, including the growing need for efficient and sustainable mining solutions in the DACH region. Innovations in equipment, such as automated machinery, electric vehicles, and improved safety systems, are playing a key role in increasing operational efficiency and reducing environmental impact. Furthermore, the rising demand for minerals and metals, coupled with the expansion of mining projects, is also fueling the market’s expansion.
Geographically, the DACH region, which includes Germany, Austria, and Switzerland, is a major hub for underground mining activities. Germany, in particular, is known for its robust mining industry, with significant investments in advanced mining technologies. Key players in the market include Caterpillar Inc., Atlas Copco AB, Komatsu Ltd., and Sandvik AB, all of which offer a wide range of cutting-edge underground mining equipment to meet the growing demands of the industry.
Market Drivers
Technological Advancements in Mining Equipment
Technological innovations are one of the key drivers propelling the growth of the DACH Underground Mining Equipment Market. In recent years, advancements in machinery such as automated and remotely operated equipment, electric-powered mining vehicles, and sophisticated underground drilling systems have revolutionized the mining process. These innovations not only enhance operational efficiency but also contribute to improved safety standards within the mining industry. For instance, the integration of automated and remotely operated equipment has led to remarkable improvements in operational safety and efficiency. Companies are increasingly deploying autonomous vehicles that can be controlled from a distance, allowing operators to manage machinery without entering hazardous environments. This shift not only minimizes the risk of accidents but also enhances productivity by ensuring continuous operation without human presence in dangerous areas. Moreover, advancements in real-time data analytics and IoT-enabled devices have transformed how mining companies monitor equipment performance. The use of smart sensors allows for continuous monitoring of machinery health, enabling predictive maintenance that reduces unexpected breakdowns and operational downtime. This proactive approach ensures that equipment is functioning optimally, thus enhancing overall productivity and cost-effectiveness. With these technological advancements, mining companies in the DACH region are adopting state-of-the-art equipment to improve mining output, minimize operational costs, and comply with increasing safety and environmental standards.
Increasing Demand for Raw Materials
The global demand for raw materials such as coal, copper, gold, and other minerals is a critical driver for the growth of the underground mining equipment market in the DACH region. As industries such as automotive, electronics, and construction continue to expand, the demand for minerals required for manufacturing processes has surged. For instance, the automotive sector's growing reliance on electric vehicles (EVs) and batteries has increased the demand for critical metals like lithium, cobalt, and nickel, all of which require extensive mining operations, often conducted underground. To meet these rising demands, mining companies are investing heavily in upgrading and expanding their underground mining operations, thus increasing the need for modern and efficient mining equipment. In the DACH region, which is a key industrial hub in Europe, mining companies are ramping up operations to extract the necessary minerals to supply these expanding sectors. This surge in demand for raw materials directly stimulates the growth of the underground mining equipment market.
Rising Focus on Sustainability and Environmental Regulations
As environmental concerns grow globally, the DACH region is placing greater emphasis on sustainable mining practices. Stricter environmental regulations and the need to reduce the carbon footprint of mining operations are compelling companies to invest in eco-friendly equipment and processes. Underground mining operations are typically more energy-intensive than surface mining, which raises environmental concerns related to emissions and energy consumption. To address these challenges, mining companies are increasingly adopting electric-powered mining equipment, which reduces reliance on diesel and minimizes harmful emissions in underground environments. Moreover, advancements in battery technology and the development of zero-emission underground mining vehicles have led to cleaner operations that not only align with stricter environmental regulations but also offer long-term cost savings. In the DACH region, where environmental sustainability is a priority, regulatory pressure is driving the shift toward cleaner, more efficient mining solutions. The growing emphasis on reducing environmental impact while maintaining productivity is therefore a key driver for the demand for advanced underground mining equipment.
Need for Improved Operational Efficiency and Cost Reduction
The mining industry is under constant pressure to improve operational efficiency and reduce costs, which is further driving the demand for innovative underground mining equipment. Mining operations, particularly in challenging underground environments, require equipment that can operate at maximum efficiency to reduce downtime and operational expenses. Modern underground mining equipment is designed to optimize performance and enhance productivity by using automated systems that streamline workflows, improve resource allocation, and reduce energy consumption. Moreover, the adoption of real-time monitoring and data analytics allows mining companies to optimize equipment usage, identify potential issues, and extend the lifespan of machinery. These efficiency gains are crucial in an industry where margins can be thin, and operational costs can significantly affect profitability. As mining companies face increasing pressures to improve cost-effectiveness and optimize their operations, the demand for high-performance underground mining equipment is expected to grow. Additionally, equipment that is more durable and reliable, requiring less maintenance, further contributes to the reduction of operational costs. Thus, the need for enhanced operational efficiency and cost reduction remains a key driver of the underground mining equipment market in Europe.
Market Trends
Adoption of Automation and Remote-Controlled Equipment**
One of the most significant trends in the DACH Underground Mining Equipment Market is the increasing adoption of automation and remote-controlled mining equipment. As the mining industry continues to face pressures to improve productivity while ensuring worker safety, automation technologies have emerged as an essential solution. For instance, companies are increasingly deploying autonomous systems, such as driverless trucks and remotely operated drilling machines, to enhance safety and productivity. This shift not only minimizes human exposure to hazardous conditions but also allows for continuous operation, which is crucial in deep mining environments where downtime can be costly. Advanced data analytics and machine learning are also being utilized for real-time performance monitoring and predictive maintenance, further optimizing operational efficiency in complex mining projects across the DACH region. These advancements help mitigate the risks associated with deep underground operations, such as cave-ins, exposure to hazardous gases, and machinery accidents. Automation also contributes to increased efficiency, as equipment can operate continuously without the need for breaks, thus improving operational output.
Emphasis on Electrification and Sustainability**
Another notable trend in the DACH Underground Mining Equipment Market is the growing emphasis on electrification and sustainable mining practices. In response to stringent environmental regulations and the increasing demand for greener operations, mining companies are transitioning from diesel-powered equipment to electric-powered alternatives. For instance, electric haul trucks, loaders, and drill rigs are gaining momentum in the region. This shift is driven by the need to comply with stringent environmental regulations and the growing demand for sustainable practices. Electric vehicles not only help reduce carbon emissions but also offer operational cost savings by decreasing fuel consumption and maintenance requirements. Furthermore, battery-powered equipment has the added advantage of reducing noise and heat generation, which improves working conditions in underground environments. As part of the broader trend toward sustainability, companies are also investing in renewable energy solutions, such as solar and wind power, to reduce their dependence on fossil fuels. This focus on electrification aligns with both global sustainability goals and the DACH region's commitment to maintaining environmentally responsible mining operations. The growing integration of electric equipment, coupled with advancements in battery technology, is helping the region move toward a more sustainable and energy-efficient mining sector.
Market Restraints and Challenges
High Initial Capital Investment and Maintenance Costs**
One of the major challenges facing the DACH Underground Mining Equipment Market is the high initial capital investment and ongoing maintenance costs associated with advanced mining equipment. As mining operations evolve to adopt more sophisticated technologies such as automation, electrification, and autonomous systems, the price of acquiring and maintaining these advanced machines increases significantly. Many mining companies, especially small to mid-sized enterprises, may find the upfront costs prohibitive, limiting their ability to invest in cutting-edge equipment. Additionally, while modern equipment can offer significant long-term savings through improved efficiency and reduced labor costs, the costs related to regular maintenance, spare parts, and system upgrades can be substantial. This financial burden may delay equipment upgrades and technological adoption, hindering overall productivity improvements. Furthermore, with the DACH region's highly competitive mining industry, companies must balance the need for advanced equipment with the constraints of managing operational and financial risks, which may restrict growth for some players in the market.
Environmental and Regulatory Compliance Challenges
Another significant restraint in the DACH Underground Mining Equipment Market is the complex and evolving regulatory environment, particularly concerning environmental standards and sustainability requirements. The DACH region, comprising Germany, Austria, and Switzerland, enforces strict environmental regulations on mining operations, focusing on issues such as emissions, waste disposal, and water usage. Compliance with these regulations requires significant investment in environmentally friendly technologies and practices, including the adoption of electric-powered equipment and renewable energy solutions. However, while these innovations contribute to sustainability goals, they often come with high implementation costs and technical challenges. Moreover, the dynamic nature of environmental laws can create uncertainty for mining operators, as regulations may change or become more stringent over time, forcing companies to continuously adapt their equipment and operations. These regulatory complexities can increase operational costs, extend project timelines, and complicate the decision-making process for mining companies, which may act as a barrier to expansion or upgrading equipment in the market.
Market Segmentation Analysis
By Product Type
Mining equipment in the DACH region is segmented by product type, including mining loaders, trucks, drills, bolters, and shearers. Mining loaders are essential for transporting ore and materials within narrow underground tunnels, with demand driven by the need for equipment capable of handling varying loads and confined spaces, while automated and electric-powered models are increasing their efficiency. Mining trucks, which are used to transport large quantities of materials to surface level, are evolving with a trend toward larger, more fuel-efficient, and electric-powered models, reflecting the growing emphasis on sustainability and energy efficiency. Mining drills, critical for both soft and hard rock applications, are becoming increasingly automated and remotely controlled, allowing for precise drilling and greater safety. Mining bolters, used to secure tunnels and ensure safety, are also seeing demand growth as safety regulations tighten, with automation improving efficiency and minimizing operator risks. Finally, mining shearers, primarily used in longwall mining, are advancing with automated and robotic systems to improve precision and productivity, particularly in coal and hard rock mining operations. Each of these product types plays a crucial role in enhancing the safety, efficiency, and sustainability of underground mining operations in the DACH region.
By Mining Technique
The DACH Underground Mining Equipment Market is segmented into soft rock and hard rock mining techniques, each requiring specialized equipment. Soft rock mining, which involves the extraction of minerals like coal, gypsum, and limestone from sedimentary or non-igneous formations, is experiencing growth in the region due to the increasing demand for these materials in industries such as construction, cement, and energy. Advanced machinery, including mining loaders, trucks, and automated bolters, is helping enhance productivity and safety in these environments. On the other hand, hard rock mining, which targets more challenging minerals like gold, silver, and copper, requires highly specialized equipment due to the extreme conditions. The DACH region’s mining industry relies heavily on advanced drilling, bolting, and shearing technologies for hard rock mining, with increasing adoption of automated systems to enhance safety and operational efficiency in these hazardous environments.
Segments
Based on Product Type
- Mining Loaders
- Mining Trucks
- Mining Drills
- Mining Bolters
- Mining Shearer
Based on Mining Technique
- Soft Rock Mining
- Hard Rock Mining
Based on End User
- Mining Operators
- Rental Service Providers
Based on Region
- Germany
- Austria
- Switzerland
Regional Analysis
Germany (70%)
Germany is the dominant player in the DACH region, accounting for approximately 70% of the total market share. The country has a well-established mining industry with a strong focus on coal, potash, and hard rock mining. Germany’s mining operations are increasingly moving toward deeper and more complex underground sites, requiring advanced machinery such as automated mining loaders, electric mining trucks, and sophisticated drilling systems. Moreover, the push for sustainability in the mining industry has led German companies to adopt environmentally friendly equipment, such as electric-powered and hybrid mining vehicles. Innovations in automation and robotics also make Germany a leader in the adoption of cutting-edge underground mining technologies. With its highly competitive industrial landscape and the presence of leading equipment manufacturers like Caterpillar and Komatsu, Germany remains the largest contributor to the DACH underground mining equipment market.
Austria (20%)
Austria holds a smaller but significant market share of around 20%, driven by the country’s mining of hard minerals such as copper and salt. Austrian mining operations typically involve hard rock mining, which requires robust and advanced mining equipment for drilling, excavation, and safety measures. The Austrian government’s commitment to sustainability and strict environmental regulations has led to an increased demand for energy-efficient and low-emission mining equipment. Additionally, Austria is witnessing a growing trend of digitalization and automation in mining operations, which is further spurring the demand for high-tech underground mining machinery.
Key players
- Terex Corporation
- SANY Group
- CNH Industrial
- AB Volvo
- Caterpillar Inc.
- Hitachi Co. Ltd.
- Atlas Copco AB
- Komatsu Ltd.
- Hyundai Heavy Industries Company Limited
- Joy Global
- Metso Corporation
- Sandvik AB
- Thyssenkrupp
- Liebherr
Competitive Analysis
The DACH Underground Mining Equipment Market is highly competitive, with major players like Terex Corporation, SANY Group, CNH Industrial, AB Volvo, and Caterpillar Inc. leading the industry. These companies offer a broad range of mining equipment, including loaders, trucks, drills, and bolters, catering to both soft and hard rock mining operations. Key players such as Hitachi Co. Ltd., Atlas Copco AB, and Komatsu Ltd. are focusing on advanced technologies like automation and electric-powered equipment to enhance productivity and reduce environmental impact. Companies like Hyundai Heavy Industries and Joy Global (now part of Komatsu) have strengthened their position through innovation in underground mining machinery. Metso Corporation, Sandvik AB, and Thyssenkrupp are also key contributors, offering cutting-edge solutions in mining equipment and machinery for tunneling, drilling, and material handling. Liebherr rounds out the list with specialized machines aimed at improving safety and operational efficiency. The competition is driven by technological advancements, sustainability initiatives, and a focus on operational cost reduction.
Recent Developments
- In April 2023, Caterpillar launched its new Cat® R1700 underground loader, designed for improved operator safety and productivity. This model features advanced automation capabilities and a more efficient powertrain, aimed at enhancing operational performance in underground mining environments.
- In March 2023, Sandvik introduced the latest version of its AutoMine system, which allows for fully autonomous operation of underground loaders and trucks. This upgrade enhances safety and efficiency by enabling continuous operations in hazardous environments without human presence.
- In July 2023, Hitachi announced the launch of its new ZW220-6 wheel loader, equipped with advanced technology to optimize fuel efficiency and reduce emissions. This model is particularly suited for underground mining operations where environmental compliance is crucial.
- In January 2024, Komatsu unveiled its new hybrid electric underground haul truck, which combines electric and diesel power to improve fuel efficiency and reduce greenhouse gas emissions. This innovative vehicle is designed to meet the increasing demand for sustainable mining solutions.
- In February 2024, Atlas Copco launched its new range of battery-powered underground drilling rigs. These rigs are designed to reduce noise and emissions while providing high performance in challenging underground conditions.
- In March 2024, Volvo CE introduced a new line of electric excavators specifically tailored for underground mining applications. These machines are designed to enhance operational efficiency while minimizing environmental impact.
- In April 2024, Hyundai Heavy Industries announced the launch of its new series of compact excavators optimized for underground mining tasks. These machines feature improved maneuverability and advanced safety features.
Market Concentration and Characteristics
The Dach Underground Equipment Market exhibits a moderately concentrated structure, characterized by the presence of both established global players and emerging regional manufacturers. Key players such as Caterpillar Inc., Komatsu Ltd., Sandvik AB, and Atlas Copco AB hold significant market shares, driven by their extensive product portfolios, technological innovations, and focus on automation and sustainability. The market's competitive dynamics are shaped by rapid advancements in smart technologies, stringent environmental regulations, and the need for energy-efficient solutions. Smaller and regional players compete by offering cost-effective and specialized equipment, often catering to niche demands. Overall, the market's characteristics reflect a strong emphasis on precision engineering, safety, and adherence to regulatory standards, fostering ongoing product development and partnerships among stakeholders.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Mining Technique, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness a surge in automation technologies, enhancing operational efficiency, precision, and safety in underground mining and construction projects.
- Manufacturers will continue to develop energy-efficient and low-emission equipment to meet stringent regulatory standards and reduce environmental impact, driving demand for sustainable solutions.
- Smart underground equipment, integrated with IoT, sensors, and real-time monitoring, will become more prevalent, providing data-driven insights to optimize operations.
- Government-led investments in urban infrastructure, including tunnels, subways, and public facilities, will boost demand for advanced underground equipment across the Dach region.
- The market will see increased demand for rental equipment services as companies seek flexible and cost-effective solutions to meet project needs without heavy upfront investment.
- Ongoing innovations in automation, AI, and machine learning will drive the development of next-generation underground equipment, further improving safety and productivity.
- Hybrid and fully electric underground machines will gain traction as companies strive to reduce carbon emissions and comply with environmental mandates.
- Manufacturers will emphasize safety features, including remote operation and automated hazard detection, to align with stringent workplace safety regulations.
- Key players will focus on strategic collaborations, mergers, and acquisitions to expand market share, drive innovation, and enhance their service offerings.
- While Germany will continue to dominate, Austria and Switzerland will experience steady growth driven by mining and tunneling activities, with regional regulations and sustainability goals shaping demand patterns.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Mining Equipment
Rapid innovation in automation, remote operation, and electric-powered machinery is enabling safer, more efficient, and cost-effective underground mining operations in the DACH region. These advancements reduce downtime, improve productivity, and help companies comply with stringent safety and environmental standards.
Increasing Demand for Raw Materials
Growth in industries such as automotive, electronics, and construction is driving up the need for minerals and metals, prompting mining companies in Germany, Austria, and Switzerland to expand underground operations and invest in modern equipment.
Rising Focus on Sustainability and Environmental Regulations
Strict environmental regulations and a regional emphasis on sustainability are pushing mining operators to adopt electric and low-emission equipment, reducing the carbon footprint of underground mining and aligning with regulatory requirements.
Need for Improved Operational Efficiency and Cost Reduction
Mining companies face ongoing pressure to optimize operations and reduce costs, leading to increased adoption of automated and durable underground mining equipment that minimizes downtime, maintenance, and labor expenses.
Expansion of Mining Projects and Urban Infrastructure
Government and private sector investments in new mining projects and urban infrastructure, such as tunnels and subways, are boosting demand for advanced underground mining equipment across the DACH region.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and growth forecast for the DACH Underground Equipment Market?
What factors are driving growth in the Dach Underground Equipment Market?
Why is Germany a major contributor to the market?
How is sustainability influencing market trends?
Which key players dominate the Dach Underground Equipment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Mining Operators
- 1.2.2 Rental Service Providers
- 1.3 By Product Type
- 1.3.1 Mining Loaders
- 1.3.2 Mining Trucks
- 1.3.3 Mining Drills
- 1.3.4 Mining Bolters
- 1.3.5 Mining Shearer
- 1.4 By Mining Technique
- 1.4.1 Soft Rock Mining
- 1.4.2 Hard Rock Mining
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1900.57 million → 2032: USD 2877.05 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1900.57 million → 2032: USD 2877.05 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mining Operators
- 12.3.7.2 Rental Service Providers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mining Loaders
- 12.4.7.2 Mining Trucks
- 12.4.7.3 Mining Drills
- 12.4.7.4 Mining Bolters
- 12.4.7.5 Mining Shearer
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mining Technique - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Soft Rock Mining
- 12.5.7.2 Hard Rock Mining
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 DACH (Germany, Austria, and Switzerland) Underground Mining Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Komatsu Ltd.
- 18.4 Sandvik AB
- 18.5 Atlas Copco AB
- 18.6 Hitachi Co. Ltd.
- 18.7 AB Volvo
- 18.8 Terex Corporation
- 18.9 Liebherr
- 18.10 Hyundai Heavy Industries Company Limited
- 18.11 Thyssenkrupp
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

