
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cluster Headache Market Size 2024 | USD 417.2 Million |
| Cluster Headache Market, CAGR | 5.9% |
| Cluster Headache Market Size 2032 | USD 659.9514 Million |
Market Overview:
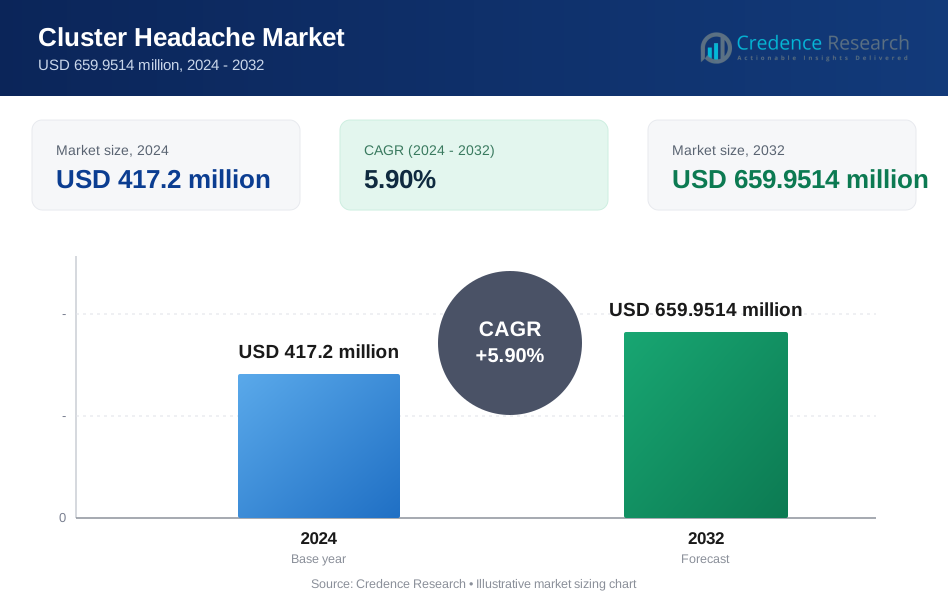
The Cluster Headache Market is projected to grow from USD 417.2 million in 2024 to USD 659.9514 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.9% over the forecast period. This growth is driven by an increasing awareness of cluster headaches, improved diagnosis rates, and ongoing research into more effective treatment options. Cluster headaches, a severe neurological disorder characterized by intense, recurrent headaches on one side of the head, are recognized as some of the most painful types of headaches. Rising awareness among healthcare professionals and patients about cluster headaches, along with advancements in targeted treatments, is anticipated to boost the market.
Key market drivers include increasing investment in research and development for innovative treatments and the availability of new therapies. Pharmaceutical companies are focusing on developing and introducing novel therapeutics, such as biologics and neuromodulation devices, to alleviate symptoms and improve patients’ quality of life. For example, biologic therapies targeting the calcitonin gene-related peptide (CGRP) are gaining traction for their efficacy in treating migraine and cluster headaches. Furthermore, the demand for non-invasive treatments, like gammaCore, a vagus nerve stimulation device, is increasing as patients seek alternatives to traditional medications. Expanding healthcare expenditures and government initiatives to support mental health and neurological disorder treatments further drive the market.
Regionally, North America holds a significant share of the cluster headache market due to well-established healthcare infrastructure, high diagnosis rates, and increasing adoption of advanced therapies. The United States leads in this region, benefiting from active clinical research and significant investment in neurology. Europe follows closely, with countries like Germany and the UK contributing to the demand for advanced treatment options. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth over the forecast period, driven by a growing awareness of cluster headaches, improved healthcare access, and rising healthcare expenditure in countries like Japan, China, and India. The Middle East and Africa also show potential for growth as healthcare systems expand and focus on treating neurological disorders. These regional dynamics highlight the market’s broadening reach and rising importance in addressing neurological health globally.
Market Drivers:
Increased Awareness and Diagnosis Rates:
As awareness of cluster headaches grows, more patients and healthcare professionals recognize the symptoms, leading to higher diagnosis rates. For instance, the World Health Organization (WHO) emphasizes that cluster headaches are often misdiagnosed or undiagnosed due to the rarity and severity of symptoms. However, recent awareness campaigns and educational initiatives by neurological health organizations have helped both physicians and patients better identify cluster headaches. This increased awareness contributes to a higher demand for specialized treatments and supports ongoing market expansion.
Advancements in Treatment Options:
The development of innovative therapies for cluster headaches has significantly advanced in recent years, focusing on both pharmacological and non-pharmacological solutions. Pharmaceutical companies are investing in research to explore the potential of biologic therapies, such as monoclonal antibodies targeting calcitonin gene-related peptide (CGRP). For example, companies like Teva Pharmaceuticals have introduced CGRP inhibitors that show promise in reducing the frequency and severity of headache episodes. Additionally, non-invasive neuromodulation devices, like the gammaCore, which provides vagus nerve stimulation, offer effective alternatives to traditional medications and are gaining popularity for their ease of use and safety profile.
Rising Healthcare Expenditures and Government Support:
Increased healthcare spending, particularly in developed countries, is another driver supporting the cluster headache market. Governments in regions like North America and Europe are investing in healthcare initiatives focused on neurological disorders, including cluster headaches. For example, the National Institute of Neurological Disorders and Stroke (NINDS) in the U.S. funds research projects aimed at understanding headache disorders, which includes investigating potential treatments and supportive therapies for cluster headaches. This governmental support not only facilitates innovation but also ensures better access to advanced therapies for patients.
Growing Demand for Non-Invasive Therapies:
There is a growing preference for non-invasive treatment options among patients, driven by concerns over side effects associated with long-term medication use. As a result, devices that provide non-invasive neuromodulation, such as transcutaneous vagus nerve stimulators, are becoming increasingly popular. According to data from the American Headache Society, non-invasive therapies are well-received by patients, as they often reduce reliance on prescription medications and provide quick relief from symptoms. This shift towards non-invasive treatment methods is encouraging manufacturers to focus on developing and refining such devices, which is expected to further drive the market in the coming years.
Market Trends:
Growing Use of Biologics and Targeted Therapies:
The use of biologics is expanding within the cluster headache market, with targeted therapies showing promising results in reducing the frequency and intensity of headache episodes. Monoclonal antibodies targeting calcitonin gene-related peptide (CGRP) pathways, such as those developed by companies like Eli Lilly, have been effective in managing cluster headaches. These therapies specifically inhibit CGRP, a protein linked to pain signaling, which can mitigate cluster headache symptoms. According to the American Headache Society, CGRP inhibitors offer new hope for patients who have not responded well to traditional treatments, driving adoption in clinical settings.
Increased Investment in Neuromodulation Devices:
There is a rising trend in the adoption of neuromodulation devices for treating cluster headaches, particularly due to patient demand for non-invasive and drug-free options. For example, electroCore’s gammaCore device, which utilizes transcutaneous vagus nerve stimulation (VNS), is gaining traction as a portable, non-invasive solution. Clinical trials cited by the National Institute of Neurological Disorders and Stroke (NINDS) have shown that VNS can provide substantial relief by stimulating the vagus nerve, reducing pain levels, and diminishing the frequency of attacks. This trend aligns with a broader healthcare shift toward wearable, non-invasive medical devices.
Technological Advancements in Telemedicine for Headache Management:
Telemedicine is increasingly being utilized for managing chronic headache conditions, including cluster headaches. The convenience and accessibility of remote consultations have allowed patients to seek specialized headache treatment more readily. For instance, the American Telemedicine Association reported a 38% increase in virtual consultations for headache-related issues over the past two years. Digital platforms offer access to headache specialists, enabling timely interventions and helping patients track symptoms and treatment effectiveness from home. This trend is particularly valuable for those living in remote areas or lacking easy access to specialized neurological care.
Personalized Medicine and Genomic Research:
As personalized medicine gains momentum, genomic research is being leveraged to develop individualized treatments for cluster headaches. By analysing genetic predispositions, researchers aim to tailor therapies that align with each patient’s unique genetic makeup. For example, the Human Genome Research Institute has initiated studies exploring genetic factors associated with cluster headaches, which may identify new therapeutic targets. Such advancements hold the potential to improve treatment outcomes by addressing the underlying genetic factors contributing to headache disorders, reflecting a broader trend toward precision medicine in neurological care.
Market Challenges Analysis:
High Treatment Costs and Limited Accessibility:
The high cost of advanced cluster headache treatments, such as biologics and neuromodulation devices, limits accessibility, especially in low- and middle-income countries. These treatments often require substantial out-of-pocket expenses, even in developed regions with insurance coverage. The World Health Organization (WHO) has noted that access to specialized neurological care is uneven, leading to disparities in treatment options and healthcare outcomes. For patients without adequate insurance, high treatment costs create a significant financial burden, impacting the overall accessibility of effective therapies.
Regulatory Complexities and Lengthy Approval Processes:
The stringent regulatory requirements enforced by authorities like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) present significant barriers to market growth. To ensure patient safety, these agencies require extensive clinical trials for new therapies, which can significantly increase development costs and extend timelines. Smaller companies, in particular, struggle to meet these regulatory demands, which often restricts their ability to innovate and compete in the market. Additionally, the requirement for continuous post-market surveillance to monitor potential adverse effects further adds to the financial strain on manufacturers.
Patient Safety Concerns and Potential Side Effects:
Certain medications and biologic treatments for cluster headaches carry risks of adverse effects, especially with prolonged use. The National Institutes of Health (NIH) has highlighted that some drugs used for treating chronic headaches can lead to complications such as cardiovascular issues, necessitating careful patient monitoring. These safety concerns can deter patients from utilizing certain therapies, and healthcare providers may exercise caution when prescribing them, particularly for long-term management. This challenge underscores the importance of balancing effectiveness with patient safety.
Variability in Effectiveness of Non-Invasive Treatments:
While non-invasive neuromodulation devices are gaining popularity, their effectiveness can vary widely among patients. Devices like transcutaneous vagus nerve stimulators may provide substantial relief for some, but others experience limited or no benefit. This variability impacts patient confidence and can hinder the widespread adoption of these devices as a standalone treatment. Healthcare providers and manufacturers must navigate these limitations and work to improve the consistency and efficacy of non-invasive treatment options.
Market Segmentation Analysis:
By Type: The market is divided into episodic and chronic cluster headaches. Episodic cluster headaches, characterized by headache attacks occurring in clusters and followed by remission periods, account for the majority of cases. Chronic cluster headaches, where attacks occur without significant remission periods, represent a smaller but more challenging segment. The need for effective, long-term management solutions is especially critical for patients with chronic cluster headaches, driving demand for advanced therapeutics.
By Technology: Technological advancements in both pharmacological and non-pharmacological treatments are expanding options for cluster headache management. Pharmacological treatments, including triptans, oxygen therapy, and emerging biologic therapies targeting calcitonin gene-related peptide (CGRP), are widely used. Non-pharmacological approaches, such as neuromodulation devices like vagus nerve stimulators, are gaining traction as patients increasingly seek non-invasive alternatives. The development of these innovative technologies supports improved symptom management and patient quality of life.
By End User: The primary end users for cluster headache treatments are hospitals, specialty clinics, and home care settings. Hospitals and specialty clinics are crucial for administering initial treatments, particularly for severe cases requiring oxygen therapy or injectable medications. Neurology clinics offer targeted expertise and are often the sites for ongoing patient management and advanced neuromodulation therapies. Home care settings are growing in importance, as more non-invasive devices allow patients to manage symptoms independently, providing convenience and reducing the need for frequent clinical visits. This segmentation highlights the market’s adaptability to various treatment environments, underscoring the increasing accessibility of cluster headache care across healthcare settings.
Segmentations:
By Type- Episodic
- Chronic
- Fast-acting Drugs
- Long-term Drugs
- Short-term Drugs
- Oral
- Topical
- Intravenous
- Others
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America North America holds the largest share of the cluster headache market, accounting for approximately 40% of the global market. The demand in this region is driven by well-established healthcare infrastructure, high patient awareness, and access to advanced therapies. The United States, in particular, benefits from substantial investment in neurological research and innovation, leading to the availability of cutting-edge treatment options such as biologics and neuromodulation devices. Government initiatives and support from organizations like the National Institutes of Health (NIH) further contribute to the market's growth by funding research into effective cluster headache therapies. Additionally, the presence of major pharmaceutical companies in the U.S. accelerates the development and availability of new treatments.
Europe Europe represents around 30% of the global cluster headache market. Countries such as Germany, the United Kingdom, and France lead the region, benefiting from robust healthcare systems and increasing patient awareness of neurological conditions. The European Medicines Agency (EMA) ensures stringent regulatory oversight, contributing to high standards for new treatments and patient safety. Additionally, rising healthcare spending and initiatives from non-profit organizations focused on headache disorders are fostering growth in the European market. Europe also experiences high adoption rates of non-invasive therapies, such as vagus nerve stimulation, due to the region’s focus on non-pharmacological approaches to pain management.
Asia-Pacific The Asia-Pacific region is the fastest-growing market, capturing approximately 20% of the global share. Rapid urbanization, changing lifestyles, and improved access to healthcare are driving demand for cluster headache treatments in countries like Japan, China, and India. Japan, in particular, has a high level of technological advancement and a growing interest in neuromodulation devices. Meanwhile, increased healthcare spending and government initiatives aimed at raising awareness about neurological disorders are expanding the market across China and India. Despite challenges related to healthcare infrastructure in some areas, the region’s growing middle class is increasing demand for advanced and accessible treatment options, positioning Asia-Pacific as a significant contributor to future market growth.
Latin America Latin America holds approximately 5% of the market share, with growth primarily driven by Brazil and Mexico. While the region has less access to advanced treatments compared to North America and Europe, there is a growing awareness of cluster headaches and an increasing focus on improving neurological healthcare. However, economic constraints and limited healthcare infrastructure in some countries restrict market expansion. Nevertheless, the presence of key players in the region and government-led initiatives to improve healthcare access are gradually addressing these limitations.
Middle East & Africa The Middle East & Africa region accounts for around 5% of the global cluster headache market. The demand is mainly concentrated in Gulf Cooperation Council (GCC) countries, where governments are investing in healthcare infrastructure to support treatment for neurological disorders, including cluster headaches. In African nations, limited healthcare resources and lower awareness of cluster headaches present challenges, though efforts to improve healthcare access and awareness are ongoing. The increasing number of healthcare projects in the Middle East, particularly in countries like the UAE and Saudi Arabia, is expected to drive demand for cluster headache treatments in the coming years.
Key Player Analysis:
- Eli Lilly and Company
- Teva Pharmaceutical Industries Ltd.
- Amgen Inc.
- Novartis AG
- GlaxoSmithKline plc
- electroCore, Inc.
- Pfizer Inc.
- Johnson & Johnson
- Zosano Pharma Corporation
- AbbVie Inc.
Competitive Analysis:
The cluster headache market is highly competitive, with key players focusing on innovative treatment options to address the complex needs of patients. Major pharmaceutical companies like Eli Lilly, Amgen, and Teva Pharmaceutical lead the market with advanced biologic therapies, such as CGRP inhibitors, which have demonstrated effectiveness in reducing headache frequency and intensity. Additionally, companies like electroCore are pioneering non-invasive neuromodulation devices, such as the gammaCore, to meet patient demand for non-pharmacological alternatives. These established players are investing heavily in research and development, not only to bring novel therapies to market but also to expand their existing product portfolios. The competitive landscape is shaped by regulatory challenges and the need for continued innovation to improve treatment efficacy and accessibility. As a result, companies are actively pursuing strategic partnerships, acquisitions, and clinical advancements to strengthen their market positions and better serve a growing global patient population.
Recent Developments:
- In 2024, Teva announced the discontinuation of its Phase III ENFORCE trial for fremanezumab in treating chronic cluster headaches. A futility analysis indicated that the study's primary endpoint was unlikely to be met, prompting Teva to focus on other potential applications for fremanezumab, particularly for episodic migraine and related conditions.
- Despite ending the chronic cluster headache program, Teva continues to evaluate fremanezumab in episodic cluster headache trials. The company believes CGRP-targeting therapies may offer benefits for patients with episodic clusters and is maintaining research efforts in this area, as fremanezumab holds promise for mitigating episodic headache frequency and intensity.
- In 2023, Teva shared data from its Phase IV UNITE study, which showed that AJOVY® (fremanezumab) reduced symptoms of depression and disability in migraine patients with major depressive disorder. The study underscores the potential for CGRP inhibitors to provide broader quality-of-life improvements for patients with neurological and psychiatric comorbidities.
- Teva presented additional data from the PEARL study in 2022, demonstrating sustained, long-term effectiveness of AJOVY® in reducing migraine frequency over time. This real-world study supports the potential for CGRP inhibitors as a durable treatment option for chronic headache conditions, which may influence future applications for cluster headaches as well.
Market Concentration & Characteristics:
The cluster headache market is moderately concentrated, with a few leading companies, such as Teva Pharmaceutical, Eli Lilly, and Amgen, holding substantial market shares due to their advanced portfolios in biologics and neuromodulation devices. These players focus heavily on research and development to improve treatment efficacy, targeting the calcitonin gene-related peptide (CGRP) pathway, a significant area of innovation for headache therapies. The market’s concentration is driven by high entry barriers, such as stringent regulatory requirements from the FDA and EMA, which ensure treatment safety and effectiveness but also extend approval timelines. Additionally, these established companies invest in clinical trials and real-world studies, demonstrating long-term effectiveness and broadening treatment options for cluster headache patients. This concentrated market structure fosters strong competition, pushing companies to continuously innovate and develop more targeted, patient-centric therapies to improve overall quality of life for cluster headache sufferers.
Report Coverage:
The research report offers an in-depth analysis based on Type, Drug Type, Route of Administration, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing awareness of cluster headaches and improved diagnostic capabilities will drive demand for specialized treatments as patients and healthcare providers recognize the symptoms earlier.
- The development of targeted biologics, particularly those inhibiting the calcitonin gene-related peptide (CGRP) pathway.
- Non-invasive neuromodulation devices, such as vagus nerve stimulators, will gain popularity among patients seeking drug-free options.
- Advances in personalized medicine will support the creation of customized treatments based on genetic markers, offering more precise and effective care for cluster headache patients.
- Investments in research and development by major pharmaceutical companies will drive innovation in both pharmacological and non-pharmacological therapies, expanding treatment options.
- Telemedicine and remote patient monitoring will enhance access to specialized headache care, allowing more patients to receive timely interventions, particularly in underserved regions.
- Expansion of healthcare infrastructure in emerging markets, particularly in Asia-Pacific, will improve access to advanced cluster headache treatments and increase market penetration.
- Rising healthcare expenditures and improved insurance coverage for neurological treatments will support greater patient access to high-cost therapies like biologics and neuromodulation devices.
- Strategic partnerships and mergers among key players will strengthen their market positions, enabling faster development and broader distribution of innovative therapies.
- Regulatory agencies will continue to influence the market by setting high safety and efficacy standards, encouraging companies to prioritize patient safety in treatment development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cluster Headache Market?
What factors are driving the growth of the Cluster Headache Market?
What are some challenges faced by the Cluster Headache Market?
Who are the major players in the Cluster Headache Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cluster Headache Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cluster Headache Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 417.2 million → 2032: USD 659.9514 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cluster Headache Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cluster Headache Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cluster Headache Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cluster Headache Market Drivers
- 3.3 Cluster Headache Market Restraints & Challenges
- 3.4 Cluster Headache Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cluster Headache Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cluster Headache Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cluster Headache category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cluster Headache Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cluster Headache Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cluster Headache market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cluster Headache Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cluster Headache Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cluster Headache Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cluster Headache (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cluster Headache Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cluster Headache Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cluster Headache Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cluster Headache Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cluster Headache Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cluster Headache Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cluster Headache Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cluster Headache Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cluster Headache Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
