
Emergency Hospital Bed Market Overview:
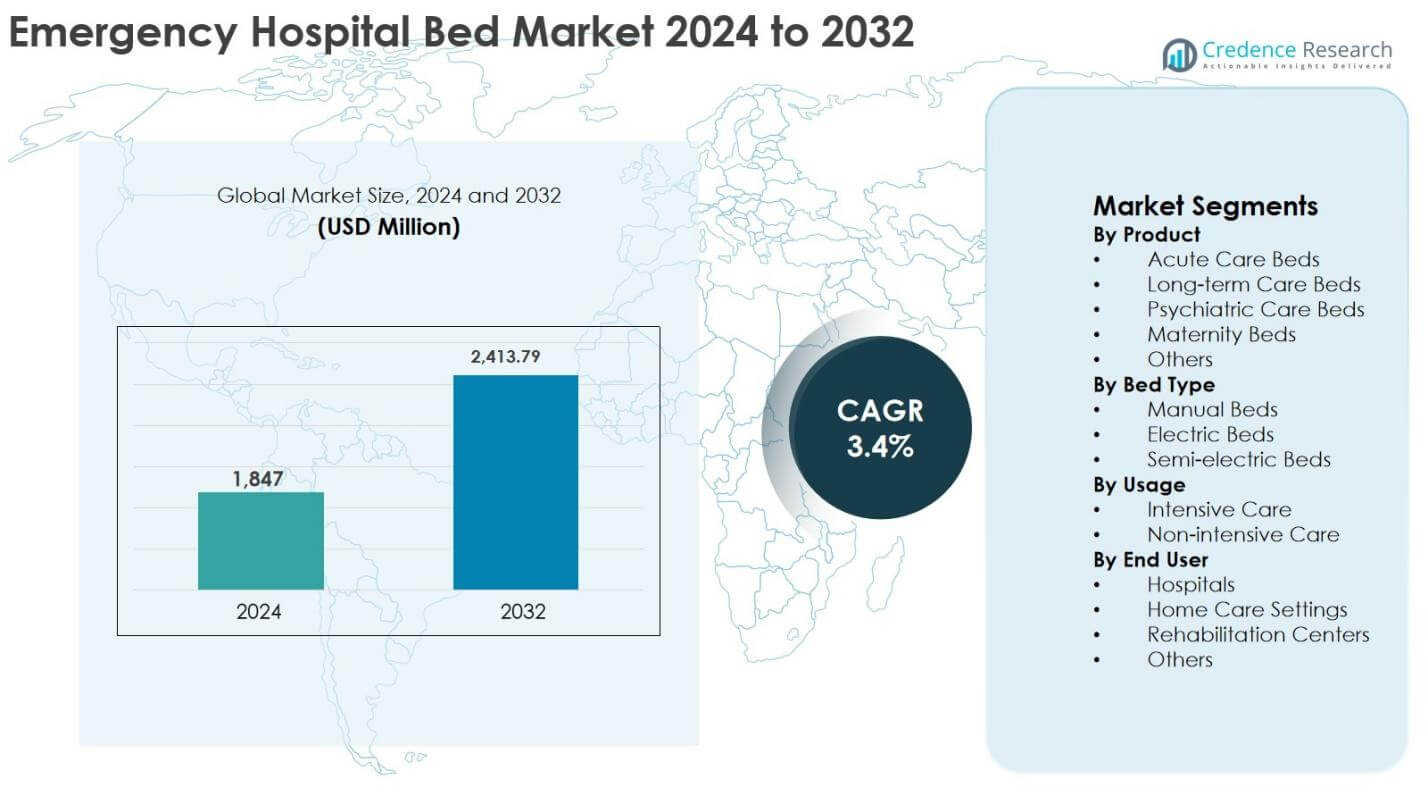
Emergency Hospital Bed market size was valued at USD 1,847 million in 2024 and is anticipated to reach USD 2,413.79 million by 2032, growing at a CAGR of 3.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Emergency Hospital Bed Market Size 2024 | USD 1,847 million |
| Emergency Hospital Bed Market, CAGR | 3.4% |
| Emergency Hospital Bed Market Size 2032 | USD 2,413.79 million |
Emergency Hospital Bed Market Insights
- Market growth is driven by rising emergency admissions, increasing trauma and accident cases, and continuous expansion of hospital and emergency care infrastructure, particularly in urban and high-density regions, supporting sustained demand for acute and intensive care beds.
- Key trends include growing adoption of electric and semi-electric beds, while acute care beds remained the dominant product segment with a 38.6% market share in 2024 due to their extensive use in emergency departments and short-term critical care settings.
- The market is moderately consolidated, with leading players such as Stryker Corporation, Hill-Rom Holdings Inc., and Invacare Corporation focusing on product innovation, safety features, and global distribution expansion.
- North America led the market with a 34.8% share in 2024, followed by Europe at 28.6% and Asia-Pacific at 24.1
- z%, while Latin America and Middle East & Africa together accounted for the remaining share, supported by gradual healthcare infrastructure development.
Emergency Hospital Bed Market Segmentation Analysis:
By Product
The Emergency Hospital Bed market by product is led by Acute Care Beds, which accounted for 38.6% of the market share in 2024, driven by their extensive use in emergency departments, trauma centers, and short-term critical care settings. Rising emergency admissions, increasing accident cases, and growth in hospital infrastructure continue to support demand. Long-term Care Beds and Maternity Beds follow, supported by aging populations and rising birth-related hospitalizations, while Psychiatric Care Beds maintain steady adoption due to increasing mental health admissions and specialized ward expansions across public and private hospitals.
- For instance, Hillrom (now part of Baxter International) reported that its med-surg and ICU bed portfolio was a core driver of growth in its Patient Support Systems segment, reflecting strong utilization in acute care and emergency settings.
By Bed Type
By bed type, Electric Beds dominated the Emergency Hospital Bed market with a 46.2% share in 2024, owing to their superior patient positioning, ease of operation, and compatibility with advanced monitoring equipment. Hospitals increasingly prefer electric beds to improve caregiver efficiency and patient safety in high-acuity environments. Semi-electric Beds held a 32.1% share, supported by cost-effectiveness and balanced functionality, while Manual Beds retained demand in budget-constrained facilities and developing regions due to lower upfront costs and minimal maintenance requirements.
- For instance, Stryker’s ProCuity and Hillrom-branded Progressa beds are widely deployed in intensive care and step-down units to enable integrated monitoring, advanced lateral rotation, and safer patient mobilization.
By Usage
In terms of usage, Intensive Care applications accounted for the largest share at 41.8% in 2024, driven by the rising prevalence of critical illnesses, post-surgical monitoring needs, and emergency admissions requiring continuous observation. Advanced ICU beds with mobility assistance, pressure relief, and integrated monitoring features are increasingly prioritized. Non-intensive Care usage represented 58.2% of installations, supported by high patient turnover in general wards, emergency observation units, and recovery areas, where durability, flexibility, and cost efficiency remain key purchasing drivers.
Key Growth Drivers
Rising Emergency Admissions and Trauma Cases
The Emergency Hospital Bed market is significantly driven by the continuous rise in emergency admissions linked to road accidents, cardiovascular events, respiratory disorders, and sudden disease outbreaks. Rapid urbanization and increasing lifestyle-related health risks have placed sustained pressure on emergency departments to expand capacity. Hospitals increasingly prioritize emergency beds that enable rapid patient positioning, safe mobility, and compatibility with monitoring equipment to manage high patient inflow. In addition, growing exposure to natural disasters and public health emergencies has encouraged governments to strengthen emergency preparedness, directly accelerating investments in specialized emergency hospital beds across both developed and emerging healthcare systems.
- For instance, the World Health Organization has reported that road traffic injuries cause around 1.19 million deaths annually worldwide, contributing heavily to emergency and trauma admissions.
Expansion of Healthcare Infrastructure and Hospital Capacity
Ongoing expansion of healthcare infrastructure is a key driver supporting growth in the Emergency Hospital Bed market. Governments and private investors are funding new hospitals, trauma centers, and emergency units to improve access to urgent care services. Many secondary hospitals are being upgraded with advanced emergency wards, increasing demand for acute and intensive care beds. Public healthcare funding programs and hospital modernization initiatives are further encouraging the replacement of outdated beds with advanced emergency solutions. This expansion trend is particularly strong in emerging economies, where rising population and healthcare utilization rates necessitate higher emergency bed availability.
- For instance, India’s Pradhan Mantri Swasthya Suraksha Yojana (PMSSY) and Ayushman Bharat Health Infrastructure Mission have financed new AIIMS institutions and upgraded district hospitals, adding capacity for emergency and critical care beds.
Growing Aging Population and Chronic Disease Burden
The increasing geriatric population and rising prevalence of chronic diseases continue to drive demand in the Emergency Hospital Bed market. Older patients are more susceptible to sudden medical emergencies such as falls, strokes, and cardiac complications, leading to higher emergency hospitalizations. Chronic conditions including diabetes, hypertension, and renal disorders frequently result in acute episodes requiring immediate care. Emergency beds equipped with pressure-relief systems, height adjustability, and enhanced safety features are increasingly adopted to improve outcomes for elderly patients, supporting sustained market growth as healthcare systems adapt to demographic shifts.
Key Trends & Opportunities
Increasing Adoption of Electric and Smart Emergency Beds
The Emergency Hospital Bed market is witnessing a strong trend toward the adoption of electric and smart beds with automated positioning, remote control functions, and integrated safety features. These beds enhance patient comfort, reduce caregiver strain, and improve operational efficiency in emergency settings. Integration with monitoring devices and hospital information systems enables better workflow management and patient tracking. This trend creates opportunities for manufacturers to differentiate through innovation, smart technologies, and ergonomic designs, particularly as hospitals increasingly focus on patient-centric and technology-driven emergency care environments.
- For instance, Baxter (Hillrom) promotes its Centrella Smart+ and Progressa beds with advanced patient positioning, integrated scales, and connectivity to nurse call and monitoring systems to support safer, more efficient care.
Rising Demand from Emerging Healthcare Markets
Emerging economies offer substantial growth opportunities for the Emergency Hospital Bed market due to rising healthcare expenditure, expanding hospital networks, and improving emergency care standards. Asia-Pacific, Latin America, and the Middle East are investing heavily in emergency infrastructure to support growing populations and increasing trauma cases. Expansion of private hospitals and medical tourism further fuels demand for modern emergency beds. Favorable government policies supporting local manufacturing and healthcare modernization enhance long-term market potential for global and regional suppliers.
- For instance, India’s Production-Linked Incentive (PLI) schemes and medical device parks aim to boost domestic production of hospital equipment, while Brazil and Mexico have introduced incentives and regulations encouraging localized manufacturing and technology transfer in medical devices.
Key Challenges
High Capital Investment and Cost Sensitivity
High upfront costs associated with advanced emergency hospital beds remain a major challenge for the Emergency Hospital Bed market. Electric and ICU-grade beds require significant investment, limiting adoption in budget-constrained public hospitals and smaller healthcare facilities. Ongoing maintenance and servicing expenses further increase total ownership costs, slowing replacement cycles. These financial barriers restrict penetration of premium bed solutions and force manufacturers to balance innovation with affordability in cost-sensitive markets.
Complex Regulatory and Procurement Processes
Regulatory compliance and complex procurement procedures pose challenges to market growth in the Emergency Hospital Bed market. Hospitals must meet strict safety, quality, and infection-control standards, which vary across regions and increase certification timelines. Public-sector procurement often involves lengthy tender processes, delaying purchasing decisions. Additionally, fragmented regulatory frameworks across countries complicate market entry and expansion, extending sales cycles and increasing operational complexity for manufacturers.
Regional Analysis
North America
North America dominated the Emergency Hospital Bed market with a market share of 34.8% in 2024, supported by well-established healthcare infrastructure and high emergency admission volumes. The region benefits from widespread adoption of advanced electric and ICU-grade beds across hospitals and trauma centers. Rising prevalence of chronic diseases, an aging population, and high rates of road accidents continue to drive emergency care demand. Strong healthcare spending, favorable reimbursement policies, and continuous hospital modernization initiatives further support market growth. The United States accounts for the majority of regional revenue due to large hospital networks and rapid adoption of technologically advanced emergency beds.
Europe
Europe accounted for 28.6% of the Emergency Hospital Bed market share in 2024, driven by strong public healthcare systems and increasing investments in emergency and critical care infrastructure. Countries such as Germany, France, and the United Kingdom lead demand due to rising emergency admissions and aging populations. Government funding for hospital capacity expansion and replacement of outdated beds supports steady growth. Emphasis on patient safety, infection control, and ergonomic designs has increased adoption of electric and semi-electric emergency beds. Eastern European countries are also contributing through gradual healthcare infrastructure upgrades and increased focus on emergency preparedness.
Asia-Pacific
Asia-Pacific held a 24.1% share of the Emergency Hospital Bed market in 2024 and is the fastest-growing regional market. Rapid population growth, rising accident rates, and increasing healthcare expenditure are major growth drivers. Countries such as China, India, and Japan are investing heavily in hospital expansion and emergency care capacity. Government healthcare reforms, urbanization, and growing private hospital chains are accelerating demand for emergency beds. Although manual and semi-electric beds remain prevalent due to cost sensitivity, adoption of electric beds is increasing in tertiary hospitals, supporting long-term regional growth.
Latin America
Latin America accounted for 7.1% of the Emergency Hospital Bed market share in 2024, supported by gradual improvements in healthcare infrastructure and rising emergency care demand. Countries such as Brazil, Mexico, and Argentina are expanding public hospitals and trauma care facilities to address increasing accident and chronic disease cases. Government healthcare programs and private sector investments are driving replacement of aging hospital equipment. However, budget constraints limit widespread adoption of high-end electric beds, maintaining strong demand for cost-effective manual and semi-electric beds. Ongoing healthcare reforms are expected to support moderate market growth.
Middle East & Africa
The Middle East & Africa region 5.4% of the Emergency Hospital Bed market share in 2024, driven by increasing healthcare investments and expanding emergency medical services. Gulf Cooperation Council countries are leading regional growth due to high healthcare spending, hospital modernization projects, and rising trauma cases. In contrast, parts of Africa face infrastructure and funding limitations, restricting adoption of advanced emergency beds. Demand remains strong for durable and cost-efficient solutions. Government initiatives to improve emergency response systems and international healthcare investments are gradually strengthening market growth across the region.
Emergency Hospital Bed Market Segmentations:
By Product
- Acute Care Beds
- Long-term Care Beds
- Psychiatric Care Beds
- Maternity Beds
- Others
By Bed Type
- Manual Beds
- Electric Beds
- Semi-electric Beds
By Usage
- Intensive Care
- Non-intensive Care
By End User
- Hospitals
- Home Care Settings
- Rehabilitation Centers
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Emergency Hospital Bed market is characterized by the presence of well-established global manufacturers and specialized regional players competing on product innovation, pricing, and distribution reach. Leading companies such as Stryker Corporation, Hill-Rom Holdings Inc., Invacare Corporation, Arjo, and LINET dominate the market through broad product portfolios covering electric, semi-electric, and critical care beds. These players focus on ergonomic design, patient safety, and integration with emergency and ICU monitoring systems. Companies such as PARAMOUNT BED CO., LTD., Midmark Corp, Howard Wright Limited, and Stiegelmeyer GmbH & Co. KG strengthen competition through regional expansion and cost-effective offerings. Continuous product upgrades, hospital partnerships, and expansion in emerging markets remain key strategic priorities across the competitive environment.
Key Player Analysis
- Novum Medical Products
- LINET
- Midmark Corp
- Joson-Care Enterprise Co., Ltd.
- Arjo
- Stiegelmeyer GmbH & Co. KG
- Invacare Corporation
- PARAMOUNT BED CO., LTD.
- Howard Wright Limited
- Stryker Corporation
Recent Developments
- In February 2025, Stryker launched the ProCeed hospital bed, a new hospital bed designed to enhance patient care and simplify caregiver operations in markets outside the U.S. with improved durability and usability features.
- In June 2025, Stryker introduced the APAISER X1 advanced ICU air mattress, integrating with its SmartMedic system to enhance patient comfort and caregiver efficiency in critical care settings, indicating product ecosystem expansion in beds and support surfaces.
- In June 2025, PROMA REHA showcased its GENEO Green Line hospital bed at the Medlab West Africa trade fair in Lagos, highlighting its advanced features to distributors and healthcare professionals expanding into new markets.
Report Coverage
The research report offers an in-depth analysis based on Product, Bed Type, Usage, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Emergency Hospital Bed market will continue to expand steadily, supported by sustained growth in emergency admissions and trauma care requirements.
- Hospitals will increasingly prioritize replacement of outdated beds with modern emergency and critical care bed solutions.
- Adoption of electric and semi-electric beds will rise as healthcare providers focus on patient safety and caregiver efficiency.
- Integration of emergency beds with monitoring and hospital information systems will gain wider acceptance.
- Aging populations will drive higher demand for advanced emergency beds with mobility and pressure-relief features.
- Expansion of emergency and trauma centers in emerging economies will support long-term market growth.
- Manufacturers will focus on ergonomic design and infection-control features to meet evolving clinical standards.
- Cost-effective emergency bed solutions will see strong demand in budget-constrained healthcare facilities.
- Strategic partnerships with hospitals and healthcare groups will strengthen supplier market presence.
- Regulatory emphasis on quality and safety standards will influence product development and purchasing decisions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Emergency Hospital Bed market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Emergency Hospital Bed market projected to grow between 2024 and 2032?
Which Emergency Hospital Bed market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Emergency Hospital Bed market?
Who are the leading companies in the Emergency Hospital Bed market?
Which region commanded the largest share of the Emergency Hospital Bed market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Emergency Hospital Bed Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Emergency Hospital Bed Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,847 million → 2032: USD 2,413.79 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Emergency Hospital Bed Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Emergency Hospital Bed Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Emergency Hospital Bed Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Emergency Hospital Bed Market Drivers
- 3.3 Emergency Hospital Bed Market Restraints & Challenges
- 3.4 Emergency Hospital Bed Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Emergency Hospital Bed Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Emergency Hospital Bed Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Emergency Hospital Bed category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Emergency Hospital Bed Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Emergency Hospital Bed Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Emergency Hospital Bed. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Emergency Hospital Bed Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Emergency Hospital Bed Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Emergency Hospital Bed Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Emergency Hospital Bed (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Emergency Hospital Bed
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Emergency Hospital Bed Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Emergency Hospital Bed Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Emergency Hospital Bed Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Emergency Hospital Bed Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Emergency Hospital Bed Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Emergency Hospital Bed Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Emergency Hospital Bed Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Emergency Hospital Bed Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
