
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ethylene Carbonate Market Size 2023 | USD 291.5 million |
| Ethylene Carbonate Market, CAGR | 4.70% |
| Ethylene Carbonate Market Size 2032 | USD 420.93 million |
Market Overview
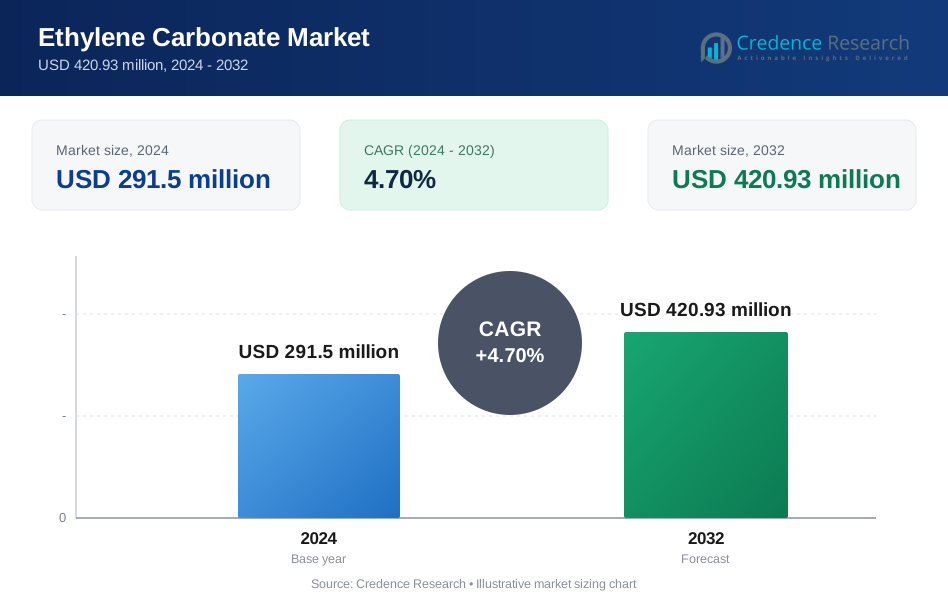
The Ethylene Carbonate market is projected to grow from USD 291.5 million in 2024 to USD 420.93 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.70%.
The Ethylene Carbonate market is driven by increasing demand for lithium-ion batteries, particularly in the electric vehicle and consumer electronics sectors, where ethylene carbonate serves as a critical electrolyte component. Additionally, the growing adoption of ethylene carbonate in the manufacturing of lubricants, coatings, and plastics is contributing to market expansion. Trends indicate a surge in research and development activities aimed at enhancing the efficiency and performance of ethylene carbonate applications. Environmental regulations and the shift towards sustainable and high-performance materials further propel market growth, highlighting ethylene carbonate's role in advancing technology and sustainability initiatives.
The Ethylene Carbonate market is characterized by significant regional activity and key players across various geographies. North America and Europe are prominent markets due to their advanced chemical industries and stringent environmental regulations. In Asia-Pacific, China and Japan are major contributors, driven by high demand for lithium-ion batteries and growing chemical production capabilities. Key players such as BASF SE, Mitsubishi Chemical Corporation, and Huntsman Corporation lead with extensive R&D and production capacities. In Asia, companies like Shandong Shida Shenghua Chemical Group and Toagosei Co., Ltd. are pivotal in meeting regional demand and driving market growth.
Market Drivers
Soaring Demand for Lithium-Ion Batteries
Ethylene Carbonate (EC) plays a pivotal role in the electrolyte formulation for lithium-ion batteries, which are essential for the widespread adoption of electric vehicles (EVs), portable electronics, and renewable energy storage systems. The global demand for lithium-ion batteries is projected to increase almost seven-fold, reaching 4.7 terawatt-hours in 2030. The surging demand for these batteries is a significant driver for the EC market. As consumers and industries increasingly shift towards EVs to reduce carbon footprints and improve energy efficiency, the reliance on high-performance lithium-ion batteries grows. This trend is expected to continue, bolstering the demand for EC, a critical component in ensuring the reliability and efficiency of these energy storage systems.
Expanding Applications Beyond Batteries
While lithium-ion batteries remain a dominant driver, EC also finds diverse applications in other sectors, contributing to market growth. In the lubricant industry, EC enhances efficiency and reduces friction, making it a valuable additive. For instance, in the lubricant industry, EC is a valuable additive that enhances efficiency and reduces friction. Additionally, EC is used in coatings and plasticizers, where it improves performance and durability. The expansion of these sectors, driven by industrial growth and the demand for high-performance materials, further supports the market for EC. As industries seek to improve product performance and meet regulatory standards, the versatility of EC ensures its continued relevance and application across various domains.
Rise of the Asia-Pacific Market
The Asia-Pacific region, particularly China, is experiencing significant growth in the EC market. In 2021, the Asia-Pacific market’s volume surged to 910.6 hundred tonnes, showcasing a growth of 7.5% (2019-2022). Factors such as rising disposable incomes, a booming EV industry, and stringent environmental regulations promoting the adoption of electric vehicles contribute to this regional expansion. China, as a major manufacturing hub for electronics and EVs, drives the demand for EC. Additionally, government initiatives and policies supporting green technologies and sustainable development further propel the market. As the region continues to prioritize environmental sustainability and technological advancement, the demand for EC is poised to grow, making Asia-Pacific a key player in the global market.
Focus on Sustainability and Technological Advancements
As environmental concerns escalate, there is a heightened focus on sustainable and efficient technologies like electric vehicles, which strengthens the demand for EC as a vital component in lithium-ion batteries. For instance, the production of EC relies on specific precursor chemicals, the prices of which can be subject to unpredictable fluctuations in the global market. However, the direct carboxylation of CO2 with ethylene glycol emerges as a promising green synthesis route. Technological advancements in EC production methods are also shaping the market landscape. Innovations aimed at increasing production efficiency and reducing costs make EC more accessible and affordable for various applications. These advancements not only support the growing demand but also enhance the sustainability of EC production. The ongoing research and development in this field are expected to yield significant improvements, ensuring that EC remains a cornerstone of modern, eco-friendly technologies.
Market Trends
Shifting Focus on High-Performance EC and Regional Production Hubs
As the demand for longer-range electric vehicles (EVs) and high-performance electronics continues to rise, the need for Ethylene Carbonate (EC) with enhanced properties is becoming increasingly important. For instance, research has been conducted on EC with better thermal stability and conductivity, which are crucial for modern lithium-ion batteries. This shift towards high-performance EC is essential for supporting the next generation of EVs and electronic devices. This trend has led to intensified research on higher purity grades and formulations that can improve battery performance and safety. Manufacturers are focusing on developing EC that offers better thermal stability and conductivity to meet the stringent requirements of modern lithium-ion batteries. This shift towards high-performance EC is crucial for supporting the next generation of EVs and electronic devices, which demand more reliable and efficient energy storage solutions. Concurrently, the Asia-Pacific region, particularly China, remains a dominant producer of EC due to its established manufacturing infrastructure and booming EV industry. However, North America and Europe are expected to see increased regional production to address supply chain concerns and enhance self-sufficiency. The expansion of production hubs in these regions is driven by the need to mitigate risks associated with over-reliance on imports and to support local industries' growing demand for EC. This regional diversification in production is poised to strengthen the global supply chain and ensure a steady supply of EC to meet the rising market demands.
Focus on Recycling, Resource Recovery, and Market Consolidation
Sustainability is a major concern in the EC market, leading to a growing trend towards developing efficient recycling processes for EC recovered from spent lithium-ion batteries. For instance, recycling methods such as direct recycling, pyrometallurgy, hydrometallurgy, bio-hydrometallurgy (bioleaching), and electrometallurgy are generally used to resynthesize LIBs. These methods aim to reclaim high-purity EC that can be reused in new batteries, creating a more sustainable lifecycle for lithium-ion batteries. This not only addresses environmental concerns but also provides economic benefits by lowering the costs associated with raw material procurement. This focus on recycling and resource recovery is essential for reducing the reliance on virgin EC and minimizing the environmental impact of battery production. Advances in recycling technologies aim to reclaim high-purity EC that can be reused in new batteries, thereby creating a more sustainable lifecycle for lithium-ion batteries. This not only addresses environmental concerns but also provides economic benefits by lowering the costs associated with raw material procurement. In addition to recycling efforts, there is a push towards the exploration of alternative feedstocks for EC production. Traditionally derived from fossil fuels, there is a growing interest in bio-based EC production using renewable resources like plant-derived ethylene oxide. This shift aligns with the increasing demand for sustainable solutions and supports the broader movement towards reducing the carbon footprint of industrial processes. The development of bio-based EC could significantly contribute to the sustainability goals of the industry by providing a greener alternative to conventional production methods.
Market Challenges Analysis
Price Volatility of Raw Materials and Regulatory Stringency
The production of Ethylene Carbonate (EC) is heavily reliant on raw materials such as ethylene oxide, which are subject to price fluctuations driven by the volatility of oil and gas markets. These price swings can significantly impact the cost structure of EC production, creating uncertainty and instability in the market. Manufacturers face the challenge of managing these cost fluctuations while maintaining competitive pricing for their products. Strategies to mitigate this issue include diversifying feedstock sources, potentially incorporating bio-based alternatives, to reduce dependence on fossil fuel-derived ethylene oxide. Additionally, long-term supply agreements and hedging mechanisms can provide some financial stability against raw material price volatility. The regulatory landscape surrounding the manufacturing and use of EC further complicates market dynamics. Stringent environmental and safety regulations require manufacturers to invest in compliance measures, which can increase production costs and limit operational flexibility. Adhering to these regulations is essential to ensure the safe handling and application of EC, but it also necessitates ongoing monitoring and adaptation to evolving standards. To address these challenges, companies are investing in research and development to create more efficient and environmentally friendly production methods that meet regulatory requirements while minimizing costs. Collaboration with regulatory bodies to streamline compliance processes can also help in managing the regulatory burden.
Limited Recycling Capacity and Geopolitical Tensions
Despite advancements in recycling technologies, the current capacity for recycling Ethylene Carbonate remains limited. This insufficiency creates a continued reliance on virgin EC production, raising concerns about the long-term sustainability of the market. Developing more efficient and scalable recycling processes is crucial to creating a closed-loop system for EC, which would reduce environmental impact and enhance resource utilization. Investment in recycling infrastructure and technology is necessary to expand capacity and improve the quality of recycled EC. Such efforts not only address sustainability concerns but also provide economic benefits by lowering the dependency on raw materials and reducing waste. The global nature of the EC market means it is susceptible to disruptions from geopolitical tensions. The interconnected network of producers and consumers can be significantly affected by political instability, trade disputes, and other geopolitical factors. These tensions can lead to supply chain disruptions, affecting the availability and cost of EC on the market. To mitigate these risks, promoting international collaboration and establishing diversified supply chains are essential. Building robust relationships with multiple suppliers and exploring regional production capabilities can help ensure a stable supply of EC. Additionally, strategic stockpiling and contingency planning can provide buffers against potential geopolitical disruptions.
Market Segmentation Analysis:
By Product Form:
In the Ethylene Carbonate (EC) market, product forms are primarily categorized into solid and liquid types. Solid EC is commonly used in applications where stability and easy handling are essential, such as in battery manufacturing and certain industrial processes. Its solid form simplifies storage and transportation, making it a preferred choice for large-scale production. Liquid EC, on the other hand, is favored for its ease of integration into various chemical formulations. It is predominantly used in applications requiring a more fluid and easily mixable ingredient, such as in surface coatings and plasticizers. The flexibility of liquid EC in blending and application processes supports its use in diverse industries, highlighting its versatility and essential role in the market.
By Application:
The EC market is segmented based on applications into lithium battery electrolytes, plasticizers, lubricants, surface coatings, and others. Lithium battery electrolytes represent the largest segment, driven by the growing demand for high-performance batteries in electric vehicles and consumer electronics. EC's role in enhancing battery efficiency and safety makes it critical in this sector. Plasticizers and lubricants utilize EC's properties to improve product performance and durability, while surface coatings benefit from its chemical stability and adhesion qualities. The "others" category includes miscellaneous applications where EC's unique characteristics are leveraged, expanding its market potential. This segmentation underscores the diverse utility of EC across various industrial applications, reflecting its broad and integral role in modern manufacturing and technology.
Segments:
Based on Product Form:
- Solid
- Liquid
Based on Application:
- Lithium battery electrolytes
- Plasticizers
- Lubricants
- Surface coatings
- Others
Based on End-use Industry:
- Oil and gas
- Automotive
- Pharmaceuticals
- Others
Based on the Geography:
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
Regional Analysis
Asia Pacific
The Asia Pacific region dominates the global ethylene carbonate market, commanding a substantial 45% market share. This leadership position is primarily attributed to the region's booming lithium-ion battery production industry, particularly in technological powerhouses like China, Japan, and South Korea. The rapid expansion of the electronics sector in these countries has created an unprecedented demand for ethylene carbonate, a crucial component in battery electrolytes. Moreover, governments across the region have implemented aggressive initiatives to promote electric vehicle adoption, further fueling the need for advanced battery technologies. This push towards electrification has led to a surge in ethylene carbonate consumption, as manufacturers strive to meet the growing demand for high-performance, long-lasting batteries. The region's thriving automotive industry, coupled with significant investments in renewable energy storage solutions, has created a perfect storm for ethylene carbonate market growth. As countries in Asia Pacific continue to prioritize sustainable development and clean energy transitions, the demand for ethylene carbonate is expected to maintain its upward trajectory.
North America
North America holds the second-largest market share at approximately 30%, driven by several key factors. The region has witnessed a rapid increase in electric vehicle adoption, with consumers and businesses alike embracing sustainable transportation solutions. This shift has been supported by the presence of major battery manufacturers who have established significant production capacities within the region. These manufacturers rely heavily on ethylene carbonate for their battery production processes, contributing substantially to market growth. Furthermore, North America's unwavering commitment to sustainable energy solutions has led to increased investments in grid-scale energy storage systems, which also utilize ethylene carbonate-based electrolytes. The pharmaceutical industry in the region has also played a role in driving demand, as ethylene carbonate finds applications in drug formulations and as a solvent in various pharmaceutical processes. The combination of these factors, along with ongoing research and development efforts to improve battery technologies, has solidified North America's position as a key player in the global ethylene carbonate market.
Key Player Analysis
- Oriental Union Chemical Corporation
- Huntsman Corporation
- BASF SE
- Mitsubishi Chemical Corporation
- Toagosei Co., Ltd.
- Asahi Kasei
- Prasol Chemicals Ltd
- Shandong Shida Shenghua Chemical Group
- Shandong Senjie Chemical
- Dubi Chem
- Alfa Aesar
Competitive Analysis
The Ethylene Carbonate market is highly competitive, featuring major players who leverage their extensive capabilities to gain market share. BASF SE and Mitsubishi Chemical Corporation are leaders in the field, renowned for their advanced production technologies and broad product portfolios. BASF SE focuses on innovation and efficiency, while Mitsubishi Chemical emphasizes high-purity and specialty products. Huntsman Corporation is notable for its global reach and strong R&D efforts, positioning itself prominently in the market. Oriental Union Chemical Corporation and Toagosei Co., Ltd. also play significant roles, offering diverse product lines and robust production facilities. Asahi Kasei and Prasol Chemicals Ltd. are key competitors with specialized offerings in both solid and liquid forms of Ethylene Carbonate. These companies are engaged in strategic partnerships, technological advancements, and regional expansions to enhance their competitive edge and meet the growing demand across various applications.
Recent Developments
- In 2024, Dow, headquartered in the United States, invested in discovering ethylene derivatives capacity.
- In 2023, BASF, a Germany-based company, boosted ethylene oxide capacity in Belgium, easing Germany's ethylene carbonate prices. The country is gaining momentum due to rising raw materials and changing energy prices, while downstream consumer demand remains weak, leading to lower rates and acquisitions.
- In 2023, Lotte Chemical, headquartered in South Korea, built a new plant with an investment of USD 502 million to produce high-purity organic solvents like ethylene carbonate and dimethyl carbonate for lithium-ion battery electrolytes.
Market Concentration & Characteristics
The Ethylene Carbonate market exhibits moderate to high concentration, with several key players dominating due to their extensive production capacities and technological expertise. Major companies such as BASF SE, Mitsubishi Chemical Corporation, and Huntsman Corporation hold substantial market shares, driven by their advanced manufacturing processes and broad product portfolios. The market is characterized by significant entry barriers, including high capital requirements and stringent regulatory compliance, which limit new entrants and consolidate the competitive landscape. Additionally, the industry is marked by a high level of technological innovation and R&D investment aimed at improving product performance and developing sustainable production methods. Regional concentration is notable, with Asia-Pacific emerging as a major production hub due to its favorable economic conditions and growing demand, while North America and Europe also play critical roles in market dynamics. This concentration fosters intense competition and drives continuous improvements in product quality and efficiency.
Report Coverage
The research report offers an in-depth analysis based on Product Form, Application, End-use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Ethylene Carbonate market is expected to grow steadily, driven by increasing demand for lithium-ion batteries in electric vehicles and consumer electronics.
- Advancements in production technology will likely enhance efficiency and reduce costs, broadening market accessibility.
- The focus on sustainability will drive the development of bio-based Ethylene Carbonate, catering to the growing demand for environmentally friendly solutions.
- Recycling and resource recovery initiatives will gain traction, aiming to create a closed-loop system for Ethylene Carbonate and minimize environmental impact.
- Asia-Pacific will continue to be a major growth region due to rising disposable incomes, expanding industrial activities, and increased production capacities.
- North America and Europe will see a rise in regional production to address supply chain concerns and enhance self-sufficiency.
- Innovation in Ethylene Carbonate applications, such as in new types of batteries and advanced coatings, will drive market expansion.
- The development of alternative feedstocks and more efficient recycling technologies will mitigate dependency on traditional raw materials.
- Competitive dynamics will lead to increased consolidation, as major players seek to expand their market reach and production capabilities.
- Regulatory support for sustainable and efficient technologies will bolster market growth and encourage further investment in R&D.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ethylene Carbonate Market?
What factors are driving the growth of the Ethylene Carbonate Market?
What are the key segments within the Ethylene Carbonate Market?
What are some challenges faced by the Ethylene Carbonate Market?
Who are the major players in the Ethylene Carbonate Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ethylene Carbonate Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ethylene Carbonate Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 291.5 million → 2032: USD 420.93 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ethylene Carbonate Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ethylene Carbonate Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ethylene Carbonate Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ethylene Carbonate Market Drivers
- 3.3 Ethylene Carbonate Market Restraints & Challenges
- 3.4 Ethylene Carbonate Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ethylene Carbonate Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ethylene Carbonate Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ethylene Carbonate category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ethylene Carbonate Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ethylene Carbonate Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ethylene Carbonate market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ethylene Carbonate Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ethylene Carbonate Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ethylene Carbonate Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ethylene Carbonate (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ethylene Carbonate Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ethylene Carbonate Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ethylene Carbonate Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ethylene Carbonate Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ethylene Carbonate Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ethylene Carbonate Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ethylene Carbonate Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ethylene Carbonate Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ethylene Carbonate Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
