
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
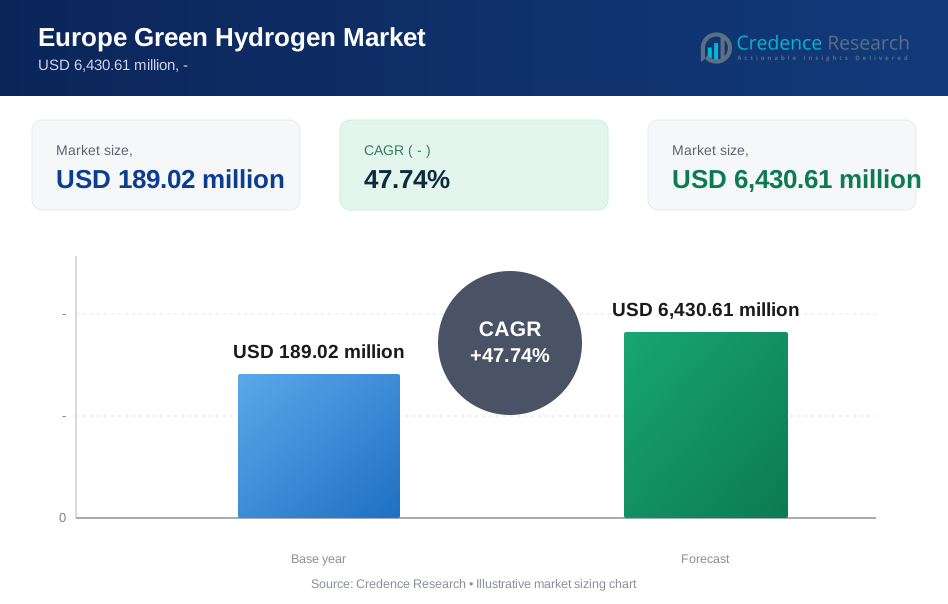
| Europe Green Hydrogen Market Size 2023 | USD 189.02 million |
| Europe Green Hydrogen Market, CAGR | 47.74% |
| Europe Green Hydrogen Market Size 2032 | USD 6430.61 Million |
Market Overview:
The European green hydrogen market is expected to experience remarkable growth in the coming years. It is projected to have a Compound Annual Growth Rate (CAGR) of 47.74%, with the market value increasing from USD 189.02 million in 2023 to an impressive USD 6430.61 million by 2032. This growth is primarily driven by the ambitious climate goals set by the European Union (EU), particularly through initiatives like the Green Deal and the Hydrogen Strategy. These initiatives aim to significantly increase the production, storage, and transportation infrastructure for green hydrogen in the region by 2030 and 2050.
One of the main factors contributing to this growth is the urgency to combat climate change and achieve net-zero emissions. Efforts to decarbonize hard-to-abate sectors such as transportation, steel production, and chemicals are leading to the adoption of clean energy sources like green hydrogen. Furthermore, advancements in electrolysis, storage, and transportation technologies are improving efficiency and reducing costs, making green hydrogen a more viable solution for decarbonization. Supportive government policies, including incentives and carbon pricing mechanisms, are also encouraging investment in green hydrogen projects and creating a favorable environment for market expansion.
However, there are challenges that the market must overcome, including high production costs, limited infrastructure, and regulatory uncertainty. Despite these challenges, there are significant opportunities for market growth, particularly in industrial decarbonization, renewable energy integration, blending with natural gas, and export potential. It will be crucial to leverage these opportunities while addressing the challenges in order to fully realize the potential of the European green hydrogen market and drive the transition to a more sustainable energy landscape.
Segmentation Analysis:
By Production Technology:
In Europe, green hydrogen production utilizes various technologies, with electrolysis being the predominant method. Electrolysis, powered by renewable electricity, divides water molecules to generate hydrogen and oxygen, aligning with the region's sustainability objectives. Another approach is biomass gasification, which involves converting organic matter into hydrogen gas through thermochemical processes. While biomass gasification offers potential for renewable hydrogen, careful consideration is necessary due to challenges related to feedstock availability and sustainability. Additionally, emerging technologies like photocatalytic water splitting, which utilizes sunlight to directly produce hydrogen from water, hold promise for the future but are still in early stages of development and commercialization.
By Application:
Green hydrogen finds applications in diverse sectors across Europe. In power generation, it is gaining traction as a clean fuel source, especially in regions aiming to decarbonize energy grids and reduce reliance on fossil fuels. Industries such as steel production and refining heavily depend on hydrogen, and green hydrogen provides a sustainable alternative to conventional methods that contribute to greenhouse gas emissions. Furthermore, the transportation sector is increasingly adopting hydrogen fuel cell vehicles as a zero-emission option, driving the need for the expansion of hydrogen refueling infrastructure.
By End-User:
A wide range of sectors in Europe are end-users of green hydrogen. Industries such as steel, chemicals, and refining are significant consumers of hydrogen, and green hydrogen offers an opportunity for these sectors to reduce their carbon footprint. Power generation companies are also transitioning towards renewable energy sources and exploring green hydrogen as a viable option for clean power generation. Additionally, fleet operators and public transport authorities in the transportation sector are seeking clean fuel alternatives, making green hydrogen an attractive prospect, particularly for heavy-duty vehicles.
By Geography:
The European green hydrogen market exhibits geographical variations across different regions. Western Europe, including countries like Germany, France, and the Netherlands, represents a mature market with established policies, ongoing projects, and supportive regulatory frameworks. Northern Europe, encompassing the Nordics and Baltic countries, benefits from abundant renewable energy resources and is actively pursuing green hydrogen development to decarbonize their economies. Meanwhile, Eastern European countries are showing increasing interest in green hydrogen, although their markets are still in the early stages of development.
Segments:
By Production Technology:
- Electrolysis (dominant segment)
- Biomass gasification
- Photocatalytic water splitting
By Application:
- Power generation
- Industrial processes (e.g., steel production, refining)
- Transportation sector (e.g., fueling hydrogen vehicles)
- Other applications
By End-User:
- Industrial sector
- Power generation companies
- Transportation sector (e.g., fleet operators, public transport authorities)
By Geography:
- Western Europe (mature market)
- Northern Europe (growing market)
- Eastern Europe (emerging market)
Market Drivers:
Environmental Concerns and Decarbonization Goals:
Europe is committed to addressing climate change and achieving carbon neutrality. As part of this commitment, green hydrogen is seen as a crucial element in the region's sustainable energy transition. The European Union (EU) aims to be climate-neutral by 2050 and reduce net emissions by 90% by 2040. To meet these ambitious targets, the region is actively exploring alternatives to fossil fuels. Green hydrogen, produced through electrolysis using renewable energy sources like solar and wind power, is emerging as a clean and versatile solution across various sectors, aligning with Europe's decarbonization goals.
Rising Demand for Sustainable Energy Solutions:
There is a growing emphasis on sustainability among consumers and businesses, leading to increased demand for eco-friendly energy sources. Green hydrogen, known for its emission-free nature at the point of use, is gaining significant attention as a sustainable energy solution. This rising demand not only drives investment in green hydrogen production but also fosters innovation in its application across industries, indicating promising growth prospects for the market. By 2024, the EU aims to develop 6GW of green hydrogen electrolysers within the EU, with an estimated cost of €5–9bn. This target is expected to scale up to 40 GW of EU-based electrolysers and 40 GW of non-EU-based electrolysers by 2030, with a cost of up to €44bn. Over the past eight years, the European Investment Bank has provided over €550 million in direct financial support for hydrogen technologies, mobilizing over €1.2 billion in overall investment.
Dependence on Fossil Fuel Imports and Energy Security Concerns:
Europe's heavy reliance on imported fossil fuels exposes it to price volatility and geopolitical risks, highlighting the need to enhance energy security. Domestic production of green hydrogen, powered by renewable resources, helps reduce dependence on external sources, thereby strengthening energy security. This strategic imperative incentivizes European countries to invest in green hydrogen infrastructure and production capacities.
Government Policies and Incentives:
Government support plays a crucial role in accelerating the transition to green hydrogen. Policymakers across Europe are implementing various measures, including financial subsidies, tax incentives, and regulatory frameworks, to promote the development and adoption of green hydrogen. These supportive policies create a favorable environment for investment, innovation, and market expansion, driving the growth of the green hydrogen sector.
Technological Advancements and Infrastructure Development:
Continuous advancements in electrolysis technology and cost reduction efforts are enhancing the competitiveness of green hydrogen. At the same time, significant investments are being made in infrastructure development, such as pipelines, storage facilities, and refueling stations, to establish a comprehensive hydrogen ecosystem. These technological strides and infrastructure initiatives pave the way for broader integration of green hydrogen into Europe's energy landscape, facilitating its role as a key driver of sustainable growth and decarbonization.
Market Trends:
Increasing Focus on Decarbonization and Energy Security: European nations are prioritizing the reduction of their reliance on fossil fuels and imported energy sources. In 2022, the total demand for hydrogen in Europe was estimated to be 8.19 Mt. Green hydrogen, produced using renewable energy sources like solar and wind, is emerging as a clean and sustainable alternative for various sectors, contributing to decarbonization goals and enhancing energy security.
Supportive Government Policies and Regulations: Governments across Europe are implementing policies and regulations that incentivize green hydrogen production and utilization. These include financial aid, subsidies, and favorable regulatory frameworks, creating a more attractive environment for investment in this nascent market. For instance, the EU hydrogen strategy, adopted in July 2020, aims to accelerate the development of clean hydrogen. The European Clean Hydrogen Alliance, established at the same time, is a forum bringing together industry, public authorities, and civil society to coordinate investment. Almost all EU Member States recognize the important role of hydrogen in their national energy and climate plans for the 2021-2030 period. The Council adopted conclusions on the EU hydrogen market in December 2020, with a focus on renewable hydrogen for decarbonization, recovery, and competitiveness. The EU has set the objective to become climate-neutral by 2050. The European Union's ambition is to import 10 Mt of renewable hydrogen from non-EU sources by 2030.
Technological Advancements and Cost Reductions: Research and development efforts are driving advancements in electrolysis technologies used for green hydrogen production. These advancements are leading to increased efficiency and cost reductions, making green hydrogen a more competitive energy source in the long run.
Developing Green Hydrogen Infrastructure: Investments are being made in building infrastructure for green hydrogen production, transportation, and storage. This includes establishing electrolyzer facilities, hydrogen pipelines, and storage facilities, creating a robust ecosystem for green hydrogen utilization.
Market Restraints and Challenges:
High Production Costs: Green hydrogen production through electrolysis remains significantly more expensive compared to traditional grey hydrogen derived from fossil fuels. The high cost of renewable electricity, electrolyzer technology, and infrastructure development contribute to this price disparity. This economic barrier discourages widespread investment and market uptake for green hydrogen across various sectors.
Limited Infrastructure and Distribution Network: The current infrastructure for transporting and storing green hydrogen is underdeveloped in most European regions. Building a dedicated hydrogen pipeline network and developing efficient storage solutions are crucial for large-scale commercialization. Without this infrastructure, transporting green hydrogen over long distances becomes economically and logistically challenging, hindering its broader utilization.
Policy and Regulatory Uncertainty: While the European Union has set ambitious green hydrogen development goals, some aspects of the regulatory framework remain unclear. Uncertainties regarding long-term policy support, including subsidies and carbon pricing mechanisms, can deter potential investors and slow down project development. Consistent and well-defined regulations are essential to provide a stable and predictable environment for market participants, encouraging investment and innovation in the green hydrogen sector.
Lack of Standardized Certification and Guarantees of Origin: Establishing a standardized system for certifying the green origin of hydrogen is crucial for ensuring consumer confidence and transparency. Without clear and verifiable green hydrogen certification, it becomes difficult to differentiate it from grey hydrogen, potentially undermining the environmental benefits associated with green hydrogen production.
Public Perception and Social Acceptance: Raising public awareness and addressing potential social concerns surrounding green hydrogen projects are important considerations. Concerns about safety associated with hydrogen storage and transportation need to be effectively addressed through public education and transparent communication strategies. Fostering social acceptance for green hydrogen infrastructure development will be crucial for facilitating its smooth integration into existing energy systems.
Key player:
- Air Liquide
- Air Products and Chemicals, Inc.
- Cummins Inc.
- Messer
- Ballard Power Systems
- TAIYO NIPPON SANSO CORPORATION
- McPhy Energy S.A.
- Mahler AGS GmbH
- Teledyne Technologies Incorporated
- Xebec Adsorption Inc.
- RESONAC HOLDINGS CORPORATION
- CALORIC
- NUVERA FUEL CELLS, LLC
- Plug Power Inc.
- Nel ASA
Recent Developments:
- In March 2023, Air Liquide announced the construction of an industrial scale innovative ammonia cracking pilot plant in Belgium. With innovative technology, the plant will enable the conversion of ammonia to hydrogen and contribute to the development of hydrogen as a key enabler in energy transition. The addition of the new plant will strengthen the company’s portfolio and augment its position across the industry.
- In October 2022, NUVERA FUEL CELLS, LLC signed an MoU with H2Boat, a system integrator for marine applications based in Italy, to supply a fuel cell engine. The company will provide the fuel cell engine named E-45 to the H2Boat for marine kind approval certification as well as for integration in H2Boat’s upcoming HP Energy Pack with P>40kW. The use of hydrogen fuel cells in boats will reduce the noise, vibrations, exhaust emissions, and environmental costs related to diesel-powered vessels. This will further strengthen the company’s business footprint in Europe.
Regional Analysis:
- Western Europe: This region is expected to hold a dominant market share throughout the forecast period. Stronger regulations, a well-developed hydrogen infrastructure, and a higher GDP compared to Central and Eastern Europe position Western Europe for early adoption and continued market leadership. Countries like Germany, France, and the Netherlands are at the forefront of green hydrogen development, with significant investments in electrolysis capacity, hydrogen refueling stations, and green hydrogen production facilities.
- Central and Eastern Europe: While starting from a lower base, Central and Eastern Europe is also expected to witness notable growth in the green hydrogen market. This is driven by increasing investments in renewable energy sources and growing government initiatives to promote green hydrogen production and utilization. Countries like Poland, Hungary, and Slovenia are implementing favorable policies and attracting investments to establish a green hydrogen ecosystem in the region.
Future Outlook:
- Ambitious renewable energy targets: European nations are setting ambitious renewable energy targets, and green hydrogen production aligns perfectly with these goals, creating a supportive policy environment.
- Falling renewable energy costs: The declining costs of solar and wind power, key sources of renewable electricity for green hydrogen production, will contribute to the economic viability of the market.
- Increasing hydrogen demand across sectors: Green hydrogen is expected to find applications in various sectors, including transportation, power generation, and industrial processes, fueling market growth.
- Development of hydrogen infrastructure: Investments in hydrogen refueling stations, pipelines, and storage facilities are crucial for market expansion and will likely accelerate in the coming years.
- Stringent carbon emission regulations: As regulations to curb carbon emissions become stricter, green hydrogen will emerge as a clean alternative to fossil fuels, driving market adoption.
- Technological advancements: Continuous research and development in electrolysis technologies used for green hydrogen production are expected to improve efficiency and reduce costs, further propelling market growth.
- Growing investor interest: The potential of the green hydrogen market is attracting significant investments from public and private entities, providing the necessary capital for market expansion.
- EU Hydrogen Strategy: The European Union's Hydrogen Strategy outlines a roadmap for developing a robust hydrogen economy in Europe, providing a clear direction and support for the market.
- Focus on green hydrogen production: As the focus shifts towards green hydrogen production methods powered by renewable energy, the market is expected to witness a surge in this specific segment.
- Regional variations in market growth: The green hydrogen market will likely experience variations in growth across European regions due to factors like existing infrastructure, renewable energy resources, and government initiatives.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Ambitious Climate and Decarbonization Goals
The European Union's Green Deal and Hydrogen Strategy set aggressive targets for carbon neutrality by 2050, driving investment and policy support for green hydrogen as a key enabler of deep decarbonization across multiple sectors.
Government Incentives and Policy Support
Financial subsidies, tax incentives, and regulatory frameworks across Europe are accelerating the development and adoption of green hydrogen, creating a favorable environment for market expansion and innovation.
Technological Advancements in Electrolysis
Continuous improvements in electrolysis efficiency and cost reductions are making green hydrogen production more economically viable, supporting its scale-up and integration into industrial and energy systems.
Energy Security and Reduced Fossil Fuel Dependence
Europe's desire to reduce reliance on imported fossil fuels and mitigate geopolitical risks is driving investment in domestic green hydrogen production, enhancing regional energy security.
Industrial Decarbonization and Sector Integration
Hard-to-abate sectors such as steel, chemicals, and transportation are increasingly adopting green hydrogen to meet emission reduction targets, fueling demand and supporting the development of supporting infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the European Green Hydrogen market between 2023 and 2032?
What factors are driving the growth of the European Green Hydrogen market?
Who are the major players in the European Green Hydrogen market?
How is the availability of European Green Hydrogen expanding, and through what channels?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Industrial sector
- 1.2.2 Power generation companies
- 1.2.3 Transportation sector
- 1.3 By Application
- 1.3.1 Power generation
- 1.3.2 Industrial processes
- 1.3.3 Transportation sector
- 1.3.4 Other applications
- 1.4 By Production Technology
- 1.4.1 Electrolysis
- 1.4.2 Biomass gasification
- 1.4.3 Photocatalytic water splitting
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 189.02 million → 2032: USD 6,430.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Green Hydrogen Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Green Hydrogen Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Green Hydrogen Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Green Hydrogen Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Green Hydrogen Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Green Hydrogen Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Green Hydrogen Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Green Hydrogen Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 189.02 million → 2032: USD 6,430.61 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Green Hydrogen Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Industrial sector
- 12.3.7.2 Power generation companies
- 12.3.7.3 Transportation sector
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Power generation
- 12.4.7.2 Industrial processes
- 12.4.7.3 Transportation sector
- 12.4.7.4 Other applications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Production Technology - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electrolysis
- 12.5.7.2 Biomass gasification
- 12.5.7.3 Photocatalytic water splitting
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Green Hydrogen End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Green Hydrogen Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Green Hydrogen Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Green Hydrogen Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Air Liquide
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Air Products and Chemicals, Inc.
- 18.4 Cummins Inc.
- 18.5 Ballard Power Systems
- 18.6 McPhy Energy S.A.
- 18.7 Nel ASA
- 18.8 Plug Power Inc.
- 18.9 Messer
- 18.10 Teledyne Technologies Incorporated
- 18.11 NUVERA FUEL CELLS, LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

