
AI and custom briefs reshape executive learning budgets
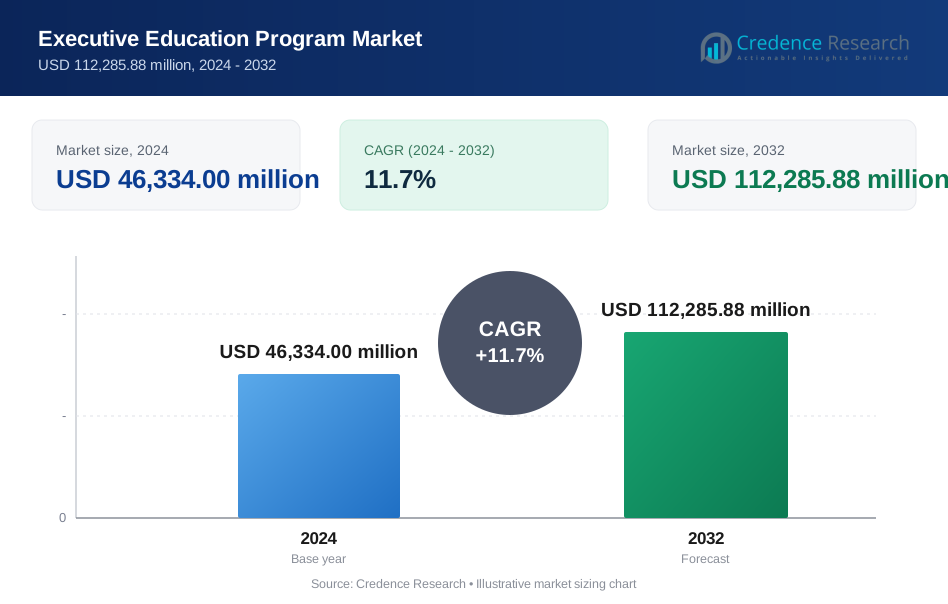
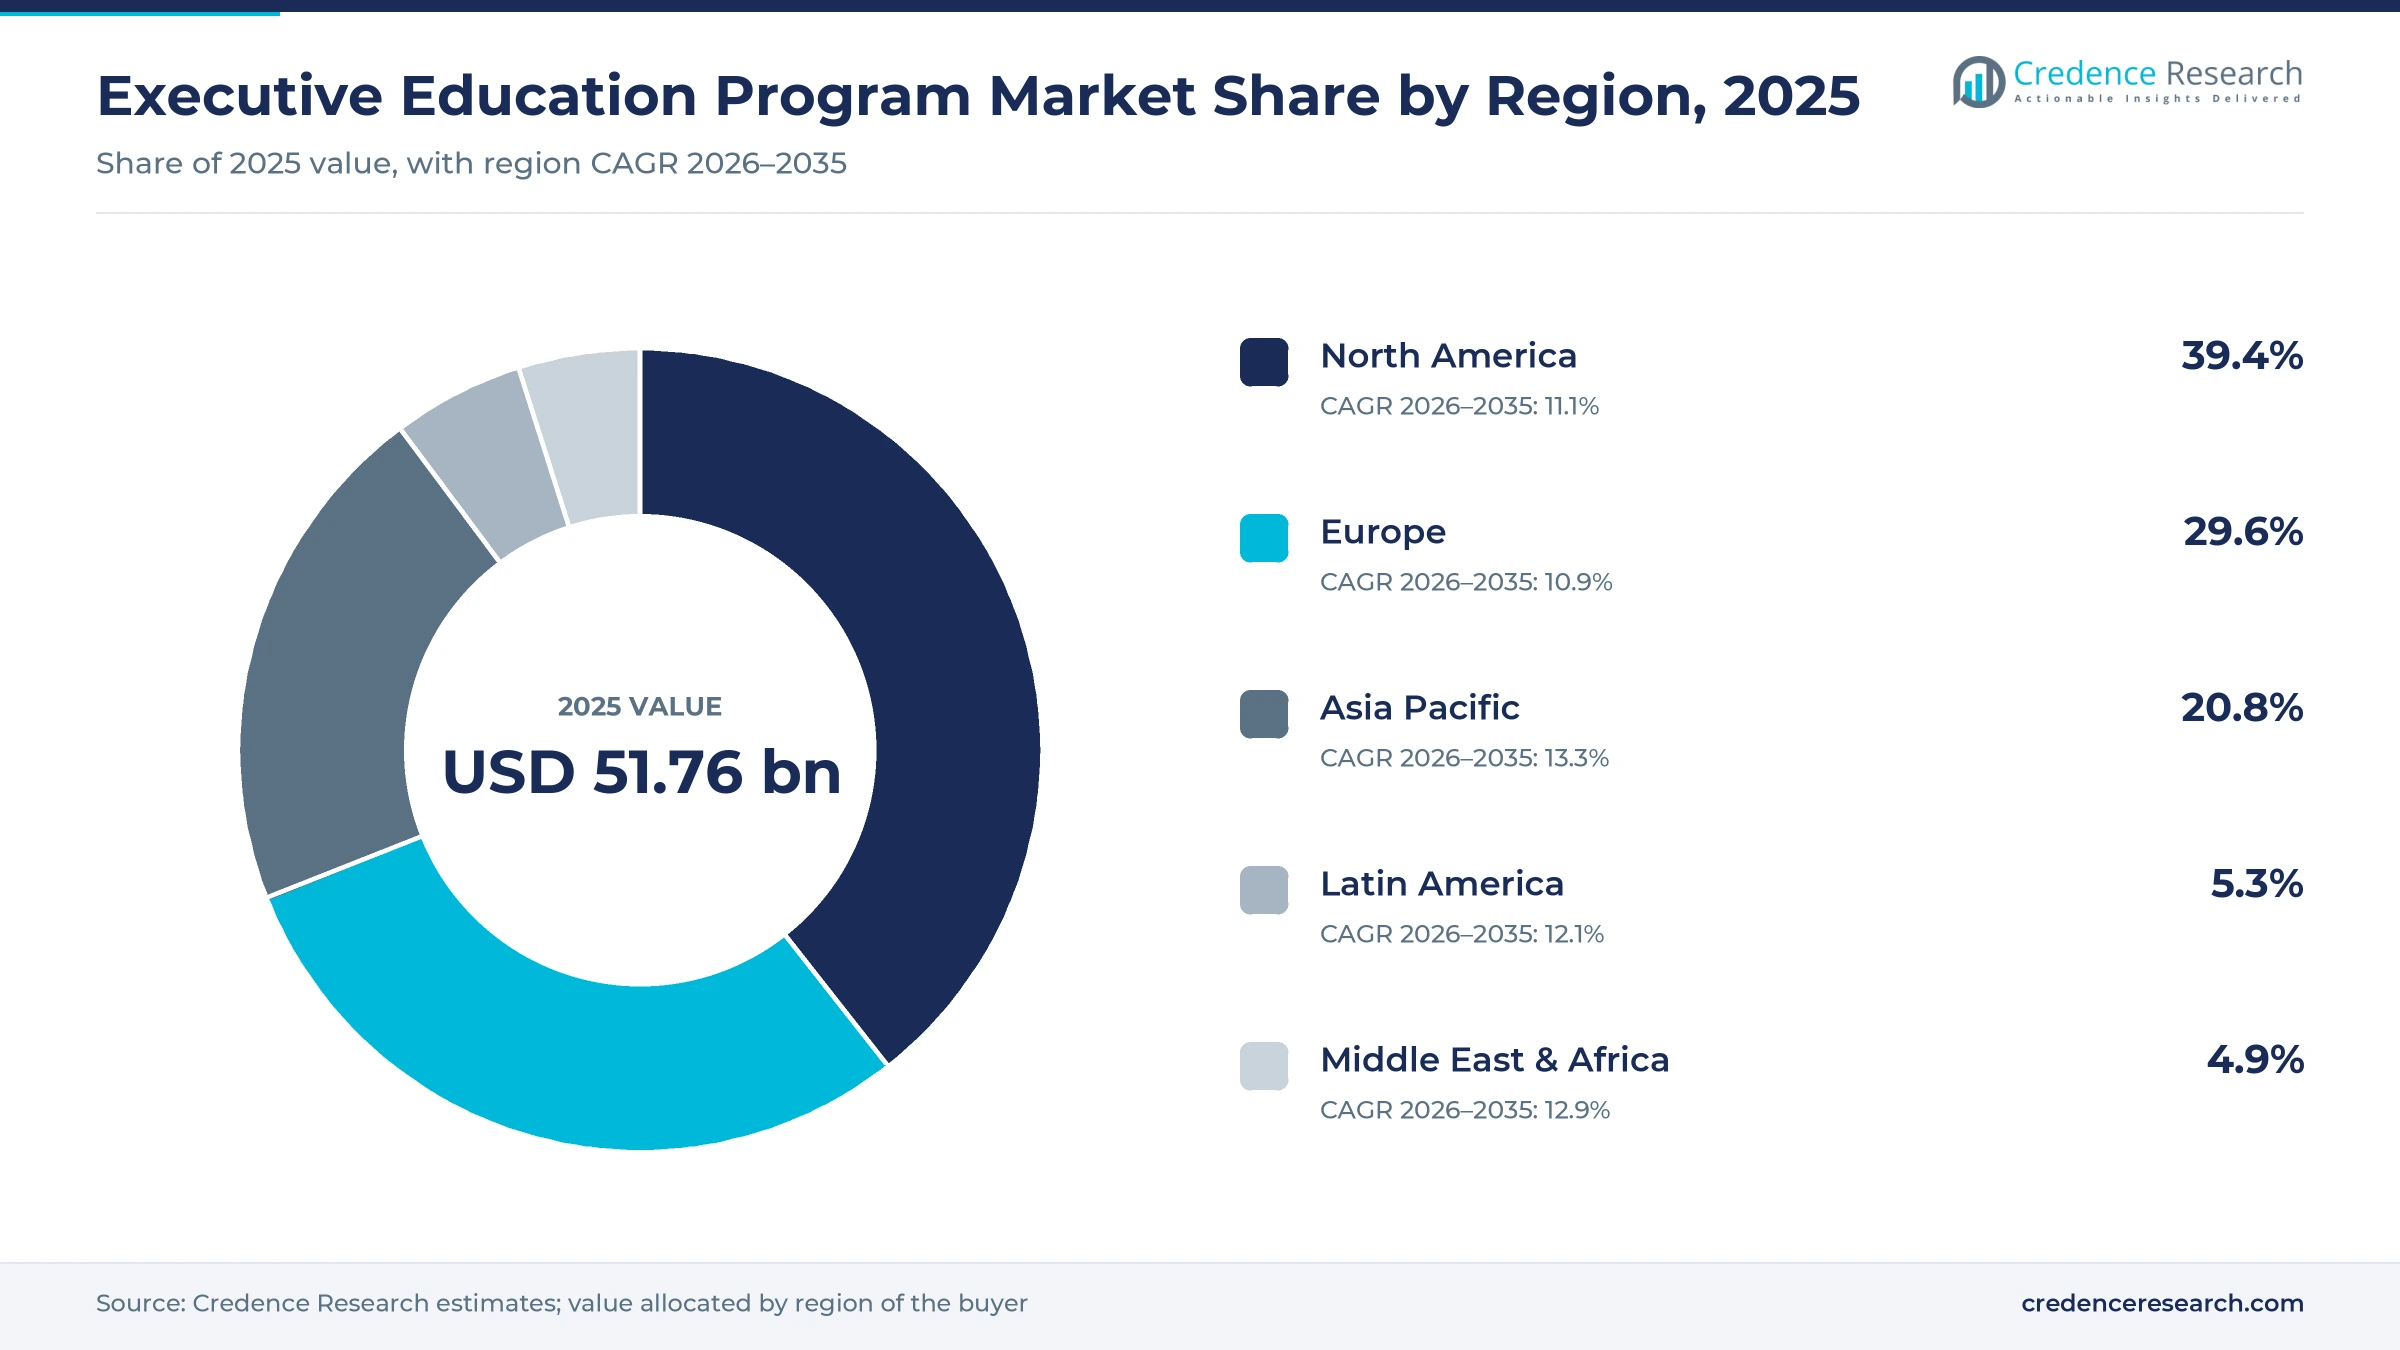
The global executive education program market was valued at USD 51.76 billion in 2025 and is projected to increase from USD 57.81 billion in 2026 to USD 156.49 billion by 2035, registering a CAGR of 11.70% during 2026–2035. Demand comes from employers that need senior managers fluent in AI, from sector bodies that commission their own cohorts, and from Gulf and Asian organizations building leadership benches. North America held the largest regional share, 39.4% in 2025, because large employers and long-established business schools concentrate there. Asia Pacific is the fastest-growing region at 13.3% a year, as online and blended formats open programs to leaders who cannot leave work for several weeks. Meanwhile, the supply side has changed sharply since Coursera completed its combination with Udemy in May 2026, adding scale to low-cost enterprise catalogs. Business schools are answering with AI curricula, shorter residential modules and new offices nearer to clients, while top fees still approach six figures.
What counts as an executive education program and who pays for it?
An executive education program is non-degree learning for working managers, business owners and senior leaders, delivered by business schools, universities, digital platforms and corporate training providers. This report counts customized programs built for one organization, pre-designed open-enrollment courses and certificates, and employer academy programs, including internal budgets for senior development as well as fees paid to outside providers, whether paid by the employer or by the participant.
Degree programs, including the Executive MBA, are excluded, as are general staff compliance training and consumer hobby courses. Value therefore reflects a broad definition of the field, which is wider than university-based provision alone. Buyers range from chief learning officers commissioning cohorts to individual managers paying for a certificate, so price points run from a few hundred dollars to several tens of thousands.
Executive Education Program Market Insights
- The market stood at USD 51.76 billion in 2025 and is expected to reach USD 156.49 billion by 2035, expanding at an 11.70% CAGR during 2026–2035.
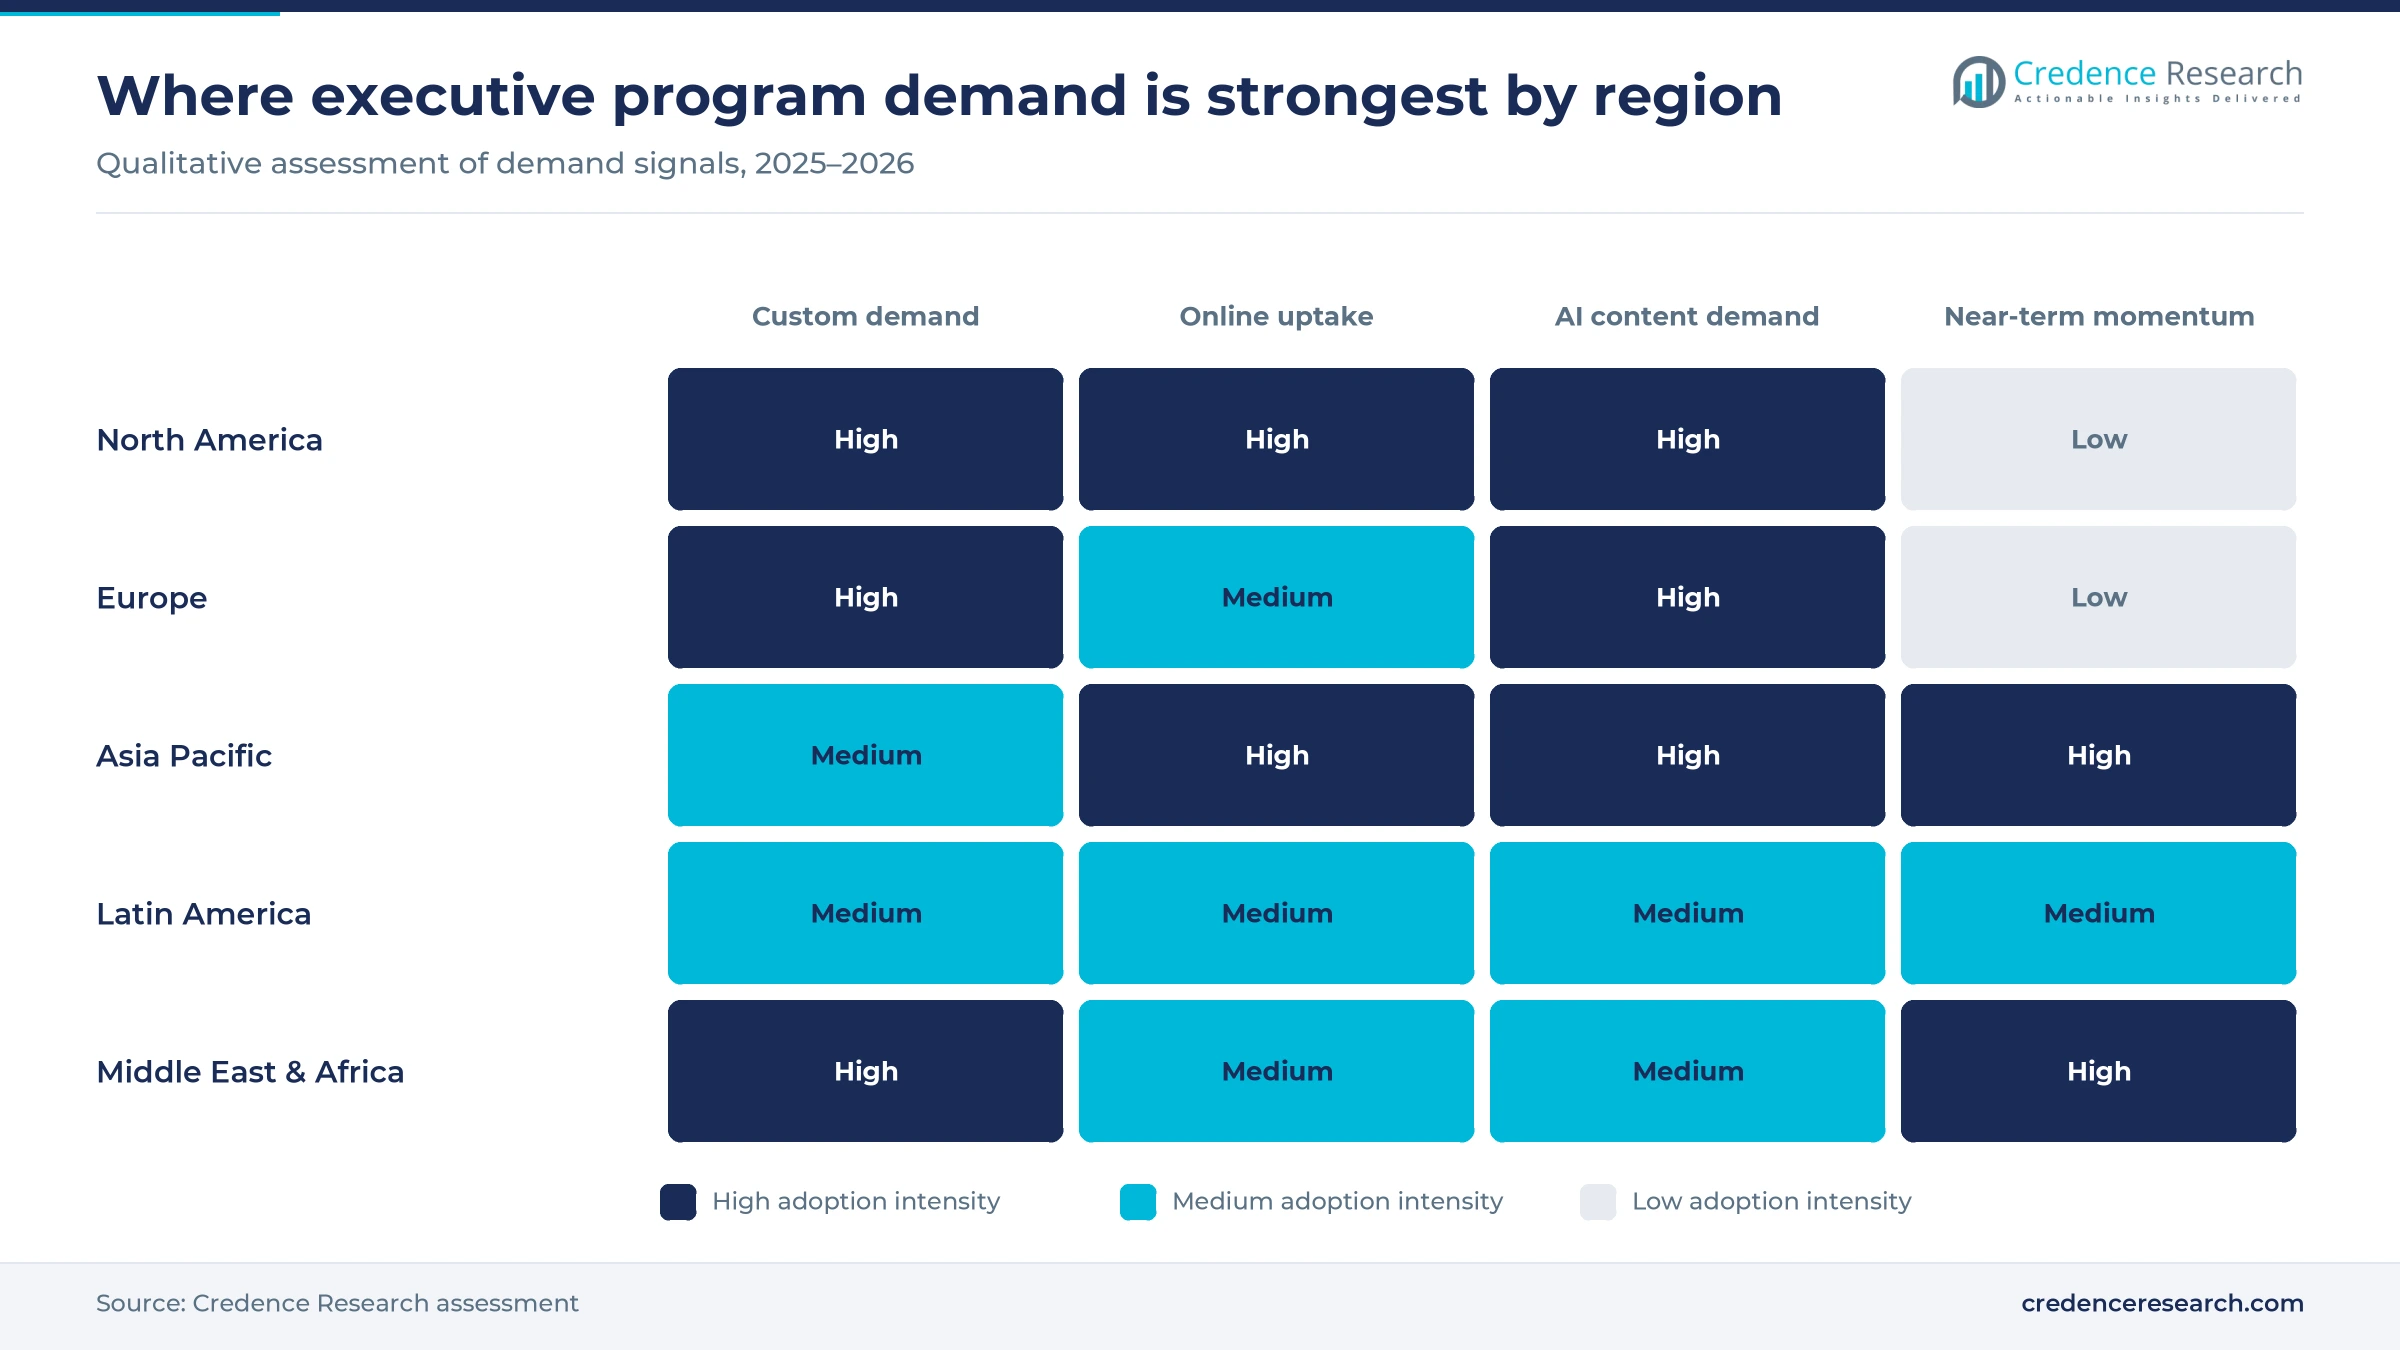
- North America held 39.4% of 2025 value, while Asia Pacific grows fastest at 13.3% a year as online and blended formats widen access.
- Customized Programs led with 58.0% of 2025 value, as UNICON members reported custom revenues rising nearly 15% in 2023-24.
- Three-quarters of open-enrollment courses now treat AI as a core element, according to a May 2026 Bluesky Thinking review of Financial Times rankings.
- Coursera completed its Udemy combination in May 2026 with 18,000 enterprise customers, raising pressure on school-led short courses at lower price points.
Custom briefs and senior leaders anchor program spending
Why bespoke executive education leads for high-potential talent
Based on program type, the market is categorized into customized programs and pre-designed programs. Customized Programs led with 58.0% of 2025 value because employers want cohorts built around their own strategy and high-potential talent. UNICON reported custom revenues rising nearly 15% in 2023-24, ahead of open programs at 13%. Customized Programs also grow fastest at 12.0% a year as sector bodies commission their own cohorts, and LIMRA and LOMA filled a Wharton AI Leadership Experience within two weeks in early 2026. Pre-designed courses keep their place with individuals, and Kellogg ran 72 open programs in 2025.
Senior executives carry the highest fees while owners add volume
Based on leadership level, the market is categorized into senior executives, managers, mid-level employees, business owners and junior and entry-level employees. Senior Executives led with 34.0% of 2025 value because flagship residential programs carry the highest prices, as Harvard Business School lists $95,000 for its Advanced Management Program and IESE lists 46,000 euros for its own. Business Owners grow fastest at 12.5% a year as subsidized routes widen access. According to the Initiative for a Competitive Inner City 2025 impact report, Goldman Sachs 10,000 Small Businesses has served more than 17,000 businesses through a 12-week program.
In-person delivery recovered as online certificates scale
Based on mode of learning, the market is categorized into in-person learning and online learning. In-Person Learning led with 56.0% of 2025 value because networking remains central to senior programs, and Poets&Quants cited a Unicon survey in June 2025 showing in-person attendance above 60% in 2023-24, well above the levels recorded during the pandemic years. Online Learning grows fastest at 12.8% a year from a low base, since Training magazine reported in November 2025 that executive development was the area least served online, at 48% of organizations. MIT xPRO added a 20-week online AI program for Indian leaders in 2026.
Financial firms lead sector buying while healthcare gains pace
Based on industry type, the market is categorized into financial services, technology and communications, professional services, healthcare and pharmaceuticals, manufacturing and industrials, consumer products and retail, energy and transportation, and others. Financial Services led with 24.0% of 2025 value because regulated firms need leaders who can govern AI, and MIT Sloan announced a two-day AI for Financial Services course on Jan. 7, 2026. Healthcare & Pharmaceuticals grows fastest at 12.6% a year as clinical leaders move into management roles. The American College of Healthcare Executives ran its 2025 Executive Program across three cities from June to November at $10,250 for members.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Program Type | Customized Programs | 58.0% | Customized Programs | 12.0% |
| By Leadership Level | Senior Executives | 34.0% | Business Owners | 12.5% |
| By Mode of Learning | In-Person Learning | 56.0% | Online Learning | 12.8% |
| By Industry Type | Financial Services | 24.0% | Healthcare & Pharmaceuticals | 12.6% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
AI, employer budgets and the Gulf lift program demand
Senior leaders need AI fluency they can apply at work
Employers now pay for senior AI literacy, and that need has become the clearest reason for new program spending. A May 2026 Bluesky Thinking review of the Financial Times rankings reported that three-quarters of open-enrollment courses treat AI as a core element. MIT Sloan Executive Education added five AI courses and a 10-day AI Executive Academy in its May 26, 2026 portfolio update. Wharton Online followed the same direction with Leading an AI-Powered Future, announced July 9, 2025, while Kellogg scheduled Mastering the Human-AI Partnership for October 2026. As a result, schools that once sold general strategy courses now compete on applied AI content, and executives can compare very similar offers before enrolling in any of them.
Employers are moving more training budget to outside providers
Outside providers are taking a larger part of employer learning budgets, which directly benefits schools and platforms selling to companies. Training magazine reported in November 2025 total training spending of $102.8 billion, up 4.9%, across United States corporate training budgets. The same report put spending on outside products and services at $16 billion, up 29%, and spending per learner at $874, up from $774 in 2024. Average training time fell to 40 hours per employee from 47, however, which favors short and modular formats over long residential courses. In turn, buyers are spending more per person on fewer hours, a pattern that suits focused senior programs with a clear business purpose and measurable workplace results.
Gulf and global clients widen the buyer base beyond home markets
International clients are widening the buyer base for established schools, especially in the Gulf. London Business School told Arab News in April 2025 that nearly one-third of its global executive education clients are Saudi individuals or companies, and that Saudi enrollment in open programs had risen more than 250% in recent years. The school responded by planning a Riyadh office for tailored programs serving public and private sector organizations. Poets&Quants reported in May 2026 that roughly 70% of Harvard Business School executive education participants come from outside the United States. Kellogg said in May 2026 that its learners came from more than 150 countries and that its Miami offerings had tripled, with a focus on Latin America, which shows how providers now follow clients abroad.
Sector bodies and employers commission bespoke cohorts
Custom executive education is growing because organizations want content tied to their own strategy and talent pipeline. UNICON, the consortium of more than 120 university-based providers, said in June 2025 that custom program revenues rose nearly 15% and open program revenues rose 13% in 2023-24. LIMRA and LOMA said on Feb. 20, 2026 that their Wharton AI Leadership Experience had registered 90 people from 39 companies, filling within two weeks of opening to members. Kellogg ran 92 custom engagements in 2025 and drew participants from roughly 350 Fortune 500 companies. UNICON also published a study in September 2025 of 200 global talent leaders, which found that 24% put alignment with business goals first when choosing a learning partner, a preference that favors tailored work.
Blended formats and platform mergers redraw the field
Shift toward blended programs with a residential core
Providers are settling on blended designs that keep a residential core and move the rest online. Poets&Quants cited Unicon data in June 2025 showing in-person attendance above 60% in 2023-24, which confirms that senior buyers still value time on campus. The LIMRA and LOMA program runs for six months, with a three-day session in Philadelphia in May, four virtual classes and a capstone from October 2026. Harvard Business School now describes its Advanced Management Program as blended, combining campus and virtual study, and Kellogg launched a self-paced Executive Education On-Demand platform. This shift is also visible in budgets, because programs now compete with leadership coaching for the same manager development funds.
Rise of larger platforms through mergers and restructuring
Platform consolidation is changing the lower-priced end of the field. Coursera completed its combination with Udemy in May 2026, after announcing it on Dec. 17, 2025, and the group reported 290 million learners and 18,000 enterprise customers. 2U, the owner of edX, emerged from Chapter 11 as a private company on Sept. 13, 2024, then expanded its Oxford Saïd partnership to nearly 40 programs on July 2, 2025. A UNICON recap from March 2026 noted that Emeritus works with more than 80 universities across several regions. Enterprise buyers increasingly compare those catalogs with content already licensed through learning management systems, which pushes schools to justify their premium with faculty access and peer networks.
Opening in affordable routes that widen access to business education
Lower-cost routes are the clearest opening for widening access to business education in academic institutions and beyond. Oxford Saïd and 2U launched open courses on edX in July 2025 at 149 pounds for about six hours of study, a price nearer to e-learning than to campus programs. Goldman Sachs 10,000 Small Businesses shows the scale subsidized models can reach, with more than 17,000 businesses served and activity in all 50 states, according to the Initiative for a Competitive Inner City. Kellogg ran 42 nonprofit programs in 2025, showing that schools can serve mission-driven leaders too. Schools that build a ladder from short courses to certificates can therefore recruit participants who could never fund a flagship program.
Opportunity in India and southeast Asia leadership programs
Asia offers a large opening for providers that localize content and price. MIT xPRO and Emeritus launched an AI Leadership and Data Strategy Program for India in May 2026, running 20 weeks online at 345,000 rupees plus tax for CXOs, senior directors and founders. That price and format show how a global brand can reach senior managers without requiring campus travel. INSEAD announced a three-day INSEAD for Impact forum on April 23, 2026, held at its Singapore campus in June. This opening carries weight because Asia Pacific is already the fastest-growing region in the model, and providers with local faculty, partners and pricing should capture a growing share of that demand.
Fees, volatility and visas test providers and buyers
Flagship fees put programs out of reach for many managers
Price remains the most visible barrier for managers without employer backing. Harvard Business School lists a fee of $95,000 for its Advanced Management Program, and IESE lists 46,000 euros for its equivalent course. Individuals and smaller companies therefore often cannot justify such programs, particularly when the return is hard to measure. Providers are responding with shorter modules, certificates and online versions, although cheaper formats can weaken the peer networks that attract senior participants to campus in the first place.
Market volatility has hit demand in the United States and Europe
Economic uncertainty quickly reaches discretionary leadership budgets, because companies can postpone senior programs. In a July 2025 UNICON pulse survey of 65 member schools, 85% said recent market volatility had directly affected their operations, and respondents reported significant demand declines in the United States and Europe. Providers relying on one home region are the most exposed to such swings. Many are therefore spreading risk through Gulf offices, cross-border delivery partners and online programs, although those moves take several years to pay back.
Visa barriers complicate programs built on international cohorts
Travel rules threaten the international mix that makes residential cohorts attractive to senior participants. AACSB reported in December 2025 that nearly eight in 10 schools in the Americas saw visa barriers as a challenge to attracting international students, against 49% in EMEA and 22% in Asia Pacific. That exposure matters for schools such as Harvard, where about 70% of executive participants come from abroad. In response, providers are adding overseas sites and virtual modules, which raise delivery costs and require careful quality control.
Patchy ranking data makes programs hard to compare
Buyers searching for the best executive education programs face incomplete comparisons, and that slows purchase decisions. Poets&Quants noted in June 2025 that Harvard, Wharton, Kellogg, MIT Sloan, Columbia and Stanford were absent from the Financial Times rankings because they did not submit the required data. As a result, some of the largest providers cannot be compared directly with ranked rivals on outcomes. Talent leaders therefore often rely on references and pilot cohorts, while schools must publish clearer evidence of workplace results.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 20.39 | 39.4% | 11.1% |
| Europe | 15.32 | 29.6% | 10.9% |
| Asia Pacific | 10.77 | 20.8% | 13.3% |
| Latin America | 2.74 | 5.3% | 12.1% |
| Middle East & Africa | 2.54 | 4.9% | 12.9% |
North America leads on employer budgets and school scale
North America held 39.4% of 2025 value and grows at 11.1% a year, the result of large employer budgets and deep school capacity. Training magazine put United States training spending at $102.8 billion in 2025, and Kellogg alone ran over 350 programs for about 16,000 participants that year. However, a May 2026 Bluesky Thinking review found that only Michigan Ross remained among United States schools in the Financial Times open-enrollment top 25, partly because many leading schools no longer submit data.
Europe combines ranking strength with uneven employer training
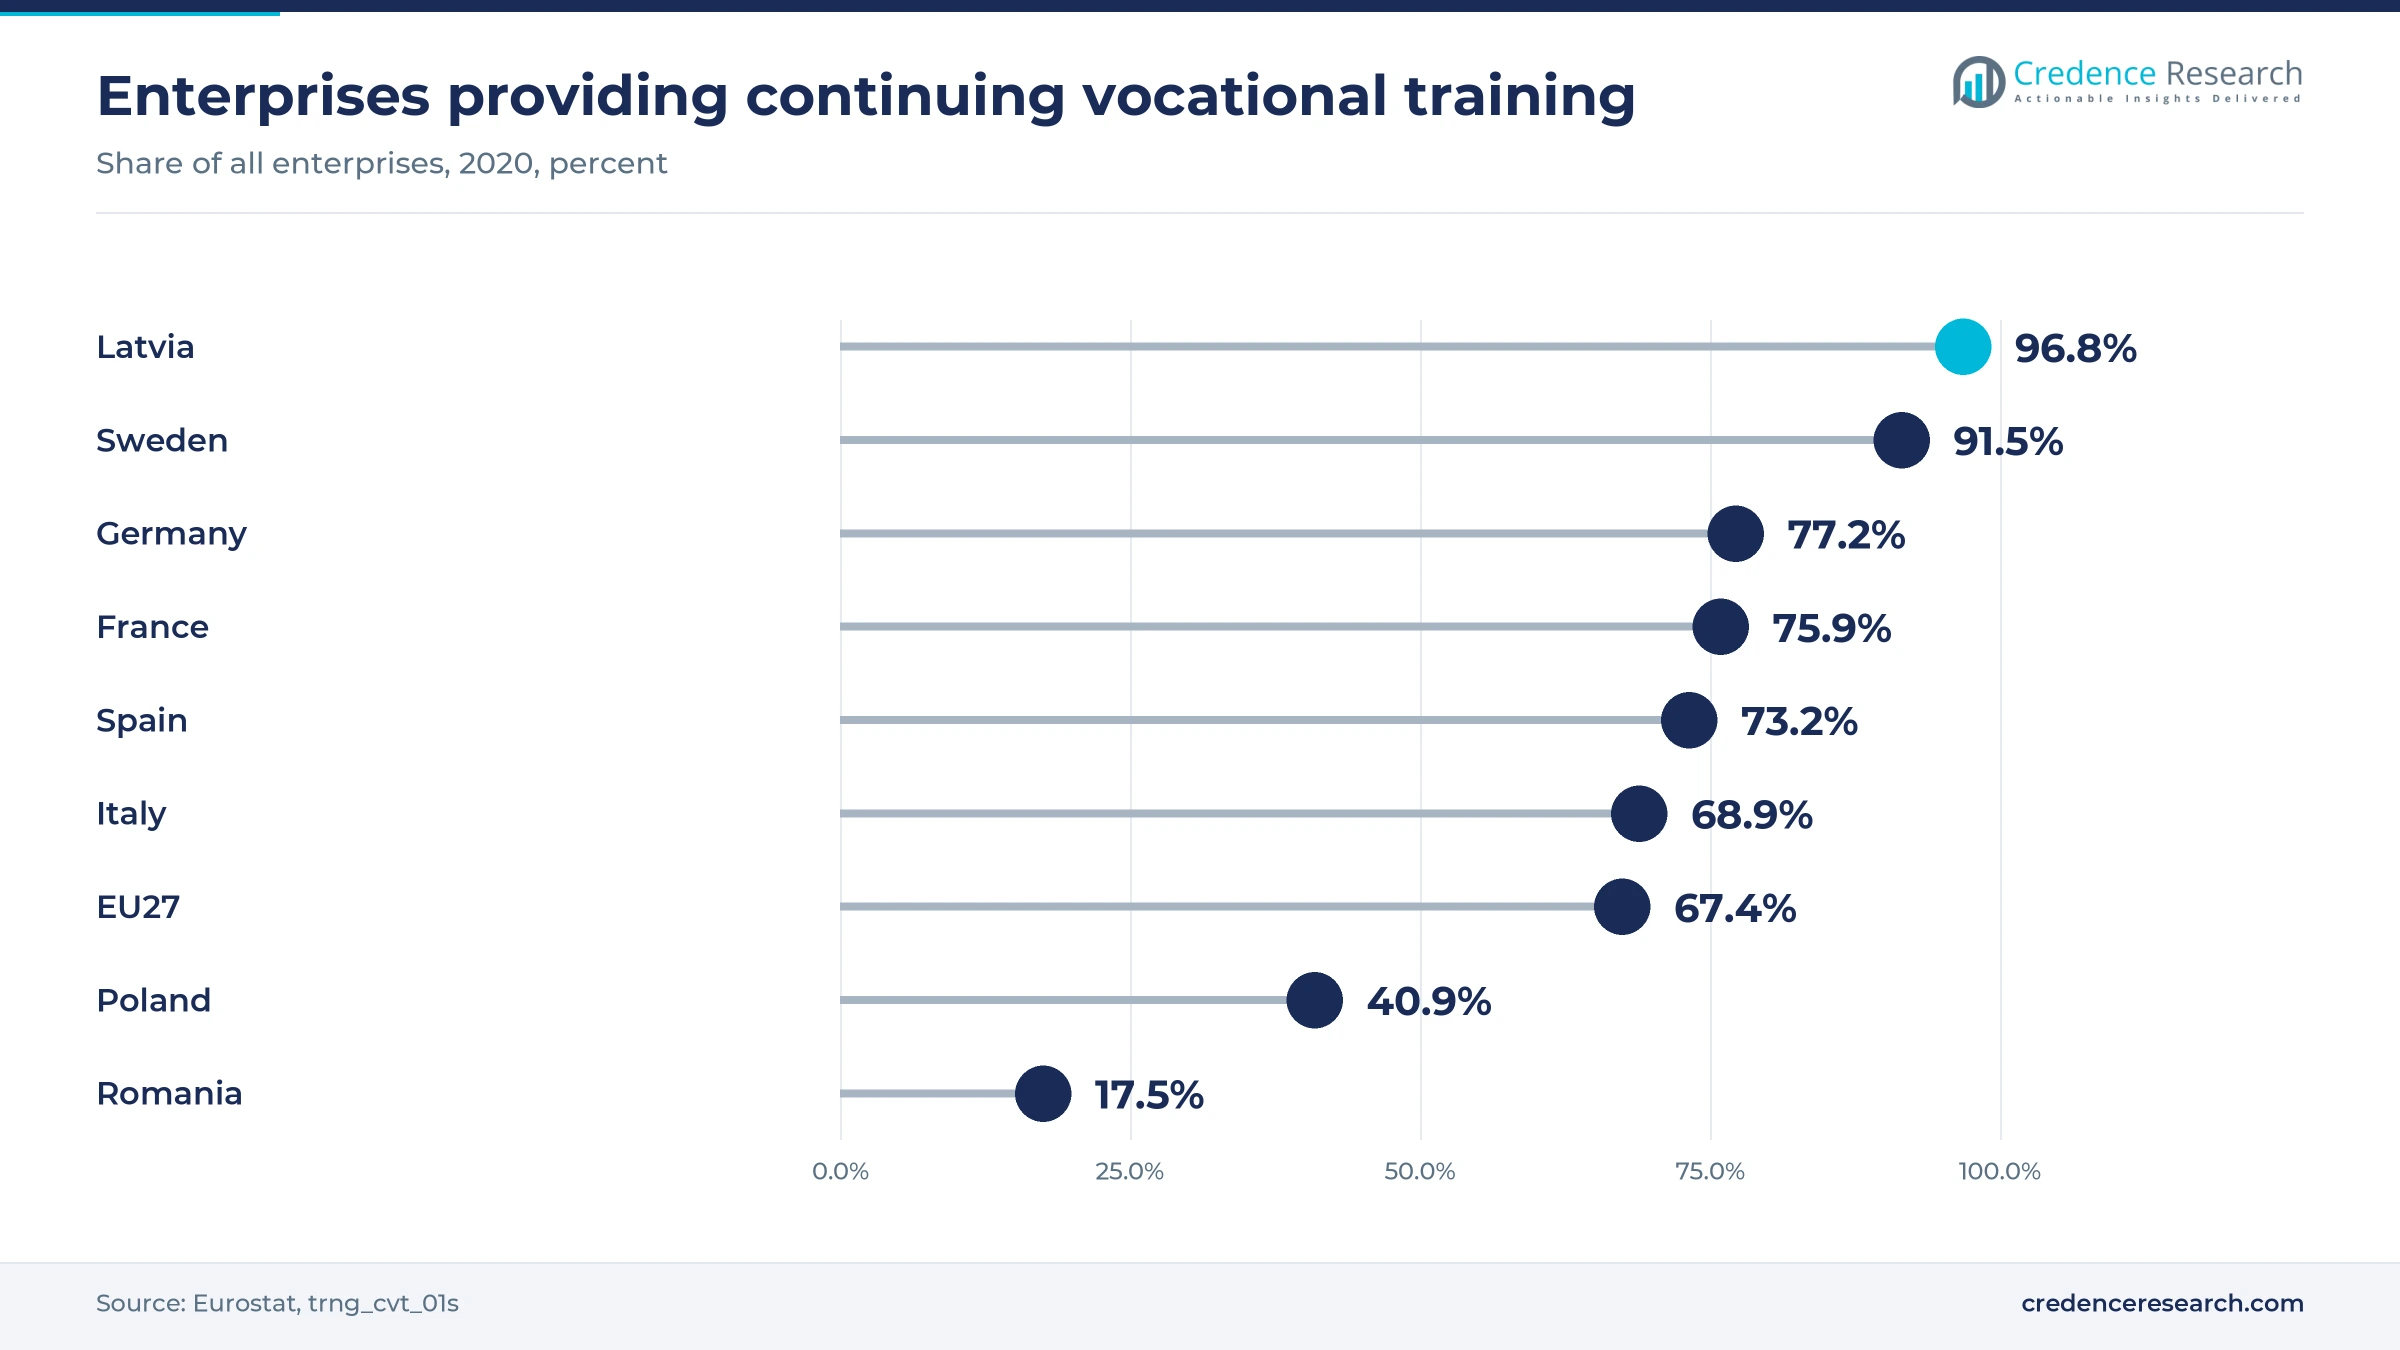
Europe held 29.6% of 2025 value and grows at 10.9% a year, supported by the strongest schools in the Financial Times tables. London Business School ranked first for open programs and SDA Bocconi first for custom programs in 2026. Eurostat data show the share of enterprises providing continuing vocational training in 2020 at 67.4% across the European Union, ranging from 96.8% in Latvia to 17.5% in Romania. That gap suggests clear room for growth, particularly among employers in the lowest-ranking member states.
Asia Pacific grows fastest on online and localized programs
Asia Pacific held 20.8% of 2025 value and grows fastest at 13.3% a year, because online formats reach managers across very large and dispersed markets. MIT xPRO and Emeritus priced their 2026 India AI program at 345,000 rupees plus tax for a 20-week course, well under campus fees. INSEAD used its Singapore campus for the INSEAD for Impact forum in June 2026, the 25th anniversary year of that campus, which shows how global schools are building regional hubs close to clients.
Latin America gains visibility through Brazilian schools
Latin America held 5.3% of 2025 value and grows at 12.1% a year, helped by strong regional schools that compete directly with global brands. A May 2026 Bluesky Thinking review counted 11 Latin American schools in the Financial Times custom top 100, with Fundação Dom Cabral fourth in the open ranking. Kellogg also said in May 2026 that its Miami offerings had tripled with a focus on Latin America, so regional clients now have more local and nearby options.
Middle East and Africa demand is led by Saudi clients
Middle East and Africa held 4.9% of 2025 value and grows at 12.9% a year, with Saudi organizations as the most visible buyers. London Business School told Arab News in April 2025 that it would open a Riyadh office, its second Middle East location after Dubai, citing Vision 2030 as a reason for the investment. UNICON pulse survey respondents also reported growing demand in the Middle East and Africa in July 2025, even while demand weakened in other regions.
Schools and platforms moved quickly on AI from 2024
| Development | Status and market relevance |
|---|---|
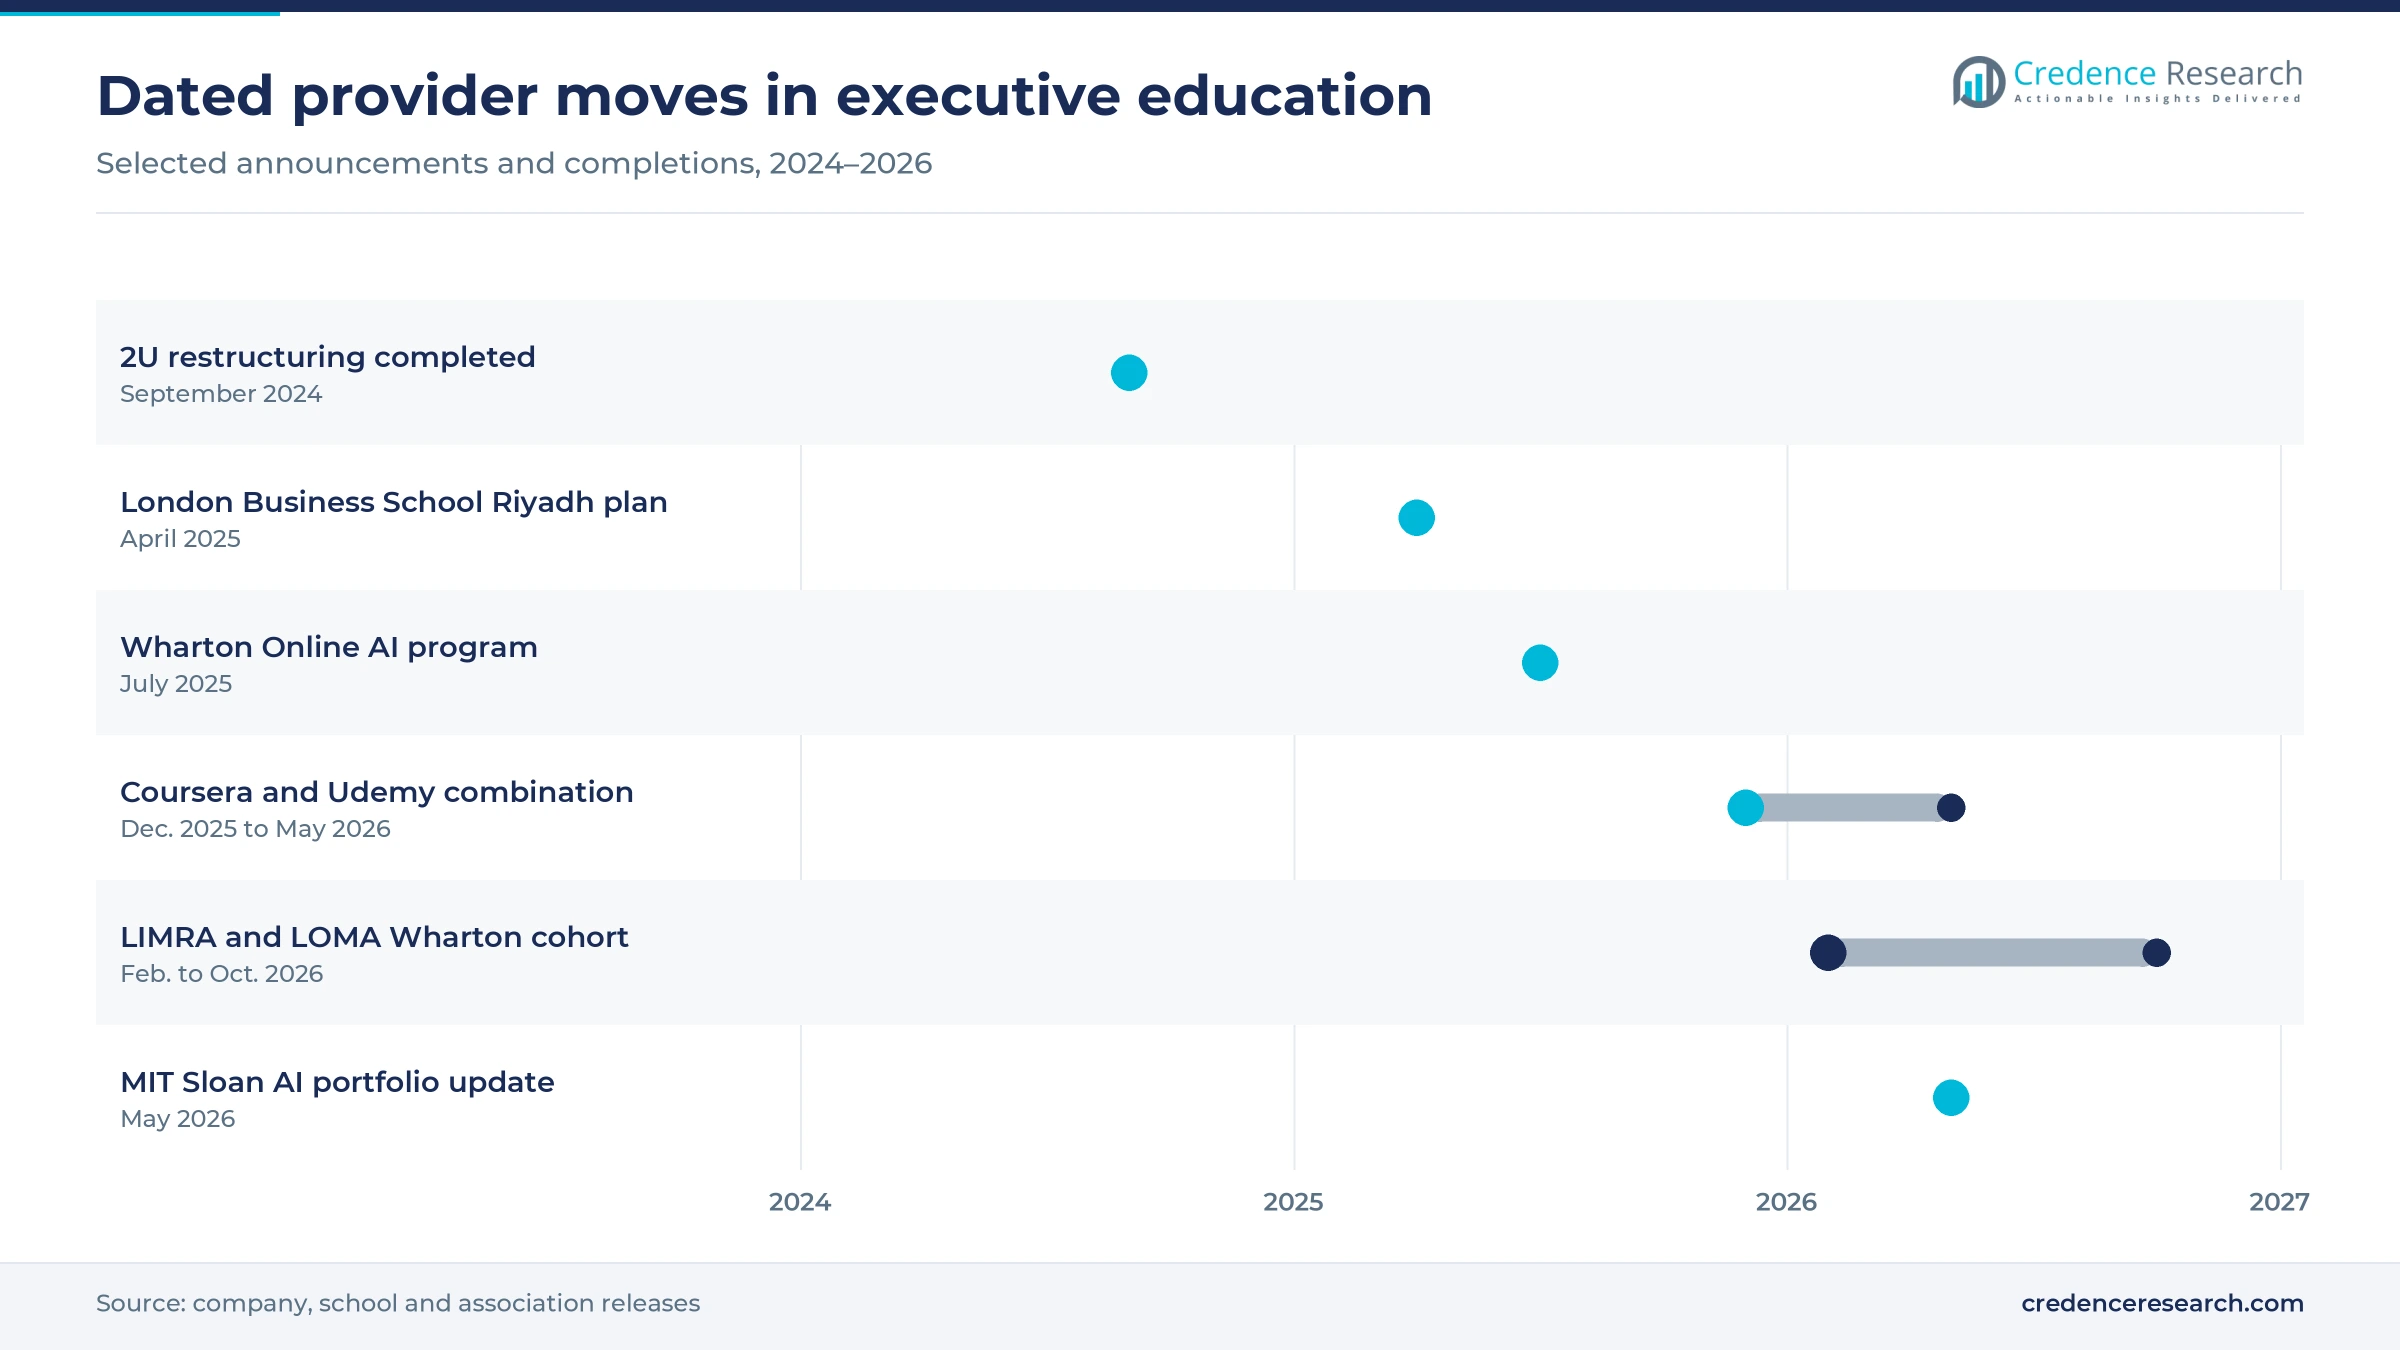
| In September 2024, 2U completed its financial restructuring, emerging from Chapter 11 as a private company with a new board. | Completed; edX remains its executive learning channel |
| In April 2025, London Business School said it would open a Riyadh office offering tailored programs to public and private clients. | Announced; expands Gulf delivery |
| In July 2025, 2U and Oxford Saïd launched a five-month AI-Driven Business Transformation Executive Programme on edX. | Launched; the partnership reached nearly 40 programs |
| In February 2026, LIMRA and LOMA announced the Wharton AI Leadership Experience, registering 90 people from 39 companies. | Running through October 2026 capstone; sector-commissioned cohort |
| In May 2026, Coursera completed its combination with Udemy, reporting 18,000 enterprise customers. | Completed; raises scale in enterprise catalogs |
Certificates and AI labs change how programs are built
- Agentic AI courses now appear in school catalogs, with MIT Sloan listing Agentic AI, Business Implications and Applications among its May 2026 additions.
- Stackable executive certificates let participants build credit over time, as with the MIT Sloan Advanced Certificate for Executives in AI and Digital Business.
- No-code AI labs give nontechnical leaders direct practice, and Kellogg has built them into its Mastering the Human-AI Partnership course from October 2026.
- Self-paced school platforms extend faculty content beyond the classroom, as seen with Kellogg Executive Education On-Demand and Wharton Online, which reports over one million total learners.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Rankings, brands and platform reach decide competition
Competition among providers runs on three distinct levels across the field. Elite schools such as Harvard Business School, Wharton, MIT Sloan and Kellogg sell brand and faculty, and Wharton says 100,000 professionals take its executive programs each year. Ranked European and Latin American schools, including London Business School, IMD, SDA Bocconi, IESE and Fundação Dom Cabral, use Financial Times placings to win custom clients, and IMD topped the 2025 custom table before SDA Bocconi took first place in 2026. Platforms form the third level, because Coursera, 2U and Emeritus sell scale, lower prices and university partnerships to employers. Schools are also moving nearer to clients, with London Business School in Riyadh and Dubai and INSEAD in Singapore, while platforms are consolidating. As a result, mid-tier schools without a strong ranking or a sector specialty face the sharpest pressure on both price and enrollment.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| London Business School | Business school | First in the Financial Times open ranking in 2025 and 2026; Riyadh and Dubai presence |
| IMD | Business school | First in the 2025 Financial Times custom ranking; custom programs for corporate clients |
| SDA Bocconi | Business school | First in the 2026 Financial Times custom ranking |
| Harvard Business School | Business school | Advanced Management Program at $95,000; about 70% of participants from abroad |
| Wharton School | Business school | Serves 100,000 professionals a year; delivers the LIMRA and LOMA AI cohort |
| MIT Sloan School of Management | Business school | More than 90 short courses and a 10-day AI Executive Academy |
| Kellogg School of Management | Business school | About 16,000 participants in 2025 across custom, open and online formats |
| INSEAD | Business school | Singapore campus hosting the INSEAD for Impact forum in June 2026 |
| Fundação Dom Cabral | Business school | Fourth in the 2026 Financial Times open ranking; Latin American leader |
| Coursera | Digital platform | Combined with Udemy in May 2026; 18,000 enterprise customers |
| 2U (edX) | Digital platform | Oxford Saïd partnership of nearly 40 programs; private since September 2024 |
| Emeritus | Digital platform | Runs university-branded programs, including the MIT xPRO India AI course |
Credence Research view on custom and AI spending
Credence Research's view is that custom work and AI content will decide who gains share through 2035. The broad scope of this market means that its headline value includes much more than university programs, so buyers should read it as spending on senior development generally. Credence Research also sees near-term softness in the United States and Europe, as UNICON recorded in July 2025, as a real test rather than a pause. Providers with clients in the Gulf and Asia, or a clear sector specialty such as insurance or healthcare, look best placed, while general open-enrollment catalogs face direct pressure from cheaper platforms.
How this executive learning estimate was built
The report uses 2025 as the base year, 2026 as the first forecast year and 2035 as the final forecast year. Market values come from the Credence Research model, which rolls the earlier published estimate forward and tests it against public data on training budgets and provider activity. Segment and regional splits in this report are Credence Research estimates built from those inputs. Sources are school and consortium publications, trade press, company releases and official statistics such as Eurostat. No interviews or primary surveys were conducted by the firm for this edition.
Outlook favors programs that prove workplace results
Spending should keep rising through 2035, reaching USD 156.49 billion at an 11.70% CAGR, although growth will not be even across providers or regions. Employers are likely to want shorter, sector-specific and AI-informed cohorts with evidence of workplace results, which favors schools that can design custom work at speed. Platforms should keep gaining at the lower end, particularly after the Coursera and Udemy combination. Meanwhile, Asia Pacific and the Gulf should add the most new buyers, and providers that combine local delivery, credible faculty and clear outcome data will be best placed to win them over the period.
Frequently Asked Questions
What is the executive education market size?
Which are the best executive education programs in 2026?
What are the benefits of executive education for career growth?
Are executive education programs worth it?
What is bespoke executive education for high-potential talent?
How can access to business education be improved?
Which region leads the executive education program market?
Who are the main executive education providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Program Type
- 1.2.1 Customized Programs
- 1.2.2 Pre-designed Programs
- 1.3 By Leadership Level
- 1.3.1 Senior Executives
- 1.3.2 Managers
- 1.3.3 Mid-level Employees
- 1.3.4 Business Owners
- 1.3.5 Junior and Entry-level Employees
- 1.4 By Mode of Learning
- 1.4.1 In-Person Learning
- 1.4.2 Online Learning
- 1.5 By Industry Type
- 1.5.1 Financial Services
- 1.5.2 Technology & Communications
- 1.5.3 Professional Services
- 1.5.4 Healthcare & Pharmaceuticals
- 1.5.5 Manufacturing & Industrials
- 1.5.6 Consumer Products & Retail
- 1.5.7 Energy & Transportation
- 1.5.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 51.76 billion → 2035: USD 156.49 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Executive Education Program Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Executive Education Program Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Executive Education Program Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Executive Education Program Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Executive Education Program Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Executive Education Program Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Executive Education Program Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Executive Education Program Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 51.76 billion → 2035: USD 156.49 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Executive Education Program Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Program Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Customized Programs
- 12.3.7.2 Pre-designed Programs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Leadership Level - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Senior Executives
- 12.4.7.2 Managers
- 12.4.7.3 Mid-level Employees
- 12.4.7.4 Business Owners
- 12.4.7.5 Junior and Entry-level Employees
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mode of Learning - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 In-Person Learning
- 12.5.7.2 Online Learning
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Type - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Financial Services
- 12.6.7.2 Technology & Communications
- 12.6.7.3 Professional Services
- 12.6.7.4 Healthcare & Pharmaceuticals
- 12.6.7.5 Manufacturing & Industrials
- 12.6.7.6 Consumer Products & Retail
- 12.6.7.7 Energy & Transportation
- 12.6.7.8 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Executive Education Program End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Executive Education Program Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Executive Education Program Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Executive Education Program Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 London Business School
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 IMD
- 18.4 SDA Bocconi
- 18.5 Harvard Business School
- 18.6 Wharton School
- 18.7 MIT Sloan School of Management
- 18.8 Kellogg School of Management
- 18.9 INSEAD
- 18.10 Fundação Dom Cabral
- 18.11 Coursera
- 18.12 2U (edX)
- 18.13 Emeritus
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

