
Market Overview:
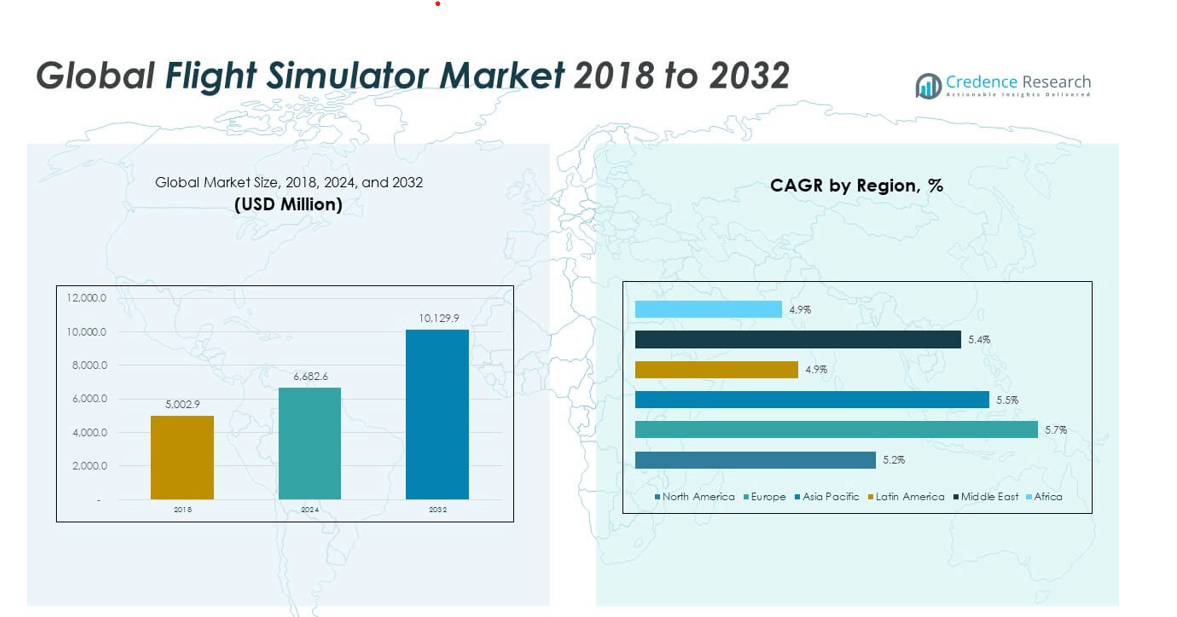
The Global Flight Simulator Market size was valued at USD 5,002.9 million in 2018, reaching USD 6,682.6 million in 2024, and is anticipated to attain USD 10,129.9 million by 2032, growing at a CAGR of 5.37% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Flight Simulator Market Size 2024 | USD 6,682.6 million |
| Flight Simulator Market, CAGR | 5.73% |
| Flight Simulator Market Size 2032 | USD 10,129.9 million |
The market growth is driven by rising demand for pilot training and the growing emphasis on flight safety. Increasing aircraft deliveries, the expansion of the aviation industry, and cost-effective simulation-based training programs are further supporting market growth. Advancements in virtual reality, motion sensors, and AI-based simulation technologies are enhancing training accuracy, reducing operational risks, and improving the overall efficiency of pilot instruction.
North America leads the market due to its strong aviation infrastructure and presence of major simulator manufacturers. Europe follows closely, supported by stringent pilot training regulations and high adoption rates in commercial aviation. Asia Pacific is emerging rapidly, driven by expanding airline fleets, rising passenger traffic, and the need for skilled pilots in nations like China, India, and Japan. Other regions are also adopting simulation solutions to enhance flight safety and reduce training costs
Market Insights:
- The Global Flight Simulator Market size was valued at USD 5,002.9 million in 2018, reached USD 6,682.6 million in 2024, and is projected to attain USD 10,129.9 million by 2032, growing at a CAGR of 5.37% during the forecast period.
- North America (32.1%), Asia Pacific (26.9%), and Europe (25.7%) collectively account for over 84% of the total market share, driven by advanced aviation infrastructure, strong regulatory frameworks, and high simulator adoption for both commercial and defense training.
- Asia Pacific is the fastest-growing region, holding 9% share, supported by expanding airline fleets, rapid air traffic growth, and rising investments in pilot training centers across China, India, and Japan.
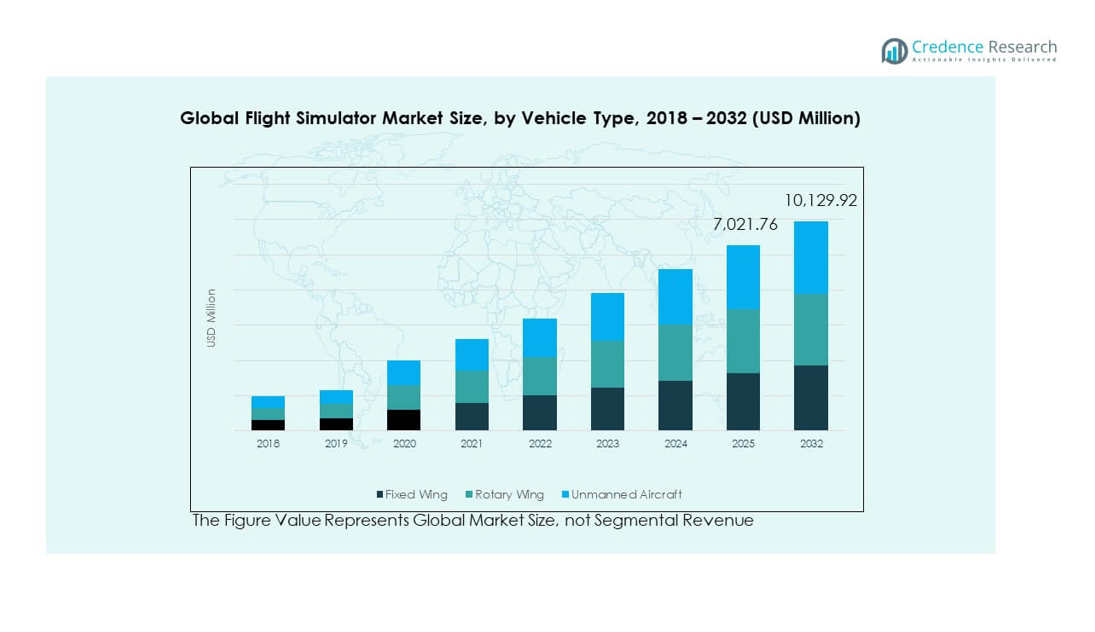
- By vehicle type, Fixed Wing simulators dominate the market, accounting for approximately 47% share, due to their widespread use in commercial aviation training programs.
- Rotary Wing and Unmanned Aircraft simulators collectively capture about 53% share, reflecting the growing adoption of helicopter and drone simulation for defense, logistics, and emergency response applications.
Market Drivers:
Rising Global Demand for Pilot Training and Aviation Safety Standards
The Global Flight Simulator Market is expanding due to the growing need for efficient pilot training programs worldwide. The rise in commercial and military aircraft fleets has increased the requirement for skilled pilots. Simulation-based training provides a safer and more cost-effective way to develop flight skills. It helps pilots handle complex flight conditions without operational risks. The increasing focus on safety regulations by aviation authorities is further accelerating simulator adoption. Airlines are investing heavily in advanced simulators to ensure regulatory compliance. Enhanced realism in simulation training is helping reduce human error in actual flight operations. The market continues to grow as pilot shortage challenges drive training investments globally.
- For instance, in October 2025, CAE Inc. secured an agreement to deliver a Boeing 737MAX full-flight simulator to MAB Academy, featuring the CAE Prodigy Image Generator, which supports the highest level of regulatory-certifiable flight training for major global airlines and is scheduled to be operational by July 2026.
Technological Advancements in Simulation Hardware and Software Systems
Continuous innovation in flight simulation technology is transforming pilot training quality. The integration of AI, virtual reality, and motion capture systems enhances immersion and training precision. These advancements allow realistic replication of flight dynamics and cockpit experiences. The Global Flight Simulator Market benefits from improved visual fidelity and motion accuracy. Modern simulators can now mimic multiple aircraft types, improving operational flexibility. The inclusion of cloud connectivity supports remote training capabilities. It also enables consistent data monitoring for performance evaluation. The adoption of next-generation software is optimizing simulator maintenance and lifecycle costs.
- For instance, Indra Sistemas launched its NEXUS fighter simulator in June 2025, which provides 8K ultra-high-resolution visuals, immersive cave environments, and connectivity for joint tactical exercises across multiple operator stations, advancing the technological ceiling for tactical pilot training.
Growth in Commercial Aviation and Aircraft Deliveries Worldwide
Rising air travel demand and new aircraft deliveries are fueling simulator requirements. Commercial airlines are increasing their investments in training centers to meet regulatory standards. The Global Flight Simulator Market supports cost-efficient pilot certification and recurrent training. It helps reduce dependence on actual flight hours, lowering operational costs. The rise in low-cost carriers across emerging economies has expanded training demand. Flight simulators provide scalable training models suited for diverse aircraft fleets. Growing air traffic management complexity also boosts simulator relevance. The expansion of fleet modernization programs ensures sustained demand for training devices.
Military Modernization and Increased Defense Spending for Pilot Training
Defense forces across major economies are investing in simulation systems to enhance operational readiness. Advanced simulators allow military pilots to practice complex combat and mission scenarios. The Global Flight Simulator Market benefits from rising defense modernization budgets. It provides training solutions for fighter jets, helicopters, and UAVs. Governments prefer simulation-based modules to reduce fuel costs and aircraft wear. These systems support frequent drills and tactical mission planning without risk. The integration of AR and mixed reality enhances real-time situational awareness. The shift toward next-generation aircraft platforms further drives simulator procurement in defense programs.
Market Trends:
Integration of Artificial Intelligence and Data Analytics in Training Modules
Artificial intelligence is redefining simulation systems by enabling personalized pilot training. AI-driven simulators analyze performance data to identify learning gaps and suggest improvements. It enhances operational efficiency by creating adaptive training programs for each trainee. The Global Flight Simulator Market is adopting analytics-based systems to monitor skill progression. Data-driven insights improve decision-making for both instructors and regulators. Predictive analytics also aid in scheduling maintenance and minimizing downtime. Machine learning integration supports error prediction during virtual flight sessions. This trend enhances training quality while reducing operational risks across civil and defense sectors.
Expansion of Cloud-Based and Remote Training Platforms
The growing adoption of cloud technology is transforming simulator accessibility. Remote simulator operation allows flexible pilot training schedules across locations. The Global Flight Simulator Market is witnessing a rise in web-based interfaces and hybrid setups. These systems reduce infrastructure costs for flight academies and airlines. Cloud platforms ensure centralized data storage and synchronization across multiple simulators. It enables real-time performance monitoring and progress assessment. Remote connectivity supports instructor-led virtual sessions for continuous learning. This trend improves scalability for commercial and defense aviation training centers.
- For instance, in September 2025, FlightSafety International expanded its VITAL MR mixed-reality platform to over 30 certified training centers, enabling remote session management, real-time monitoring, and central data access for thousands of pilots each quarter.
Increasing Use of Virtual and Mixed Reality in Simulation Environments
Virtual and mixed reality technologies are improving simulation realism. These technologies enable immersive cockpit experiences that replicate real-world conditions. The Global Flight Simulator Market is leveraging VR to enhance pilot engagement during training. Head-mounted displays and haptic feedback systems improve situational awareness. Simulators now integrate spatial audio and 3D visualization for realistic interaction. The enhanced sensory experience strengthens pilot reflexes and crisis management skills. VR-based simulators are also gaining traction in academic institutions. This trend is reshaping conventional flight training approaches with interactive and cost-efficient solutions.
Collaborations and Mergers to Develop Advanced Simulator Solutions
Leading companies are forming strategic alliances to innovate and expand simulator portfolios. Partnerships between OEMs, airlines, and training centers foster technology integration. The Global Flight Simulator Market benefits from collaborations that align research and development efforts. These ventures accelerate the production of high-fidelity simulators for diverse aircraft types. Mergers strengthen product distribution and after-sales support globally. Joint development programs help standardize training systems across regions. It ensures simulator interoperability and cross-platform compatibility. These partnerships also encourage regulatory alignment and enhance global training infrastructure.
Market Challenges Analysis:
High Initial Investment and Maintenance Cost Limiting Adoption
The Global Flight Simulator Market faces significant cost-related constraints. High initial investment requirements for full flight simulators restrict access for smaller training academies. Maintenance and system upgrades add continuous financial pressure on operators. The complex hardware setup demands specialized technicians and calibration tools. It often leads to extended downtime and higher operational expenses. Budget limitations in developing economies further slow down simulator adoption. Many training institutes rely on used or outdated equipment to manage costs. These challenges hinder scalability and restrict widespread deployment. The market must balance technological advancement with affordability to sustain growth.
Regulatory Complexities and Limited Availability of Skilled Instructors
Regulatory differences among countries complicate simulator certification and approval processes. Each region has distinct training standards and compliance norms, delaying deployment timelines. The Global Flight Simulator Market is also impacted by a shortage of qualified simulation instructors. Training programs require experienced pilots who can accurately interpret simulator data. The lack of uniform regulations raises certification costs for manufacturers. Delayed approval cycles slow down fleet-wide training adoption for airlines. Skill shortages lead to inconsistent training quality and reduced simulator utilization. Addressing these regulatory and human resource gaps remains crucial for market expansion.
Market Opportunities:
Growing Demand for Next-Generation Aircraft and Pilot Recurrent Training
The increasing production of modern aircraft is creating new opportunities for simulator manufacturers. The Global Flight Simulator Market is expected to benefit from mandatory pilot recertification and ongoing training. Airlines are investing in simulator-based programs to ensure proficiency in advanced avionics. Expanding global air traffic will further drive training demand. Many operators seek cost-efficient and environmentally friendly training methods. Simulators meet both needs by minimizing fuel use and reducing carbon emissions. The need for tailored training systems for electric and hybrid aircraft adds further growth prospects.
Rising Adoption of Simulation for Urban Air Mobility and Drone Operations
Emerging urban air mobility and drone segments are opening new revenue streams. The Global Flight Simulator Market is witnessing interest in UAM-specific and UAV simulators. These systems help operators train for vertical take-off, air traffic coordination, and emergency protocols. Governments are supporting research for autonomous flight simulation. Simulator vendors are diversifying into these segments to expand their portfolios. Growing investments in smart city and defense drone programs amplify the demand. The evolving air mobility ecosystem ensures strong long-term growth opportunities for simulator developers.
Market Segmentation Analysis:
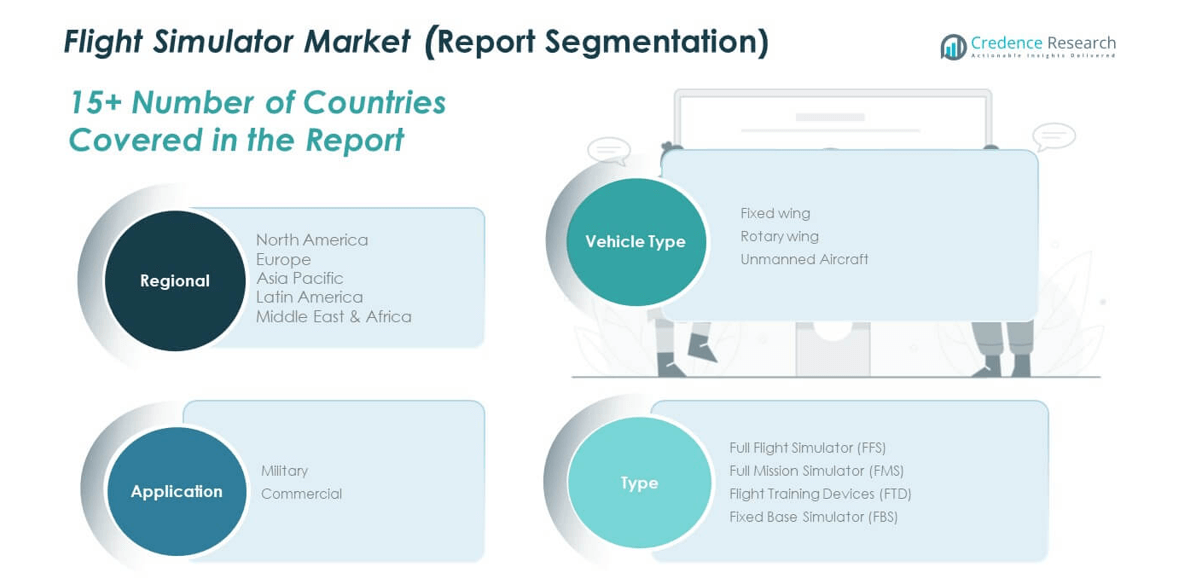
By Vehicle Type
The Global Flight Simulator Market is divided into fixed wing, rotary wing, and unmanned aircraft simulators. Fixed wing simulators hold the largest share due to their use in commercial and military pilot training. Rotary wing simulators are gaining traction with the growth of helicopter operations in defense and emergency services. Unmanned aircraft simulators are emerging fast as drone adoption expands across surveillance, logistics, and defense sectors. It supports flight mission planning, navigation training, and complex operational rehearsals for unmanned systems.
- For instance, In May 2023, Thales SA and Simaero signed a contract to relocate an H225 Reality H® Level D full-flight helicopter simulator to serve China Sky-Wings in Shanghai. This relocation project was carried out by Simaero's engineering team. The new simulator allows for advanced helicopter mission training for pilots in a center certified to the highest simulation standards.
By Application
The market is segmented into military and commercial applications. The military segment dominates due to high defense spending and increased focus on mission readiness. It benefits from advanced training programs for fighter jets, helicopters, and UAVs. The commercial segment is growing with the rise in air passenger traffic and airline expansion. Simulators help reduce fuel consumption and operational costs during pilot training. Training institutions and airlines continue investing in simulator infrastructure to meet global pilot certification requirements.
- For instance, in October 2025, VirTra demonstrated its Soldier Virtual Training (SVT) system to U.S. Army PEO STRI, providing advanced ballistic and joint fires simulation in portable systems, while Boeing reported that its 2025 simulator upgrades supported over 2,000 device configurations for large airline fleets worldwide.
By Type
The market includes Full Flight Simulator (FFS), Full Mission Simulator (FMS), Flight Training Devices (FTD), and Fixed Base Simulator (FBS). Full Flight Simulators account for the largest share due to their high realism and regulatory recognition for pilot licensing. Full Mission Simulators are preferred for defense applications to replicate combat and tactical scenarios. Flight Training Devices and Fixed Base Simulators support procedural and initial training stages. Each type addresses specific operational and training needs across civil and defense aviation segments.
Segmentation:
By Vehicle Type:
- Fixed Wing
- Rotary Wing
- Unmanned Aircraft
By Application:
- Military
- Commercial
By Type:
- Full Flight Simulator (FFS)
- Full Mission Simulator (FMS)
- Flight Training Devices (FTD)
- Fixed Base Simulator (FBS)
By Region:
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Flight Simulator Market size was valued at USD 1,651.95 million in 2018, reaching USD 2,179.97 million in 2024, and is anticipated to attain USD 3,250.69 million by 2032, at a CAGR of 5.2% during the forecast period. North America accounts for 32.1% of the total Global Flight Simulator Market share. The region leads due to advanced aviation infrastructure and the presence of key simulator manufacturers. The U.S. dominates the market, driven by high investments in military aviation training and civil pilot programs. Continuous demand from commercial airlines for recurrent pilot certification boosts simulator adoption. Strong regulatory standards by the FAA support simulator-based training across fleets. Canada contributes through its expanding flight schools and defense training facilities. It benefits from technological integration in simulator software and hardware systems, enhancing operational precision and safety outcomes.
Europe
The Europe Flight Simulator Market size was valued at USD 1,239.72 million in 2018, reaching USD 1,684.59 million in 2024, and is anticipated to attain USD 2,611.49 million by 2032, at a CAGR of 5.7% during the forecast period. Europe holds 25.7% of the total Global Flight Simulator Market share. The region’s dominance is supported by strong aviation regulation and an expanding network of airline training centers. The UK, Germany, and France remain major contributors to simulator production and export. The European Union Aviation Safety Agency (EASA) enforces strict simulator certification standards, promoting technology upgrades. Growing commercial airline operations across Europe increase simulator demand. Defense modernization programs in the UK and France further support the market. It also benefits from collaboration between European OEMs and training service providers to expand simulator capabilities and cost efficiency.
Asia Pacific
The Asia Pacific Flight Simulator Market size was valued at USD 1,316.76 million in 2018, reaching USD 1,773.19 million in 2024, and is anticipated to attain USD 2,716.85 million by 2032, at a CAGR of 5.5% during the forecast period. Asia Pacific captures 26.9% of the total Global Flight Simulator Market share. Rapid air traffic growth and fleet expansion across China, India, and Japan are driving regional demand. Major airlines are investing in training facilities to manage rising pilot requirements. China leads with large-scale simulator installations in new aviation academies. India’s focus on domestic aviation and low-cost carriers adds to growth. Japan and South Korea contribute through advanced defense aviation programs. It benefits from increasing government support for training infrastructure and partnerships with global simulator developers to strengthen regional capabilities.
Latin America
The Latin America Flight Simulator Market size was valued at USD 366.21 million in 2018, reaching USD 476.85 million in 2024, and is anticipated to attain USD 697.95 million by 2032, at a CAGR of 4.9% during the forecast period. Latin America accounts for 6.9% of the total Global Flight Simulator Market share. The region is expanding its aviation training infrastructure to meet growing pilot demand. Brazil leads with simulator installations for both commercial and defense applications. Mexico and Argentina are investing in new pilot training centers to support airline expansion. The market benefits from modernization programs in regional carriers. Economic recovery and air traffic growth across Latin America are improving simulator adoption. It faces challenges from budget constraints and limited access to advanced technologies but continues to show steady progress in simulator-based aviation training.
Middle East
The Middle East Flight Simulator Market size was valued at USD 289.17 million in 2018, reaching USD 387.40 million in 2024, and is anticipated to attain USD 589.56 million by 2032, at a CAGR of 5.4% during the forecast period. The Middle East contributes 5.8% to the total Global Flight Simulator Market share. The region’s growth is led by strong aviation investments in GCC nations, primarily the UAE, Qatar, and Saudi Arabia. Expanding fleets of major airlines such as Emirates and Qatar Airways drive training requirements. Governments are funding simulator-based academies to support pilot localization initiatives. Defense aviation also plays a key role, with military forces investing in combat and mission simulators. It benefits from collaborations between regional training institutions and international simulator manufacturers, improving training quality and capacity.
Africa
The Africa Flight Simulator Market size was valued at USD 139.08 million in 2018, reaching USD 180.62 million in 2024, and is anticipated to attain USD 263.38 million by 2032, at a CAGR of 4.9% during the forecast period. Africa holds 2.6% of the total Global Flight Simulator Market share. The region’s growth is driven by expanding air transport networks and rising interest in aviation training. South Africa leads with well-established training schools and regional airline hubs. Egypt is investing in simulator technology to strengthen its aviation infrastructure. Limited financial resources and low simulator availability restrict market expansion in other African nations. However, rising regional connectivity and international partnerships are helping improve training access. It continues to advance gradually through focused aviation development initiatives across key African economies.
Key Player Analysis:
- CAE Inc.
- L3Harris Technologies, Inc.
- Thales SA
- Indra Sistemas S.A.
- FlightSafety International Inc.
- The Boeing Company
- VirTra, Inc.
- Teledyne Brown Engineering, Inc.
- Saab AB
- Meggitt PLC
- Other Key Players – including regional and niche simulator manufacturers, technology developers, and training service providers contributing to innovation and global market expansion.
Competitive Analysis:
The Global Flight Simulator Market is highly competitive, with major players focusing on innovation, product development, and expansion. Companies such as CAE Inc., L3Harris Technologies, Thales SA, and FlightSafety International dominate through advanced simulation solutions and extensive training networks. It emphasizes continuous R&D investments to enhance realism, automation, and connectivity in simulator platforms. Partnerships with airlines, defense organizations, and training academies strengthen market positioning. Emerging players are targeting niche applications such as UAV training and urban air mobility. Competitive differentiation depends on simulator fidelity, cost efficiency, and after-sales support. Strategic alliances and mergers continue to shape the market’s technological edge and global presence.
Recent Developments:
- VirTra, Inc. demonstrated its next-generation Soldier Virtual Training (SVT) system for the U.S. Army PEO STRI on October 7, 2025. The portable V-100 SVT system showcased marksmanship, joint fires, and use-of-force training capabilities and integrated with VBS4 simulation software. The demonstration reportedly exceeded requirements, with advanced ballistic accuracy and analytics included at no additional cost.
- In October 2025, CAE Inc. announced an agreement to deliver a new Boeing 737MAX full-flight simulator to MAB Academy, the training arm of Malaysia Airlines Group. The simulator is equipped with the CAE Prodigy Image Generator powered by Unreal Engine, offering photorealistic visual capabilities, and is expected to be ready for training by July 2026. This collaboration marks a long-standing partnership between CAE and Malaysia Airlines since 2008.
- FlightSafety International advanced its mixed reality training capabilities in September 2025 by expanding its VITAL MR technology across certified training environments. This technology adds immersive, scenario-based instruction layers to flight simulators, enhancing pilot readiness while reducing dependency on actual aircraft through scalable training options across fixed- and rotary-wing platforms.
Report Coverage:
The research report offers an in-depth analysis based on vehicle type, application, and type segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing adoption of AI and VR technologies will transform pilot training realism.
- Defense modernization programs will increase simulator investments across regions.
- Expansion of airline fleets will drive demand for advanced Full Flight Simulators.
- Urban air mobility and drone operations will open new simulator market segments.
- Strategic collaborations between OEMs and simulator developers will accelerate innovation.
- Increased focus on sustainability will boost virtual training to reduce fuel use.
- Cloud-based platforms will enable remote and connected simulator training models.
- Regional training centers in Asia Pacific and the Middle East will see rapid expansion.
- Simulation standardization by aviation authorities will enhance global training quality.
- AI-based analytics will support predictive maintenance and performance optimization.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Demand for Pilot Training and Aviation Safety Standards
The expansion of commercial and military aircraft fleets is increasing the need for skilled pilots, making simulation-based training essential for safe, cost-effective skill development and regulatory compliance. Enhanced realism in simulators helps reduce human error and supports airlines in meeting stringent safety standards.
Technological Advancements in Simulation Hardware and Software
Continuous innovation in AI, virtual reality, and motion capture systems is improving the realism and effectiveness of flight simulators, enabling more immersive and precise pilot training. These advancements also support multi-aircraft simulation, remote training, and lower lifecycle costs.
Growth in Commercial Aviation and Aircraft Deliveries
Rising air travel demand and new aircraft deliveries are driving airlines to invest in simulator-based training centers, which help reduce operational costs and ensure pilots are certified efficiently. The proliferation of low-cost carriers and expanding fleets in emerging markets further amplifies simulator demand.
Military Modernization and Increased Defense Spending
Defense forces are investing in advanced simulation systems to enhance pilot readiness for complex missions, reduce operational risks, and lower training costs. Modern simulators support frequent drills and tactical planning for next-generation aircraft, fueling market growth in the defense segment.
Expansion of Cloud-Based and Remote Training Platforms
The adoption of cloud technology and remote simulator operation is making pilot training more accessible and scalable, reducing infrastructure costs for training centers and enabling real-time performance monitoring and virtual instruction across geographies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
hat is the current market size for Global Flight Simulator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Flight Simulator Market projected to grow between 2025 and 2032?
Which Global Flight Simulator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Flight Simulator Market?
Who are the leading companies in the Global Flight Simulator Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Full Flight Simulator (FFS)
- 1.2.2 Full Mission Simulator (FMS)
- 1.2.3 Flight Training Devices (FTD)
- 1.2.4 Fixed Base Simulator (FBS)
- 1.3 By Application
- 1.3.1 Military
- 1.3.2 Commercial
- 1.4 By Vehicle Type
- 1.4.1 Fixed Wing
- 1.4.2 Rotary Wing
- 1.4.3 Unmanned Aircraft
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,682.6 million → 2032: USD 10,129.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Flight Simulator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Flight Simulator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Flight Simulator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Flight Simulator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Flight Simulator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Flight Simulator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Flight Simulator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Flight Simulator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,682.6 million → 2032: USD 10,129.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Flight Simulator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Full Flight Simulator (FFS)
- 12.3.7.2 Full Mission Simulator (FMS)
- 12.3.7.3 Flight Training Devices (FTD)
- 12.3.7.4 Fixed Base Simulator (FBS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Military
- 12.4.7.2 Commercial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fixed Wing
- 12.5.7.2 Rotary Wing
- 12.5.7.3 Unmanned Aircraft
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Flight Simulator End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Flight Simulator Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Flight Simulator Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Flight Simulator Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CAE Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 L3Harris Technologies, Inc.
- 18.4 Thales SA
- 18.5 Indra Sistemas S.A.
- 18.6 FlightSafety International Inc.
- 18.7 The Boeing Company
- 18.8 VirTra, Inc.
- 18.9 Teledyne Brown Engineering, Inc.
- 18.10 Saab AB
- 18.11 Meggitt PLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

