
Market Overview
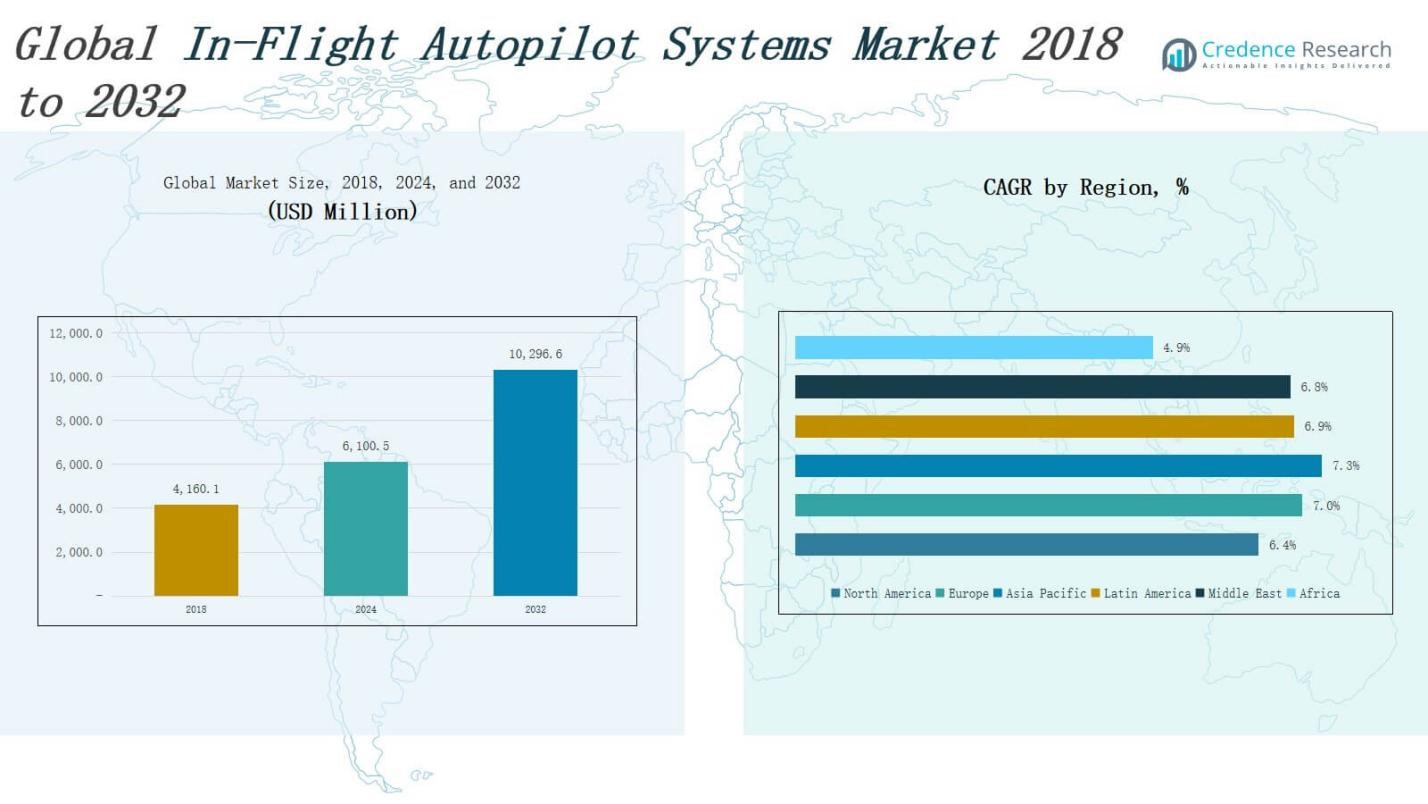
The In Flight Autopilot Systems Market size was valued at USD 4,160.1 million in 2018 to USD 6,100.5 million in 2024 and is anticipated to reach USD 10,296.6 million by 2032, at a CAGR of 6.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| In Flight Autopilot Systems Market Size 2024 | USD 6,100.5 Million |
| In Flight Autopilot Systems Market, CAGR | 6.80% |
| In Flight Autopilot Systems Market Size 2032 | USD 10,296.6 Million |
The In-Flight Autopilot Systems Market is driven by the growing demand for advanced flight management solutions that enhance operational efficiency, reduce pilot workload, and improve flight safety. Increasing air traffic, coupled with the global expansion of commercial aviation and unmanned aerial vehicles (UAVs), is fueling the adoption of sophisticated autopilot technologies. Regulatory mandates emphasizing reduced human error and improved situational awareness further accelerate integration. The market is also benefiting from rising investments in next-generation avionics, digital flight control systems, and autonomous navigation platforms. Key trends shaping the industry include the miniaturization of autopilot components, integration of artificial intelligence (AI) for adaptive flight control, and the development of fly-by-wire systems across both manned and unmanned aircraft. The shift toward electric vertical takeoff and landing (eVTOL) aircraft and urban air mobility (UAM) solutions is creating new avenues for autopilot innovation. As OEMs and defense sectors prioritize automation and flight efficiency, the market continues to evolve rapidly.
The In Flight Autopilot Systems Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America holds the largest share, driven by strong aerospace infrastructure and defense investments. Europe follows with robust commercial aircraft production and regulatory support. Asia Pacific shows rapid growth due to expanding airline fleets and military modernization. Latin America and the Middle East experience steady demand from civil aviation and UAV applications, while Africa exhibits emerging potential through fleet upgrades and aviation reforms. Leading players in this market include Lockheed Martin Corporation, Rockwell Collins, Inc., Honeywell International Inc., Garmin Ltd., BAE Systems Plc, L-3 Communication Holding Inc., MicroPilot Inc., Airware Inc., Cloud Cap Technology Inc., and Tile Inc. These companies compete through technological innovation, strategic partnerships, and advanced autopilot integration across commercial, civil, and military platforms.
Market Insights
- The In Flight Autopilot Systems Market was valued at USD 4,160.1 million in 2018, reached USD 6,100.5 million in 2024, and is projected to hit USD 10,296.6 million by 2032, growing at a CAGR of 6.80%.
- Rising demand for flight safety, reduced pilot workload, and enhanced operational efficiency continues to drive adoption across commercial and defense fleets.
- UAV integration is expanding rapidly, as autopilot systems enable precise autonomous navigation, stability, and mission control across various industries.
- Regulatory pressure to reduce human error and enable real-time flight control through AI and automation accelerates system upgrades and deployment.
- High costs of R&D, certification, and integration remain key barriers, particularly for retrofitting older aircraft and for smaller market entrants.
- North America leads the market with over 30% share, followed by Europe and Asia Pacific, driven by strong OEM presence, regulatory backing, and fleet expansion.
- Key players include Lockheed Martin, Rockwell Collins, Honeywell, Garmin, BAE Systems, and MicroPilot, competing on innovation, integration capabilities, and platform adaptability.
Market Drivers
Rising Demand for Advanced Flight Safety and Operational Efficiency
The In Flight Autopilot Systems Market is driven by the aviation industry's focus on improving safety, reducing pilot workload, and enhancing overall flight efficiency. Autopilot systems help maintain precise navigation, manage complex flight phases, and ensure error-free operations. Airlines and defense sectors rely on these systems to minimize human error and improve fuel management. It supports long-haul operations by offering automated control, reducing pilot fatigue, and increasing operational consistency. The demand continues to rise across both commercial and military fleets.
- For instance, Boeing’s 787 Dreamliner incorporates advanced autopilot features that automate complex tasks such as route optimization and automatic landing, enabling more precise navigation and supporting fuel-efficient operations.
Increasing Adoption in Unmanned Aerial Vehicles (UAVs)
Unmanned Aerial Vehicles are becoming integral to defense, logistics, agriculture, and surveillance sectors, which significantly drives the In Flight Autopilot Systems Market. These vehicles depend on autopilot systems for autonomous navigation, route planning, and mission execution. It ensures stability and control without human intervention. The growing use of UAVs across tactical and civilian operations creates a strong need for high-performance autopilot solutions. Advancements in miniaturized avionics further enable broader UAV applications globally.
- For instance, the Pixhawk 4, developed by Holybro, is widely used in commercial and professional UAVs. It features advanced sensors like the u-blox Neo-M8N GPS receiver and MS5611 barometer, providing reliable autonomous navigation and stabilization for diverse drone operations.
Regulatory Push for Automation and Next-Generation Avionics
Aviation authorities worldwide are enforcing regulations that emphasize safety automation and standardized autopilot functionality. These mandates are prompting manufacturers to incorporate autopilot systems in both new aircraft and retrofit programs. The In Flight Autopilot Systems Market benefits from this shift, with compliance requirements accelerating upgrades. It aligns with global air safety objectives and supports seamless integration into evolving airspace environments. The rise of pilotless aircraft programs is also influenced by these policy directions.
Technological Advancements in AI and Flight Control Systems
Rapid innovation in AI and sensor technologies is transforming autopilot systems into intelligent flight assistants. AI-driven algorithms now enable dynamic decision-making in real-time flight scenarios. It helps aircraft respond to weather, airspace congestion, and equipment anomalies without pilot input. The In Flight Autopilot Systems Market is gaining momentum through investments in autonomous flight, fly-by-wire controls, and adaptive software. Such technological progress is crucial for next-generation aircraft, including electric and hybrid air vehicles.
Market Trends
Integration of Artificial Intelligence and Machine Learning in Autopilot Systems
The adoption of artificial intelligence (AI) and machine learning is transforming the capabilities of modern autopilot systems. AI enables real-time decision-making based on complex data inputs, including weather conditions, air traffic, and onboard diagnostics. It supports predictive navigation and enhances flight safety by reducing reliance on pilot interventions. The In Flight Autopilot Systems Market is witnessing increased investment in AI-powered flight control systems. These advancements align with the industry's push for autonomous and adaptive aircraft systems.
- For instance, Tesla’s Autopilot system collects over 1 billion miles of real-world driving data annually, refining its AI to manage complex driving behaviors in unpredictable environments, which parallels the adaptive learning potential sought in autopilot aircraft systems.
Expansion of Fly-by-Wire Technology Across Aircraft Platforms
Fly-by-wire systems are becoming standard across commercial and military aircraft, replacing traditional mechanical control systems. This digital interface improves response precision, reduces system weight, and enhances overall aircraft efficiency. The In Flight Autopilot Systems Market is evolving with these upgrades, enabling seamless integration of autopilot functions into digital control environments. It ensures consistent performance across various flight phases and supports advanced maneuvering. Fly-by-wire adoption also simplifies system diagnostics and improves maintainability.
- For instance, the Airbus A320, first introduced with a fully digital fly-by-wire control system in 1987, demonstrated improved handling and operational efficiency, setting a standard now followed in subsequent Airbus models.
Growing Demand from Electric and Urban Air Mobility Aircraft
The rise of electric vertical takeoff and landing (eVTOL) and urban air mobility (UAM) aircraft is fueling demand for compact and efficient autopilot systems. These next-generation platforms require lightweight, software-driven controls capable of operating with minimal pilot input. The In Flight Autopilot Systems Market is expanding into this emerging aviation segment. It supports fully autonomous flight modes critical for short-distance air taxis and drone deliveries. Market players are focusing on modular autopilot systems tailored for UAM applications.
Advancements in Satellite Navigation and Communication Systems
The integration of satellite-based navigation systems such as GNSS and SBAS is improving autopilot accuracy and global coverage. Enhanced connectivity through satellite communication supports continuous data exchange for real-time flight updates. The In Flight Autopilot Systems Market is benefiting from these technological upgrades, which enable better coordination with air traffic control and improve situational awareness. It enhances route optimization, supports dynamic rerouting, and strengthens autopilot reliability in remote or high-traffic regions.
Market Challenges Analysis
High Costs Associated with Development, Integration, and Certification
Developing and integrating advanced autopilot systems involves significant costs related to R&D, hardware, software, and regulatory certification. Aviation authorities require extensive testing and validation to ensure safety, which extends development timelines and raises expenses. Smaller manufacturers and startups face entry barriers due to these financial demands. The In Flight Autopilot Systems Market is constrained by the capital-intensive nature of avionics upgrades, especially in retrofit programs. It limits adoption across price-sensitive markets and aging aircraft fleets.
Cybersecurity Risks and System Reliability Concerns
The increasing reliance on software-driven autopilot systems raises concerns about data integrity, cybersecurity, and operational reliability. Aircraft systems connected to external networks are exposed to potential cyber threats that could compromise flight control. Ensuring fail-safe system redundancy and protection against interference remains a critical challenge. The In Flight Autopilot Systems Market must address these vulnerabilities through continuous system updates and stringent security protocols. It must also maintain consistent performance under varied flight and environmental conditions.
Market Opportunities
Rising Demand for Autonomous Flight in Commercial and Defense Sector
The growing push toward autonomous flight presents a major opportunity for the In Flight Autopilot Systems Market. Airlines and defense agencies seek systems that enable reduced crew operations and increased automation. It supports cost savings, enhances safety, and meets evolving mission requirements. Investments in pilotless cargo planes, surveillance UAVs, and optionally piloted vehicles create a favorable environment for autopilot innovation. Countries with advanced defense programs are accelerating funding for autonomous aircraft platforms.
Emerging Applications in Urban Air Mobility and Electric Aviation
Urban air mobility (UAM) and electric aviation represent untapped markets with high growth potential for autopilot system providers. These platforms require compact, lightweight, and highly reliable autopilot systems to operate in dense urban environments. The In Flight Autopilot Systems Market can capitalize on the need for seamless vertical flight, precision navigation, and remote piloting. It aligns with sustainability goals and supports the development of low-emission aerial transport. Technology providers are expanding offerings to serve startups and aerospace OEMs entering the UAM segment.
Market Segmentation Analysis:
By System
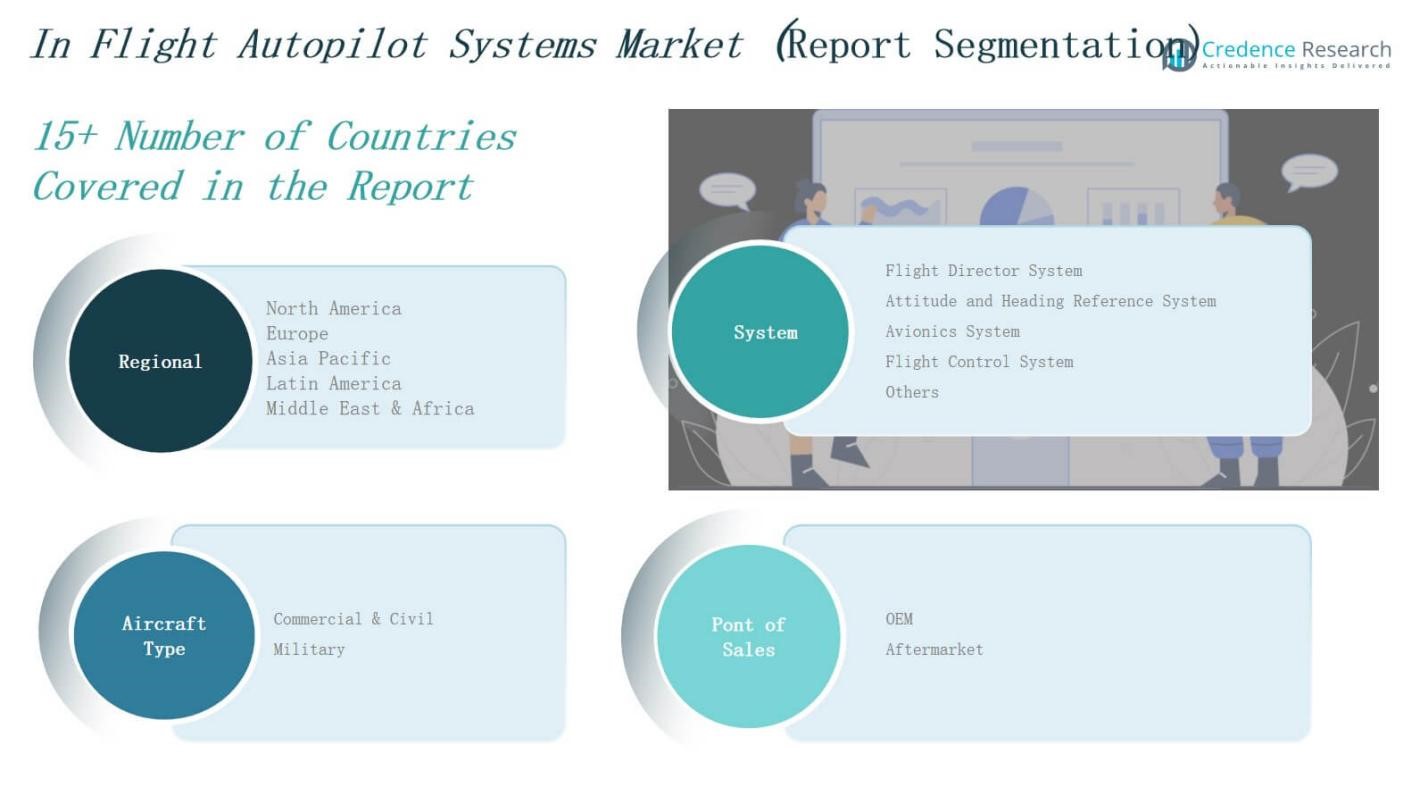
The In Flight Autopilot Systems Market is segmented into Flight Director System, Attitude and Heading Reference System, Avionics System, Flight Control System, and Others. Flight Director Systems enhance pilot situational awareness and flight path accuracy, driving strong demand in commercial aviation. Attitude and Heading Reference Systems support navigation integrity, especially in turbulent or GPS-denied environments. Avionics Systems integrate multiple subsystems, enabling advanced flight automation. Flight Control Systems remain critical for stability and maneuverability across aircraft platforms.
- For instance, the Boeing 787’s avionics suite also exemplifies integrated Avionics Systems; it combines flight management, communication, and surveillance in a modular setup, supporting advanced automation and enhanced flight safety for airline operators.
By Aircraft Type
Based on aircraft type, the In Flight Autopilot Systems Market includes Commercial & Civil and Military segments. Commercial and civil aviation holds the largest share due to rising air travel, growing fleet size, and regulatory pressure to enhance operational safety. It benefits from demand for fuel-efficient, low-maintenance autopilot systems. The military segment focuses on mission-specific capabilities, including UAVs and combat aircraft, where autonomous flight control supports reconnaissance, strike, and surveillance missions with minimal human input.
- For example, in September 2024, the US Air Force awarded Reliable Robotics $3.6 million to test autonomous flight systems for cargo missions under the AFWERX TACFI program, advancing unmanned operations to meet FAA and Department of Defense requirements.
By Point of Sales
The market is categorized into OEM and Aftermarket segments based on point of sales. OEM dominates due to strong integration of autopilot systems in new aircraft manufacturing programs. Aircraft manufacturers prioritize embedded automation to meet certification and efficiency standards. The aftermarket segment offers growth potential through retrofitting older fleets with updated autopilot capabilities. It caters to airline operators aiming to extend aircraft life while aligning with modern performance and safety benchmarks.
Segments:
Based on System
- Flight Director System
- Attitude and Heading Reference System
- Avionics System
- Flight Control System
- Others
Based on Aircraft Type
- Commercial & Civil
- Military
Based on Point of Sales
- OEM
- Aftermarket
Based on Region:
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis
North America
The North America In Flight Autopilot Systems Market size was valued at USD 1,335.82 million in 2018 to USD 1,915.47 million in 2024 and is anticipated to reach USD 3,135.33 million by 2032, at a CAGR of 6.4% during the forecast period. North America holds the largest market share, accounting for over 30% of the global revenue. It leads due to the strong presence of aerospace OEMs, military modernization programs, and high commercial aircraft demand. The region benefits from early adoption of advanced avionics and FAA regulatory support for autonomous flight systems. It also sees sustained investment in UAV and business jet segments. Continuous technological upgrades across defense and civil fleets strengthen its regional dominance in the In Flight Autopilot Systems Market.
Europe
The Europe In Flight Autopilot Systems Market size was valued at USD 1,094.95 million in 2018 to USD 1,623.43 million in 2024 and is anticipated to reach USD 2,780.09 million by 2032, at a CAGR of 7.0% during the forecast period. Europe contributes around 25% to the global market, driven by innovation in aviation automation and support from EASA regulations. Countries such as Germany, France, and the UK lead regional growth with strong aerospace production and integration capabilities. The presence of Airbus and other OEMs fuels demand for embedded autopilot systems. It benefits from growing demand for regional jets and military UAVs. Environmental policies also encourage the development of energy-efficient autopilot solutions.
Asia Pacific
The Asia Pacific In Flight Autopilot Systems Market size was valued at USD 943.10 million in 2018 to USD 1,420.63 million in 2024 and is anticipated to reach USD 2,482.52 million by 2032, at a CAGR of 7.3% during the forecast period. Asia Pacific holds a market share of over 22%, fueled by rapid growth in commercial aviation and fleet expansion across China, India, Japan, and Southeast Asia. The region experiences strong demand for new aircraft equipped with digital flight control systems. It also benefits from increased defense spending, particularly in UAV programs and regional air force upgrades. Rising low-cost carrier operations drive autopilot adoption in narrow-body aircraft. Domestic manufacturing initiatives and airport infrastructure growth support long-term market expansion.
Latin America
The Latin America In Flight Autopilot Systems Market size was valued at USD 443.89 million in 2018 to USD 653.80 million in 2024 and is anticipated to reach USD 1,109.98 million by 2032, at a CAGR of 6.9% during the forecast period. Latin America accounts for approximately 7% of the global market. Brazil and Mexico are key contributors due to their civil aviation hubs and rising demand for fleet modernization. It gains momentum through regional airline growth and increased aircraft deliveries. Economic recovery and tourism sector revival support autopilot upgrades in commercial aircraft. Investments in light and medium military aircraft also boost system installations. Domestic aerospace production partnerships are expected to influence future market share.
Middle East
The Middle East In Flight Autopilot Systems Market size was valued at USD 224.65 million in 2018 to USD 329.95 million in 2024 and is anticipated to reach USD 558.08 million by 2032, at a CAGR of 6.8% during the forecast period. The Middle East contributes close to 5% of global market share. It benefits from large fleet acquisitions by leading carriers in the UAE, Qatar, and Saudi Arabia. Strategic defense programs and UAV expansion also drive autopilot system adoption. The market gains traction through smart airport developments and digital transformation of aviation infrastructure. It supports long-haul aircraft automation and regional air defense initiatives. Local aerospace joint ventures are expected to strengthen system integration capabilities.
Africa
The Africa In Flight Autopilot Systems Market size was valued at USD 117.73 million in 2018 to USD 157.22 million in 2024 and is anticipated to reach USD 230.64 million by 2032, at a CAGR of 4.9% during the forecast period. Africa holds the smallest market share at under 3% but shows steady progress. Growth is supported by regional airline expansion and investments in aviation safety. It sees rising interest in autopilot-equipped turboprops and short-haul aircraft. Government aviation reforms and fleet modernization initiatives contribute to adoption. The military segment is gradually incorporating autonomous flight systems for border surveillance and patrol. Infrastructure limitations remain a challenge but create opportunities for portable and cost-effective autopilot solutions.
Key Player Analysis
- Lockheed Martin Corporation
- Rockwell Collins, Inc.
- Garmin Ltd.
- Airware, Inc.
- Honeywell International Inc.
- BAE Systems, Plc
- L-3 Communication Holding Inc.
- MicroPilot Inc.
- Cloud Cap Technology Inc.
- Tile Inc.
- Other Key Players
Competitive Analysis
The In Flight Autopilot Systems Market features a competitive landscape driven by innovation, system integration capabilities, and global reach. Leading players such as Lockheed Martin, Honeywell International, and Rockwell Collins focus on developing advanced, AI-enabled autopilot solutions for both commercial and military platforms. It favors companies that offer modular systems, seamless avionics integration, and compliance with international airworthiness standards. Garmin and MicroPilot serve niche markets with compact solutions for UAVs and light aircraft. Strategic partnerships, defense contracts, and avionics upgrades strengthen competitive positioning. Firms such as BAE Systems and L-3 Communication Holding Inc. emphasize military-grade systems with high redundancy and real-time data processing. The market remains fragmented, with smaller companies like Airware and Cloud Cap Technology innovating in specialized domains. Long-term success depends on R&D investments, cybersecurity features, and adaptability to evolving aircraft platforms and autonomous flight requirements. Competitive differentiation hinges on performance reliability, integration flexibility, and regulatory alignment.
Recent Developments
- In June 2025, Garmin Ltd. received FAA approval for its GFC 600H helicopter autopilot system, now certified for the Robinson R66 platform.
- On July 16, 2025, Lockheed Martin completed successful flight tests of its CMMT-D and CMMT-X configurations under the Common Multi-Mission Truck (CMMT) program.
- In January 2025, Honeywell International Inc. announced a partnership with NXP Semiconductors to accelerate the development of AI-enabled avionics and autonomous flight systems.
- In June 2025, Wisk Aero, a subsidiary of Boeing, acquired SkyGrid to enhance autonomous flight capabilities for its eVTOL air taxi operations.
Market Concentration & Characteristics
The In Flight Autopilot Systems Market demonstrates moderate to high market concentration, dominated by a few established aerospace and defense players with strong R&D capabilities and global distribution networks. It favors companies with advanced avionics integration, regulatory compliance, and the ability to support both commercial and military platforms. The market is characterized by long product lifecycles, high certification barriers, and strategic partnerships between OEMs and avionics suppliers. It features significant investment in AI-driven automation, miniaturization, and fly-by-wire technologies. Demand for scalable, modular autopilot solutions continues to rise, especially for unmanned aerial vehicles and next-generation electric aircraft. The industry operates under stringent safety standards, which drive system reliability and product differentiation. Competitive advantage depends on innovation speed, cybersecurity assurance, and seamless integration with digital flight control architectures. The In Flight Autopilot Systems Market remains sensitive to geopolitical defense budgets and commercial airline procurement cycles, creating a dynamic but technically intensive environment for market participants.
Report Coverage
The research report offers an in-depth analysis based on System, Aircraft Type, Point of Sales and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for AI-enabled autopilot systems will grow across both commercial and defense aviation sectors.
- Integration of autonomous flight technology in UAVs will expand across logistics, agriculture, and surveillance applications.
- Electric and hybrid aircraft will require lightweight, energy-efficient autopilot solutions.
- Urban air mobility platforms will boost adoption of compact and fully automated flight control systems.
- Airlines will increasingly retrofit older fleets with modern autopilot systems to extend operational life.
- Military programs will prioritize advanced autopilot integration for unmanned combat and reconnaissance missions.
- Cybersecurity features will become a critical differentiator in autopilot system procurement.
- Miniaturized avionics and fly-by-wire systems will drive innovation in autopilot hardware.
- Partnerships between OEMs and technology providers will accelerate product development cycles.
- Regulatory agencies will encourage wider adoption of automated systems to improve flight safety and efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advanced Flight Safety and Operational Efficiency
Airlines and defense operators are increasingly adopting autopilot systems to enhance flight safety, reduce pilot workload, and improve operational efficiency. These systems enable precise navigation, automated control during complex flight phases, and support for long-haul operations, directly contributing to reduced human error and improved fuel management.
Expansion of UAV and Autonomous Aircraft Applications
The rapid growth of unmanned aerial vehicles (UAVs) in defense, logistics, agriculture, and surveillance is driving demand for sophisticated autopilot systems. These platforms rely on autopilot technology for autonomous navigation, mission execution, and stability, expanding the market beyond traditional manned aircraft.
Regulatory Push for Automation and Avionics Upgrades
Global aviation authorities are mandating higher levels of automation and standardized autopilot functionality to improve air safety. These regulations are accelerating the integration of advanced autopilot systems in both new aircraft and retrofit programs, supporting compliance and modernization across fleets.
Technological Advancements in AI and Digital Flight Control
Innovations in artificial intelligence, machine learning, and fly-by-wire technology are transforming autopilot systems into intelligent flight assistants. These advancements enable real-time decision-making, adaptive flight control, and seamless integration with digital avionics, making autopilot systems more reliable and capable.
Emergence of Electric and Urban Air Mobility Aircraft
The rise of electric vertical takeoff and landing (eVTOL) and urban air mobility (UAM) platforms is creating new demand for compact, lightweight, and highly automated autopilot systems. These next-generation aircraft require advanced flight control solutions to operate safely and efficiently in urban environments, opening new growth avenues for autopilot providers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the In Flight Autopilot Systems Market?
What factors are driving the growth of the In Flight Autopilot Systems Market?
What are the key segments within the In Flight Autopilot Systems Market?
What are some challenges faced by the In Flight Autopilot Systems Market?
Who are the major players in the In Flight Autopilot Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By System
- 1.2.1 Flight Director System
- 1.2.2 Attitude and Heading Reference System
- 1.2.3 Avionics System
- 1.2.4 Flight Control System
- 1.2.5 Others
- 1.3 By Aircraft Type
- 1.3.1 Commercial & Civil
- 1.3.2 Military
- 1.4 By Point of Sales
- 1.4.1 OEM
- 1.4.2 Aftermarket
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,100.5 million → 2032: USD 10,296.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global In-flight Autopilot Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global In-flight Autopilot Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global In-flight Autopilot Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global In-flight Autopilot Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global In-flight Autopilot Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global In-flight Autopilot Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global In-flight Autopilot Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global In-flight Autopilot Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,100.5 million → 2032: USD 10,296.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global In-flight Autopilot Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By System - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Flight Director System
- 12.3.7.2 Attitude and Heading Reference System
- 12.3.7.3 Avionics System
- 12.3.7.4 Flight Control System
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Aircraft Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial & Civil
- 12.4.7.2 Military
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Point of Sales - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 OEM
- 12.5.7.2 Aftermarket
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global In-flight Autopilot Systems Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global In-flight Autopilot Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global In-flight Autopilot Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Lockheed Martin Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Rockwell Collins, Inc.
- 17.4 Honeywell International Inc.
- 17.5 Garmin Ltd.
- 17.6 BAE Systems Plc
- 17.7 L-3 Communication Holding Inc.
- 17.8 MicroPilot Inc.
- 17.9 Airware Inc.
- 17.10 Cloud Cap Technology Inc.
- 17.11 Tile Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

