
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Foliar Treatment Market Size 2024 | UUSD 15,131.72 million |
| Foliar Treatment Market, CAGR | 6.28% |
| Foliar Treatment Market Size 2032 | USD 25,500.93 million |
Market Overview
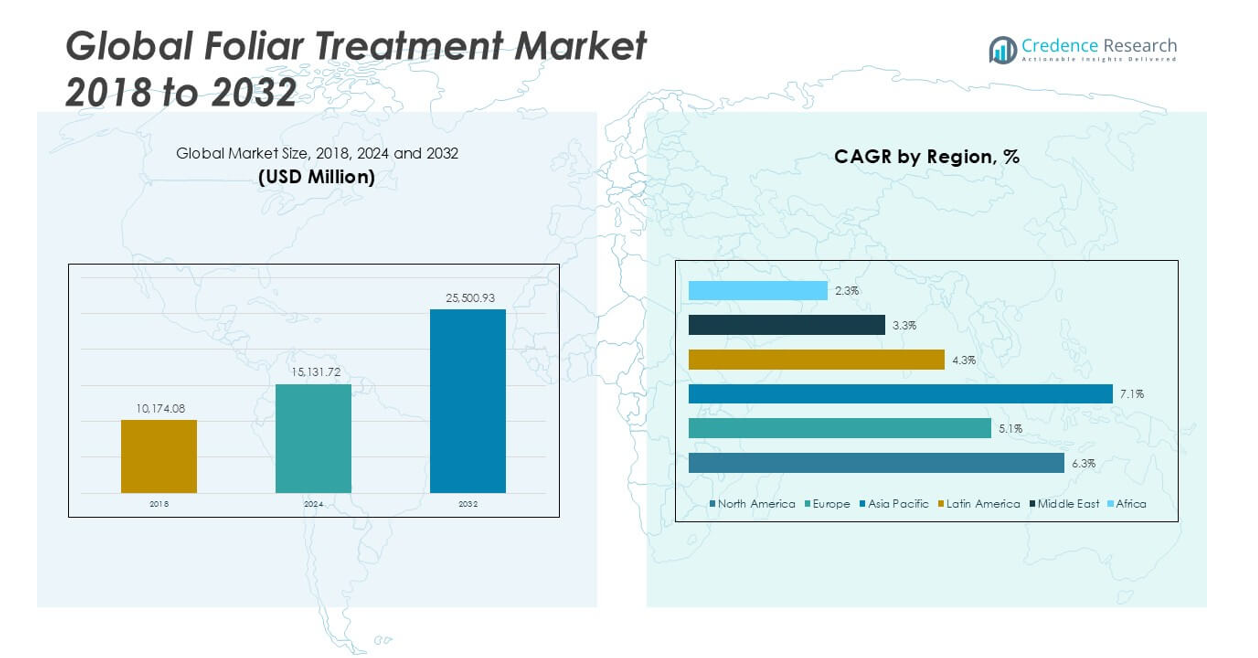
The Foliar Treatment Market was valued at USD 10,174.08 million in 2018 and increased to USD 15,131.72 million in 2024. It is anticipated to reach USD 25,500.93 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.28% during the forecast period.
The Foliar Treatment Market is experiencing robust growth driven by the increasing demand for high-efficiency crop protection solutions and the rising emphasis on sustainable agriculture practices. Farmers are adopting foliar treatments to improve nutrient uptake, boost plant resilience, and achieve higher yields with reduced input costs. Advances in formulation technology and the introduction of micronutrient-rich sprays have enhanced the effectiveness of these products, making them more attractive to modern growers. The market also benefits from a shift toward precision farming, which leverages data-driven application methods for optimal results. Growing concerns about soil health and the need to address nutrient deficiencies quickly further propel market adoption. The trend toward organic and environmentally friendly products has encouraged manufacturers to develop innovative foliar treatments with minimal environmental impact, positioning the market for steady expansion as agricultural practices evolve globally.
The Foliar Treatment Market demonstrates significant geographical diversity, with strong demand in regions such as Asia Pacific, North America, and Europe. Asia Pacific leads due to rapid modernization in agriculture, increasing focus on crop yield improvement, and widespread adoption of advanced input technologies across countries like China and India. North America and Europe follow closely, driven by high-value horticultural and field crop cultivation, well-established agricultural infrastructure, and strong regulatory support for sustainable farming. Latin America and the Middle East are also emerging as promising markets, supported by growing investments in commercial agriculture and crop nutrition. Leading companies such as Corteva Agriscience, BASF SE, and Syngenta AG play a pivotal role in shaping market trends, driving innovation, and expanding the reach of foliar treatment solutions. These key players focus on developing advanced formulations and tailored solutions to meet the evolving needs of farmers across diverse agroclimatic regions.
Market Insights
- The Foliar Treatment Market was valued at USD 10,174.08 million in 2018, reached USD 15,131.72 million in 2024, and is projected to hit USD 25,500.93 million by 2032, registering a CAGR of 6.28%.
- Growing demand for high-efficiency crop inputs and sustainable farming practices continues to drive market adoption worldwide.
- Bio-based and organic foliar solutions are gaining popularity as farmers and producers seek environmentally friendly alternatives and comply with stricter regulatory standards.
- Advanced formulation technologies, including microencapsulation and nanotechnology, are enhancing product effectiveness and boosting uptake among commercial growers.
- Major players such as Corteva Agriscience, BASF SE, and Syngenta AG focus on innovation and expanding their product portfolios to address regional needs and evolving crop challenges.
- Regional growth is strongest in Asia Pacific, followed by North America and Europe, with China, India, and the U.S. leading in adoption of advanced foliar inputs.
- Market expansion faces challenges from limited technical awareness among smallholder farmers and complex regulatory approval processes across different countries.
Market Drivers
Rising Demand for High-Efficiency Crop Inputs Fuels Market Expansion
The agricultural sector is under increasing pressure to boost crop yields while minimizing resource usage and environmental impact. The Foliar Treatment Market benefits from this trend, as farmers and growers seek solutions that maximize nutrient uptake efficiency. Foliar treatments provide direct application of nutrients to plant leaves, improving absorption rates compared to traditional soil applications. This method reduces fertilizer runoff and optimizes input utilization, making it attractive for regions with poor soil health or limited arable land. Farmers recognize the value of achieving higher productivity with fewer resources, driving adoption. It supports sustainable farming by enabling precise nutrient management.
- For instance, Yara International reported that its foliar nutrition programs led to a documented reduction in fertilizer use of 22 units per hectare while increasing wheat yields by over 1.6 metric tons per hectare in field trials.
Technological Advancements Drive Product Innovation
Rapid innovation in formulation and delivery technologies enhances the effectiveness of foliar treatments. The Foliar Treatment Market leverages microencapsulation, nanotechnology, and advanced surfactants to create products that adhere better to plant surfaces and penetrate leaf tissue more efficiently. New formulations extend the shelf life and stability of micronutrient sprays, meeting the needs of modern agriculture. Research efforts focus on combining nutrients, biostimulants, and crop protection agents for multifunctional benefits. These advancements attract growers looking for reliable solutions to enhance crop health and resilience. It positions foliar products as essential tools in integrated crop management strategies.
- For instance, UPL Ltd. launched a patented nano-technology foliar spray that demonstrated a 34% improvement in zinc uptake efficiency and maintained efficacy on leaf surfaces for over 72 hours during university-supervised greenhouse trials.
Shift Toward Sustainable and Environmentally Friendly Agriculture
Growing environmental awareness and tightening regulatory frameworks encourage farmers to adopt foliar treatments with low ecological impact. The Foliar Treatment Market responds to this demand by offering products with minimal residual effects and reduced risk of soil and water contamination. Organic and bio-based foliar sprays align with consumer and regulatory preferences for sustainable agriculture. These solutions support the transition away from conventional agrochemicals, promoting biodiversity and soil health. The market’s evolution reflects the global push for greener agricultural inputs that safeguard long-term productivity.
Precision Farming and Data-Driven Application Methods Increase Adoption
The adoption of precision agriculture technologies accelerates the use of foliar treatments. The Foliar Treatment Market benefits from data-driven application techniques that allow targeted nutrient delivery based on real-time crop and soil analysis. Growers use remote sensing, drones, and GPS-guided equipment to optimize spray timing and dosage. This approach maximizes crop response and minimizes waste, making foliar applications more effective and cost-efficient. It addresses the demand for smarter farming practices that improve both economic and environmental outcomes.
Market Trends
Integration of Bio-Based and Organic Solutions Gains Momentum
A significant trend shaping the Foliar Treatment Market is the increased preference for bio-based and organic foliar products. Farmers and agribusinesses look for solutions that support sustainable farming and reduce chemical residues in food crops. The industry responds by developing plant-derived and microbial formulations that align with environmental and regulatory standards. Bio-based products cater to the rising demand for organic produce and improve soil and crop health without contributing to chemical buildup. It strengthens the market’s position among producers who prioritize sustainability. This trend signals ongoing product development focused on natural ingredients and cleaner agricultural practices.
- For instance, Corteva Agriscience introduced a plant-based foliar biostimulant derived from seaweed extract, with field data showing a 14% reduction in pest infestation rates and an increase in tomato fruit set by 12 clusters per plant.
Digital Technologies and Precision Agriculture Transform Application Practices
Digitalization and precision agriculture technologies are changing how foliar treatments are applied in the field. The Foliar Treatment Market leverages smart sensors, drones, and satellite imagery to provide real-time data on crop health and nutrient requirements. Farmers use this information to schedule and calibrate foliar applications, achieving better efficiency and minimizing input waste. Data-driven strategies enable targeted nutrition, supporting optimal crop growth even under challenging environmental conditions. The shift toward digital agriculture supports the adoption of tailored foliar solutions. It drives the market toward smarter and more resource-efficient farming operations.
- For instance, Bayer AG’s Field View platform enabled precision foliar applications on more than 34 million hectares in one season, demonstrating quantifiable efficiency gains for growers using digital prescription maps.
Customized and Crop-Specific Formulations Drive Differentiation
Manufacturers introduce customized foliar treatments tailored for specific crops and regional requirements. The Foliar Treatment Market reflects a strong emphasis on research-driven product development, allowing companies to address diverse crop nutrition challenges. Crop-specific solutions enhance uptake efficiency and resilience, providing growers with performance advantages. The trend toward differentiated formulations appeals to commercial growers seeking value-added benefits from foliar products. It strengthens partnerships between manufacturers and the agricultural sector, supporting ongoing innovation and market expansion. These solutions help optimize productivity across various agroclimatic zones.
Sustained Focus on Nutrient Efficiency and Stress Mitigation
Efficiency in nutrient utilization and crop stress management remains a key trend in the Foliar Treatment Market. The industry emphasizes products that provide rapid correction of micronutrient deficiencies and enhance resistance to environmental stressors such as drought or salinity. New foliar treatments feature balanced nutrient profiles, biostimulants, and anti-stress agents to support healthy crop growth. It appeals to growers who face climate variability and unpredictable weather patterns. This focus aligns with the increasing need for resilient agricultural systems and drives the demand for next-generation foliar technologies.
Market Challenges Analysis
Limited Awareness and Technical Knowledge Among End Users
Limited awareness and insufficient technical knowledge among farmers restrict the widespread adoption of foliar treatments. The Foliar Treatment Market faces challenges when growers are unfamiliar with the benefits and correct application methods of these products. Misapplication can lead to inconsistent results and reduce confidence in product performance. Smallholder farmers, particularly in developing regions, may lack access to training or extension services. It creates a gap between product innovation and practical usage on the field. This barrier slows market penetration and limits the potential impact of advanced foliar solutions.
Regulatory Hurdles and Concerns Over Product Efficacy
Stringent regulations and varying approval processes across regions pose obstacles for new foliar treatment formulations. The Foliar Treatment Market must navigate complex compliance standards, which can delay product launches and increase development costs. Concerns about the long-term efficacy and safety of certain active ingredients also affect user trust. Regulatory agencies demand robust evidence of environmental safety and crop compatibility, requiring extensive field trials and documentation. It pressures manufacturers to invest in continuous research and regulatory support. These challenges impact the pace of innovation and market growth.
Market Opportunities
Expansion into Emerging Agricultural Markets Drives New Growth
Expansion into emerging agricultural regions offers strong growth opportunities for the Foliar Treatment Market. Large areas in Asia-Pacific, Latin America, and Africa are modernizing agricultural practices and adopting advanced crop management techniques. Rising demand for high-value crops and the need to improve yields present a favorable environment for foliar solutions. Governments in these regions support agricultural innovation through subsidies and educational programs. It creates a pathway for market players to introduce tailored products and training to new user bases. This growth potential aligns with the broader push for food security and sustainable agriculture worldwide.
Development of Innovative, Multifunctional Products Boosts Market Potential
The ongoing development of innovative and multifunctional foliar products opens new avenues for differentiation in the Foliar Treatment Market. Advances in formulation science allow the integration of nutrients, biostimulants, and crop protection agents into single applications. This trend appeals to growers seeking convenience, cost savings, and comprehensive crop health solutions. Precision agriculture tools further enhance product performance by enabling site-specific application. It positions manufacturers to capitalize on the demand for efficient and sustainable inputs. These opportunities support long-term market expansion and encourage further investment in research and product development.
Market Segmentation Analysis:
By Type:
The Foliar Treatment Market features several distinct product segments, each catering to unique agricultural requirements. Nutritional foliar sprays hold a significant share, as they deliver essential macro and micronutrients directly to plant foliage for quick absorption and visible crop health benefits. Foliar pesticides address pest and disease challenges efficiently, supporting integrated pest management programs. Foliar biostimulants are gaining traction, driven by their ability to promote plant growth and resilience under abiotic stress conditions. Foliar growth regulators serve specific applications, including enhancing flowering, fruit setting, or ripening processes. The ‘others’ segment comprises specialized solutions that address niche crop needs and emerging market trends. Each segment reflects ongoing innovation and targeted product development for various crop types and environments.
- For instance, Yara International documented a measurable increase in leaf chlorophyll index within 72 hours of foliar micronutrient application in controlled crop trials, demonstrating the effectiveness of targeted product formulations by segment.
By Physical Form:
The market is segmented into liquid and solid formulations. Liquid foliar treatments dominate, offering ease of application, uniform coverage, and compatibility with modern spraying equipment. These solutions provide rapid nutrient uptake and often include advanced adjuvants for improved efficacy. Solid forms, such as powders or granules, cater to growers seeking extended shelf life or unique mixing requirements. It enables manufacturers to serve diverse user preferences and adapt products for smallholder farmers or large-scale commercial operations. The flexibility of both formats supports wide adoption across different agricultural systems.
- For instance, ICL Specialty Fertilizers demonstrated that its soluble solid foliar formulation maintained product stability for up to 18 months under varied storage conditions, as verified in long-term laboratory tests.
By Application:
The Foliar Treatment Market spans horticultural crops, field crops, turfs and ornamentals, and others. Horticultural crops represent a core application area, where foliar treatments address the high nutrient demands of fruits, vegetables, and specialty crops. Field crops, including cereals and oilseeds, benefit from targeted interventions during critical growth stages. Turfs and ornamentals require precise foliar care to maintain aesthetics and disease resistance in landscaping and recreational environments. The ‘others’ segment covers emerging applications in non-traditional crops and specialized agricultural systems. This diversity in application broadens the market’s reach and supports its expansion into new geographies and farming practices.
Segments:
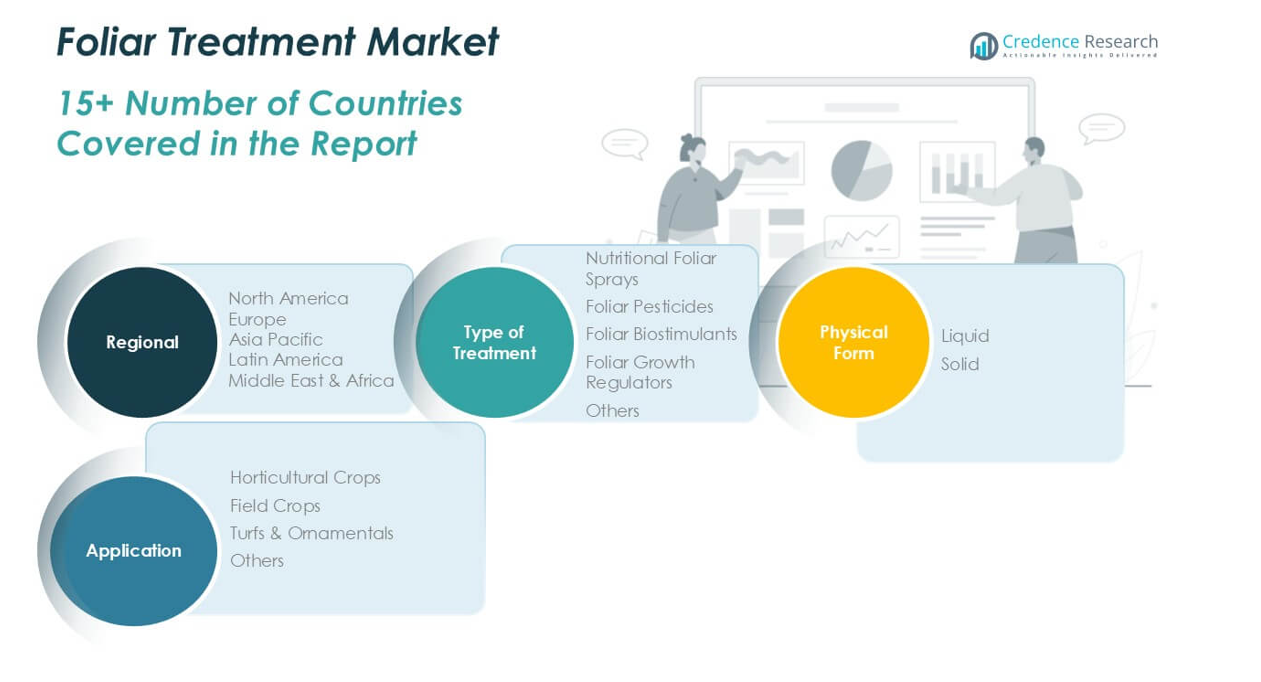
Based on Type:
- Nutritional Foliar Sprays
- Foliar Pesticides
- Foliar Biostimulants
- Foliar Growth Regulators
- Others
Based on Physical Form:
- Liquid
- Solid
Based on Application:
- Horticultural Crops
- Field Crops
- Turfs & Ornamentals
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Foliar Treatment Market
North America Foliar Treatment Market grew from USD 2,370.10 million in 2018 to USD 3,578.65 million in 2024 and is projected to reach USD 5,857.26 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.21%. North America is holding a 24% market share. The United States leads the region with strong adoption of advanced crop input technologies and high-value horticultural production. Canada supports market growth through government initiatives promoting sustainable agriculture. The region’s robust infrastructure, high farm mechanization, and focus on crop quality drive steady demand for foliar treatments.
Europe Foliar Treatment Market
Europe Foliar Treatment Market grew from USD 1,829.28 million in 2018 to USD 2,631.90 million in 2024 and is estimated to reach USD 4,154.41 million by 2032, with a CAGR of 5.96%. Europe represents a 17% market share. France, Germany, and Spain play leading roles, leveraging strong horticultural sectors and a preference for environmentally responsible crop management. The European Union’s emphasis on sustainable farming practices and reduction of chemical inputs supports ongoing adoption. Strict regulatory frameworks and consumer demand for residue-free produce shape product innovation in this region.
Asia Pacific Foliar Treatment Market
Asia Pacific Foliar Treatment Market grew from USD 4,169.40 million in 2018 to USD 6,280.44 million in 2024 and is forecast to reach USD 10,500.37 million by 2032, registering a CAGR of 6.44%. Asia Pacific commands the largest market share at 42%. China and India dominate due to large agricultural bases and growing adoption of precision farming techniques. Japan, Australia, and Southeast Asian countries contribute to growth through investments in crop quality and export-oriented horticulture. Rising population and rapid expansion of commercial farming underpin strong market prospects across the region.
Latin America Foliar Treatment Market
Latin America Foliar Treatment Market grew from USD 1,119.15 million in 2018 to USD 1,672.30 million in 2024 and is projected to reach USD 2,712.50 million by 2032, recording a CAGR of 6.06%. Latin America holds an 11% market share. Brazil and Argentina remain the region’s largest consumers, focusing on soybean, maize, and specialty crop production. The market benefits from increased export activity and government programs supporting input efficiency. Mexico and Chile also contribute to regional expansion, particularly in fruit and vegetable segments.
Middle East Foliar Treatment Market
Middle East Foliar Treatment Market grew from USD 383.99 million in 2018 to USD 575.94 million in 2024 and is set to reach USD 945.35 million by 2032, at a CAGR of 6.23%. The Middle East claims a 4% market share. Saudi Arabia, the UAE, and Israel show notable adoption due to their investments in high-tech agriculture and water-saving technologies. Regional challenges such as water scarcity and saline soils encourage foliar input use for efficient crop nutrition. Governments promote sustainable production to enhance food security and reduce reliance on imports.
Africa Foliar Treatment Market
Africa Foliar Treatment Market grew from USD 302.16 million in 2018 to USD 392.49 million in 2024 and is expected to reach USD 674.34 million by 2032, with a CAGR of 6.98%. Africa holds a 3% market share. South Africa, Egypt, and Morocco lead growth, driven by expanding commercial agriculture and increasing awareness of crop nutrition solutions. The region presents untapped potential as countries invest in agricultural modernization. Foliar treatments appeal to farmers seeking higher yields and improved resilience in challenging agroclimatic conditions.
Key Player Analysis
- Corteva Agriscience
- BASF SE
- Sumitomo Chemical Co. Ltd.
- Germain's Seed Technology, Inc.
- FMC Corporation
- Syngenta AG
- NuFarm Ltd.
- Bayer AG
- Croda International PLC
- UPL Ltd.
Competitive Analysis
The Foliar Treatment Market features intense competition among leading players such as Corteva Agriscience, BASF SE, Sumitomo Chemical Co. Ltd., Germain's Seed Technology, Inc., FMC Corporation, Syngenta AG, NuFarm Ltd., Bayer AG, Croda International PLC, and UPL Ltd. These companies focus on broadening their product portfolios through the development of innovative and differentiated foliar treatment solutions tailored to diverse crop needs and regional requirements. Investment in research and development remains a core strategy, with key players working to enhance nutrient uptake efficiency, extend product shelf life, and address specific pest and disease pressures. Strategic collaborations, partnerships with research institutions, and acquisitions help these companies expand their geographical presence and accelerate technology transfer. Sustainability and environmental stewardship drive the introduction of bio-based and low-residue products, which resonate with evolving regulatory expectations and consumer preferences. Leading firms leverage strong distribution networks and technical support services to maintain close relationships with growers, providing guidance on best practices and maximizing product efficacy. Continuous innovation and a focus on farmer-centric solutions ensure that top companies retain a competitive edge in a rapidly evolving agricultural landscape.
Recent Developments
- In November 2023, Nutrien Ltd. announces a strategic partnership with a leading global retailer to expand its distribution reach and gain access to new customer segments. This collaboration is expected to significantly boost the company's market presence and sales figures.
- In October 2023, EuroChem Group AG announces plans to expand its potash production capacity by 25% by 2025, aiming to become the world's largest potash producer. The expansion will involve the development of new potash mines and the modernization of existing facilities.
- In January 2023, K+S Group acquired Industrial Commodities Holdings (Pty) Ltd., a leading provider of innovative agricultural solutions. The acquisition would strengthen K+S’s position in the global agricultural industry and enhance its product portfolio, particularly in the foliar spray market. Leveraging ICH Company’s expertise in precision agriculture, K+S aims to develop advanced foliar spray solutions that optimize crop yield, improve nutrient uptake, and promote sustainable farming practices.
- In January 2022, EuroChem Group completed the acquisition of the Serra do Salitre phosphate project in Brazil. Fertilizer production is expected to launch in 2024 and reach full capacity in 2025. The size of the deal is USD 452 million.
- In July 2022, Nutrien Ltd. entered into an agreement to acquire the Brazilian company, Casa do Adubo S.A. (Casa do Adubo). The acquisition includes 39 retail locations under the brand Casa do Adubo, and 10 distribution centers, under the brand Agrodistribuidor Casa.
Market Concentration & Characteristics
The Foliar Treatment Market exhibits moderate concentration, with a mix of established global corporations and numerous regional players competing across diverse agricultural landscapes. It features strong participation from industry leaders who invest in research, innovation, and extensive distribution networks, which enables them to capture significant market share in key geographies. The market’s characteristics reflect a high degree of product differentiation, with companies developing specialized formulations to address varying crop types, climatic conditions, and regulatory requirements. It supports both large-scale commercial agriculture and smallholder farms, offering liquid and solid products suited to different user needs. The sector places a clear emphasis on sustainability, rapid nutrient delivery, and compatibility with precision agriculture technologies. The presence of regional manufacturers fosters local innovation and tailored solutions, while multinational companies drive the adoption of advanced technologies and best practices. The market’s dynamic environment encourages ongoing development and adaptation to evolving global agricultural trends.
Report Coverage
The research report offers an in-depth analysis based on Type, Physical Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market will increasingly favor bio-based and organic foliar solutions to satisfy sustainability standards.
- Integration with precision farming technologies will boost targeted application and resource efficiency.
- Advances in nanotechnology and microencapsulation will enhance nutrient delivery and product effectiveness.
- R&D collaboration between agritech companies and research institutes will accelerate innovation.
- Growing demand for multifunctional foliar products combining nutrients and crop protection agents will expand.
- Emerging markets in Asia, Latin America, and Africa will provide new growth opportunities.
- Digital platforms offering agronomic data and guidelines will support adoption among growers.
- Product development will focus on broad-spectrum stress management for drought, salinity, and heat.
- Regulatory approval processes will increasingly require evidence of environmental safety and residue-free profiles.
- Manufacturers will strengthen farmer education and technical support to improve usage outcomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption of Sustainable and High-Efficiency Crop Inputs
Farmers are increasingly seeking solutions that maximize nutrient uptake and minimize environmental impact, making foliar treatments attractive due to their direct application and reduced fertilizer runoff. This supports sustainable agriculture and helps address soil health concerns.
Technological Advancements in Formulation and Delivery
Innovations such as microencapsulation, nanotechnology, and advanced surfactants are improving the efficacy and stability of foliar treatments, making them more effective and appealing for commercial growers seeking reliable crop health solutions.
Shift Toward Precision and Data-Driven Agriculture
The integration of digital technologies, such as drones and remote sensing, enables targeted and efficient foliar applications, optimizing input use and crop response while reducing waste and costs.
Rising Demand for Bio-Based and Organic Solutions
Stricter regulations and consumer preferences for residue-free and environmentally friendly products are driving the development and adoption of bio-based and organic foliar treatments, expanding the market among producers focused on sustainability.
Expansion in Emerging Agricultural Markets
Modernization of agriculture and increasing investments in crop management in regions like Asia Pacific, Latin America, and Africa are creating new opportunities for foliar treatment adoption, especially as governments support innovation and food security initiatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Foliar Treatment Market?
What factors are driving the growth of the Foliar Treatment Market?
What are some challenges faced by the Foliar Treatment Market?
Who are the major players in the Foliar Treatment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Nutritional Foliar Sprays
- 1.2.2 Foliar Pesticides
- 1.2.3 Foliar Biostimulants
- 1.2.4 Foliar Growth Regulators
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Horticultural Crops
- 1.3.2 Field Crops
- 1.3.3 Turfs & Ornamentals
- 1.3.4 Others
- 1.4 By Physical Form
- 1.4.1 Liquid
- 1.4.2 Solid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,131.72 million → 2032: USD 25,500.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Foliar Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Foliar Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Foliar Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Foliar Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Foliar Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Foliar Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Foliar Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Foliar Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,131.72 million → 2032: USD 25,500.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Foliar Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Nutritional Foliar Sprays
- 12.3.7.2 Foliar Pesticides
- 12.3.7.3 Foliar Biostimulants
- 12.3.7.4 Foliar Growth Regulators
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Horticultural Crops
- 12.4.7.2 Field Crops
- 12.4.7.3 Turfs & Ornamentals
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Physical Form - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Liquid
- 12.5.7.2 Solid
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Foliar Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Foliar Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Foliar Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Foliar Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Corteva Agriscience
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF SE
- 18.4 Syngenta AG
- 18.5 Bayer AG
- 18.6 UPL Ltd.
- 18.7 FMC Corporation
- 18.8 Sumitomo Chemical Co. Ltd.
- 18.9 NuFarm Ltd.
- 18.10 Croda International PLC
- 18.11 Nutrien Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

