
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High Purity Pumps Market Size 2024 | USD 1,530 million |
| High Purity Pumps Market, CAGR | 5.65% |
| High Purity Pumps Market Size 2032 | USD 2,374.911 million |
Market Overview:
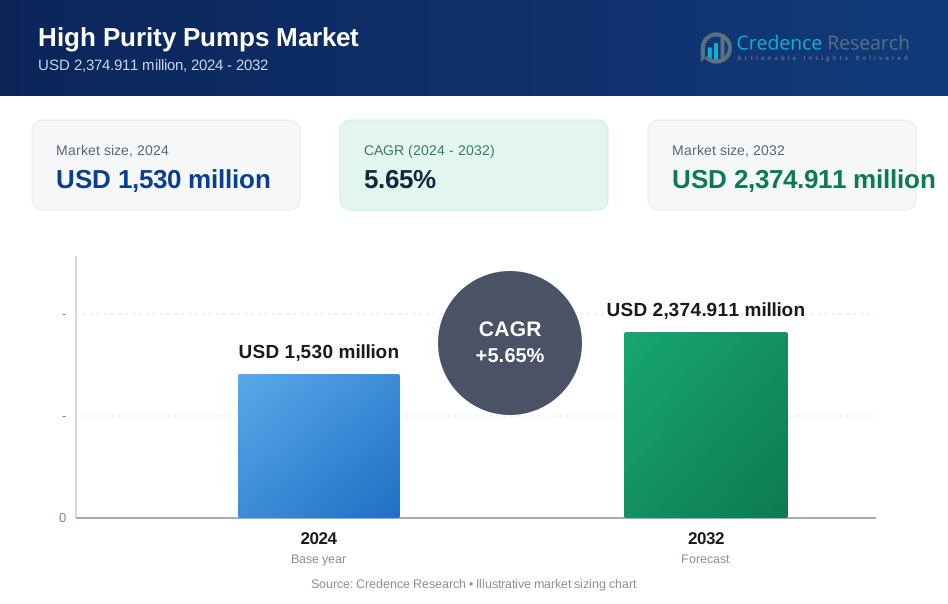
The high purity pumps market is projected to grow from USD 1,530 million in 2024 to USD 2,374.911 million by 2032, at a compound annual growth rate (CAGR) of 5.65%.
The high purity pumps market is driven by increasing demand in industries such as pharmaceuticals, biotechnology, and semiconductors, where the need for contamination-free fluid handling is critical. Advancements in cleanroom technologies and stringent regulatory requirements for maintaining high purity standards further fuel market growth. In addition, the rising adoption of high purity pumps in the food and beverage sector, driven by growing consumer demand for safe and hygienic processing, contributes to the market’s expansion. Technological innovations, including enhanced precision and energy-efficient pump designs, are also key trends shaping the market. The ongoing push for automation and smart manufacturing across industries presents new opportunities for pump manufacturers to integrate advanced monitoring systems and IoT-based solutions. Moreover, increased focus on sustainability and reducing environmental impact drives the development of pumps that ensure minimal wastage and energy consumption, solidifying the market's growth trajectory.
The high purity pumps market is geographically diverse, with North America leading the market share at 35% in 2024, driven by strong demand from the pharmaceutical and semiconductor sectors. Europe follows closely with 28%, supported by its robust pharmaceutical and biotechnology industries. The Asia-Pacific region, holding 25% market share, is the fastest-growing due to rapid industrialization in countries like China, Japan, and South Korea. The Rest of the World, including the Middle East, Africa, and Latin America, holds 12%, with growth driven by increasing healthcare and industrial development. Key players such as Watson-Marlow Fluid Technology Group (WMFTG), Graco Inc., Iwaki Co., Ltd., Verder Group, and Flowserve Corporation dominate these regions, leveraging innovation and strategic expansions to maintain their competitive edge across these diverse markets.
Market Insights:
- The high purity pumps market is projected to grow from USD 1,530 million in 2024 to USD 2,374.911 million by 2032, with a CAGR of 5.65%.
- Rising demand in the pharmaceutical, biotechnology, and semiconductor industries drives market growth due to the need for contamination-free fluid handling.
- Technological advancements, such as smart monitoring systems and energy-efficient designs, are key trends shaping the high purity pumps market.
- Increasing adoption in the food and beverage sector, driven by consumer demand for hygienic processing, contributes to market expansion.
- Industry 4.0 and automation present opportunities for manufacturers to integrate IoT-based solutions, improving operational efficiency.
- Focus on sustainability and reducing environmental impact is driving the development of energy-efficient pumps with minimal waste.
- North America leads with a 35% market share, followed by Europe at 28%, Asia-Pacific at 25%, and the Rest of the World at 12% in 2024.
Market Drivers:
Rising Demand in Pharmaceutical and Biotechnology Sectors:
The pharmaceutical and biotechnology industries are key drivers of the high purity pumps market, as these sectors require contamination-free fluid handling to maintain product integrity. For instance, Watson-Marlow's 530 series peristaltic pumps also ensure complete isolation of fluids within the tubing, thus maintaining product integrity during sensitive pharmaceutical processes. High purity pumps are essential for processing sensitive fluids such as active pharmaceutical ingredients (APIs) and biological products, where even trace amounts of contaminants can compromise quality. As global healthcare demands rise, particularly in the development and production of vaccines and biologics, the need for reliable, high-performance pumps is increasing, boosting market growth.
Stringent Regulatory Standards and Compliance:
Governments and regulatory bodies have imposed strict standards for purity and safety in industries such as pharmaceuticals, food and beverage, and semiconductors. For example, KNF Neuberger's FP 7 and FP 25 diaphragm liquid pumps, introduced in June 2024, offer extremely low pulsation with flow rates of 0.07 l/min and 0.25 l/min respectively, at maximum pressures of up to 6 bar (87 psig). High purity pumps are designed to meet these regulations, ensuring that the materials and fluids handled are free from contaminants. Compliance with standards like the FDA, GMP, and ISO is a significant market driver, as manufacturers must invest in high purity equipment to avoid non-compliance penalties. The growing regulatory scrutiny is prompting industries to adopt these advanced pumps to ensure compliance and maintain their market presence.
Technological Advancements in Pump Design:
Innovations in pump technology, including enhanced precision, energy efficiency, and smart monitoring features, are fueling the growth of the high purity pumps market. Grundfos has developed energy-efficient pumps equipped with IoT-enabled systems, allowing real-time monitoring to reduce maintenance costs and ensure uninterrupted performance. Advanced materials, such as corrosion-resistant alloys and high-grade plastics, extend the lifespan and reliability of these pumps. In addition, the integration of Internet of Things (IoT)-enabled systems allows real-time monitoring of pump performance, reducing downtime and maintenance costs, which drives demand across industries seeking efficient and cost-effective fluid handling solutions.
Increased Focus on Sustainability and Environmental Impact:
The global push for sustainable practices is another critical driver for the high purity pumps market. Verder Liquids manufactures pumps designed for low energy consumption, aligning with sustainability goals and reducing environmental impact in industrial operations. Industries are increasingly focused on reducing energy consumption and waste, and high purity pumps that offer efficiency and minimal environmental impact are gaining traction. Manufacturers are developing pumps with lower carbon footprints, which align with corporate sustainability goals and regulatory requirements, thus contributing to market expansion.
Market Trends:
Adoption of Automation and Smart Manufacturing:
A key trend in the high purity pumps market is the increasing adoption of automation and smart manufacturing technologies. For instance, Bürkert Fluid Control Systems offers IoT-enabled solutions such as the Online Analysis System, which provides real-time monitoring of parameters like pH, chlorine, and turbidity, enabling industries to optimize operations and reduce downtime through predictive maintenance strategies. Industries such as pharmaceuticals, biotechnology, and semiconductors are incorporating IoT-enabled high purity pumps to enhance operational efficiency and reduce downtime. These smart pumps offer real-time monitoring and remote diagnostics, allowing operators to track performance metrics, detect issues early, and implement predictive maintenance strategies. The integration of automation is helping manufacturers streamline processes and achieve higher productivity levels, which in turn is driving the demand for advanced high purity pumps.
Growth in the Semiconductor Industry:
The semiconductor industry is experiencing significant growth, driven by advancements in electronics, data centers, and the rise of electric vehicles. Entegris provides high precision, contamination-free pumps specifically designed for handling ultra-pure chemicals in semiconductor manufacturing processes. High purity pumps play a crucial role in the production of semiconductors, as they ensure the safe and efficient handling of ultra-pure chemicals required in the manufacturing process. The growing demand for semiconductor components has led to an increased need for high precision, contamination-free pumps that meet stringent industry requirements, positioning the semiconductor sector as a major driver of market growth.
Focus on Energy-Efficient and Eco-Friendly Solutions:
Energy efficiency and environmental sustainability are top priorities for industries utilizing high purity pumps. Iwaki Co., Ltd. develops energy-efficient high purity pumps designed to minimize operational costs and reduce environmental impact, making them ideal for industries prioritizing sustainability. Manufacturers are focusing on developing pumps that minimize energy consumption and reduce operational costs, while also aligning with environmental regulations. This trend is driving the innovation of pumps designed to reduce waste, enhance energy efficiency, and lower the carbon footprint of industrial processes, making sustainability a core factor in purchasing decisions.
Increased Applications in the Food and Beverage Industry:
The food and beverage sector are increasingly adopting high purity pumps to ensure hygienic processing and maintain product quality. Fristam Pumps USA specializes in high purity pumps that comply with food safety standards and prevent cross-contamination during processing. As consumer demand for clean-label and safe products grows, manufacturers in this sector are investing in high purity pumps to comply with safety standards and ensure contamination-free production processes.
Market Challenges Analysis:
High Initial Costs and Maintenance Expenses:
One of the key challenges in the high purity pumps market is the significant initial investment required for purchasing and installing these specialized pumps. High purity pumps, designed with advanced materials and cutting-edge technologies, often come with a higher price tag compared to conventional pumps. This can be a barrier for small and medium-sized enterprises (SMEs), especially in industries with tighter budgets. Additionally, the maintenance and servicing of these pumps can be costly due to the specialized components and expertise required. Regular calibration and cleaning are essential to ensure optimal performance and prevent contamination, further increasing the total cost of ownership. For some businesses, these expenses may outweigh the operational benefits, leading to hesitancy in adopting high purity pumps on a larger scale. Furthermore, the need for regular replacements of parts and adherence to stringent cleaning protocols makes it harder for companies to achieve long-term cost efficiencies, impacting overall profitability.
Complex Integration and Compatibility Issues:
Another challenge the high purity pumps market faces is the complexity of integrating these pumps into existing systems. Many industries operate with legacy equipment or established processes that may not be immediately compatible with the newer, more advanced high purity pump technologies. Retrofitting or upgrading older systems to accommodate high purity pumps can be both time-consuming and expensive. For example, Almatec E-Series Air-Operated Double-Diaphragm (AODD) pumps are specifically designed to handle high-purity chemicals without contamination. Moreover, ensuring that the pumps meet the specific requirements of various industries—such as chemical compatibility, temperature tolerance, and flow rate precision—adds another layer of complexity. In highly regulated industries like pharmaceuticals and semiconductors, the process of testing and validating the performance of high purity pumps can be lengthy, which can delay their widespread adoption. Addressing these integration challenges requires close collaboration between pump manufacturers and end-users to develop customized solutions that meet industry-specific needs while minimizing operational disruptions. Additionally, training personnel to handle and operate these sophisticated pumps can involve additional time and resource investments, which further complicates their seamless integration.
Market Opportunities:
The high purity pumps market presents significant growth opportunities due to the increasing demand for advanced fluid handling systems in emerging sectors such as biotechnology, pharmaceuticals, and semiconductor manufacturing. As these industries expand and focus on innovation, the need for contamination-free, reliable, and high-performance pumps continues to rise. This trend opens up opportunities for manufacturers to develop pumps with enhanced precision, durability, and energy efficiency. Additionally, the rise in biologics and personalized medicine has created a growing market for high purity pumps in pharmaceutical applications, particularly in drug production and R&D processes. Companies that can offer specialized pumps tailored to meet these evolving demands are well-positioned for growth.
Another promising opportunity lies in the growing emphasis on sustainability and energy efficiency. Industries are increasingly seeking solutions that help reduce energy consumption and environmental impact, creating a market for high purity pumps that align with these goals. Manufacturers can capitalize on this by developing eco-friendly, energy-efficient pumps that not only meet regulatory requirements but also help industries achieve their sustainability objectives. Moreover, with the advent of Industry 4.0, the integration of IoT and automation in high purity pumps offers a significant opportunity for innovation, enabling real-time monitoring and predictive maintenance. Companies that leverage these technologies to deliver smart, efficient, and environmentally conscious solutions stand to gain a competitive edge in this growing market.
Market Segmentation Analysis:
By Type The high purity pumps market is segmented by type into centrifugal, diaphragm, and peristaltic pumps, among others. Centrifugal pumps dominate the market due to their wide application in industries requiring continuous fluid transfer. However, diaphragm pumps are gaining traction for handling sensitive fluids, particularly in pharmaceutical and biotech sectors, due to their contamination-free operation.
By Material Material segmentation includes stainless steel, fluoropolymer, and engineered plastics. Stainless steel pumps hold a significant share because of their durability and resistance to corrosion in harsh environments. Fluoropolymer-based pumps are increasingly preferred for handling highly corrosive or reactive chemicals, especially in semiconductor and chemical processing industries, due to their superior chemical resistance and longer operational life.
By Application The application segment covers pharmaceuticals, biotechnology, food and beverages, and semiconductors. The pharmaceutical and biotechnology sectors lead the market, driven by the need for precise and sterile fluid handling in drug manufacturing. Semiconductor manufacturing also represents a growing segment, requiring ultra-pure fluids for contamination-free processing.
Segments:
Based on Type:
- Centrifugal Pumps
- Diaphragm Pumps
- Peristaltic Pumps
- Others
Based on Material
- Stainless Steel
- Polypropylene
- Polyvinylidene Fluoride (PVDF)
- Others
Based on Application
- Pharmaceuticals
- Biotechnology
- Food & Beverage
- Water Treatment
- Others
Based on End-User
- Pharmaceutical Companies
- Biotechnology Firms
- Food & Beverage Manufacturers
- Water Treatment Facilities
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America North America holds a significant share of the high purity pumps market, accounting for 35% of the global market share in 2024. The region's strong presence in industries such as pharmaceuticals, biotechnology, and semiconductor manufacturing is a key driver for this market. The U.S., in particular, leads the region due to its well-established pharmaceutical sector, where high purity pumps are essential for handling sensitive fluids in drug production and research. Additionally, the increasing focus on advanced manufacturing technologies and the integration of automation in production processes are further boosting the demand for high purity pumps in North America. With the rise of personalized medicine and biologics, the region is expected to continue experiencing steady growth in the high purity pumps market.
Europe Europe is another major market for high purity pumps, contributing 28% of the global market share in 2024. The region's robust pharmaceutical, biotechnology, and food and beverage sectors drive significant demand for contamination-free fluid handling systems. Countries like Germany, Switzerland, and the United Kingdom are leading in the adoption of high purity pumps due to their strong pharmaceutical manufacturing bases and stringent regulatory standards for product purity. Additionally, the region's push towards sustainability and energy efficiency is encouraging industries to invest in energy-efficient, eco-friendly pumps, creating opportunities for market expansion. The growing focus on industrial automation and cleanroom technologies further contributes to Europe's market growth.
Asia-Pacific The Asia-Pacific region is expected to see the fastest growth in the high purity pumps market, with a market share of 25% in 2024. The region's rapid industrialization, particularly in countries like China, Japan, and South Korea, is a major driver for this growth. The expanding pharmaceutical and semiconductor industries in these countries are creating substantial demand for high purity pumps to ensure contamination-free processing. China, in particular, is emerging as a key market due to its growing investment in pharmaceutical manufacturing and the semiconductor sector. Additionally, the rise of automation and smart manufacturing technologies across the region is further accelerating the adoption of high purity pumps.
Rest of the World The Rest of the World (RoW) region, including the Middle East, Africa, and Latin America, holds a smaller share of the global high purity pumps market, accounting for 12% in 2024. However, the market in these regions is expected to grow steadily due to the increasing development of the pharmaceutical and biotechnology sectors, particularly in countries like Brazil and Saudi Arabia. Investments in healthcare infrastructure and industrial development are driving the demand for high purity pumps, especially in fluid handling applications that require stringent quality standards. As more industries in these regions adopt advanced technologies and automation, the demand for high purity pumps is expected to rise in the coming years.
Key Player Analysis:
- Flowserve Corporation
- Tapflo Group
- Verder Group
- Yamada Corporation
- IDEX Corporation
- Sundyne Corporation
- Parker Hannifin Corporation
- Graco Inc.
- Watson-Marlow Fluid Technology Group (WMFTG)
- KNF Neuberger GmbH
- Iwaki Co., Ltd.
Competitive Analysis:
The high purity pumps market is highly competitive, with leading players such as Watson-Marlow Fluid Technology Group (WMFTG), Graco Inc., Iwaki Co., Ltd., Verder Group, Flowserve Corporation, Yamada Corporation, KNF Neuberger GmbH, IDEX Corporation, Parker Hannifin Corporation, Sundyne Corporation, and Tapflo Group dominating the landscape. These companies are focusing on product innovation, expanding their portfolios to meet the rising demand for precision, contamination-free fluid handling systems across various industries, including pharmaceuticals, biotechnology, semiconductors, and food and beverage. To stay competitive, market leaders are also investing in advanced technologies such as IoT-enabled smart pumps and energy-efficient designs, allowing for real-time monitoring and operational efficiency. Verder Group has introduced energy-efficient high purity pumps integrated with IoT capabilities, enabling real-time diagnostics to reduce maintenance costs and downtime. Additionally, strategic mergers, acquisitions, and partnerships are common among these players as they aim to strengthen their market position and expand their global reach. As a result, the competitive environment is characterized by continuous innovation, increasing focus on sustainability, and the adoption of advanced manufacturing processes.
Recent Developments:
- In March 2024, Sulzer announced the opening of a new state-of-the-art test and assembly center in Mexico City, adjacent to its existing pump production facility. The new center features a 10-meter-deep hydraulics test bed for large pumps, a digital monitoring system, and a dedicated packaging room.
- In July 2024, Flowserve acquired the intellectual property and in-process R&D of NexGen Cryogenic Solutions’ cryogenic LNG submerged pump technology. This acquisition aims to enhance Flowserve's LNG product offerings, focusing on decarbonization and efficiency improvements in the LNG value chain
Market Concentration & Characteristics:
The high purity pumps market exhibits a moderate to high level of concentration, with a few key players holding significant market shares. Companies such as Watson-Marlow Fluid Technology Group (WMFTG), Graco Inc., and Flowserve Corporation dominate the industry due to their strong product portfolios, technological innovations, and established global presence. These leading manufacturers are consistently investing in research and development to enhance pump performance, energy efficiency, and reliability, while also expanding their market reach through strategic mergers and acquisitions. The market is characterized by a high demand for specialized pumps designed to handle sensitive fluids in industries like pharmaceuticals, biotechnology, and semiconductors. Strict regulatory standards and a growing focus on sustainability further shape market dynamics, requiring manufacturers to develop contamination-free, energy-efficient pumps that meet stringent quality requirements. As competition intensifies, product innovation, customization, and adherence to regulatory compliance are critical for maintaining a competitive edge.
Report Coverage:
The research report offers an in-depth analysis based on Type, Material, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The high purity pumps market is expected to experience steady growth due to rising demand from the pharmaceutical and biotechnology industries.
- Increasing investments in semiconductor manufacturing will further boost the adoption of high purity pumps.
- Technological advancements, including IoT-enabled pumps, will enhance operational efficiency and create new opportunities.
- The growing focus on energy efficiency and sustainability will drive the demand for eco-friendly, energy-efficient pump designs.
- Strict regulatory standards in industries such as pharmaceuticals and food processing will continue to shape market requirements.
- Manufacturers are likely to focus on expanding their product portfolios to meet evolving customer needs.
- Automation and smart manufacturing trends will support the integration of advanced monitoring systems in high purity pumps.
- Asia-Pacific is expected to see the fastest market growth due to industrialization and increased pharmaceutical manufacturing.
- Customization of pumps to suit specific industry requirements will become a key differentiator for manufacturers.
- Strategic mergers, acquisitions, and partnerships will be common as companies aim to strengthen their market presence globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the High Purity Pumps market?
What factors are driving the growth of the High Purity Pumps market?
What are some challenges faced by the High Purity Pumps market?
Who are the major players in the High Purity Pumps market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 High Purity Pumps Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global High Purity Pumps Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,530 million → 2032: USD 2,374.911 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 High Purity Pumps Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. High Purity Pumps Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 High Purity Pumps Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 High Purity Pumps Market Drivers
- 3.3 High Purity Pumps Market Restraints & Challenges
- 3.4 High Purity Pumps Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 High Purity Pumps Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 High Purity Pumps Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, High Purity Pumps category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 High Purity Pumps Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. High Purity Pumps Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the High Purity Pumps market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 High Purity Pumps Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 High Purity Pumps Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 High Purity Pumps Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in High Purity Pumps (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New High Purity Pumps Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global High Purity Pumps Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America High Purity Pumps Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe High Purity Pumps Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific High Purity Pumps Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America High Purity Pumps Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East High Purity Pumps Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa High Purity Pumps Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. High Purity Pumps Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
