
Market Overview
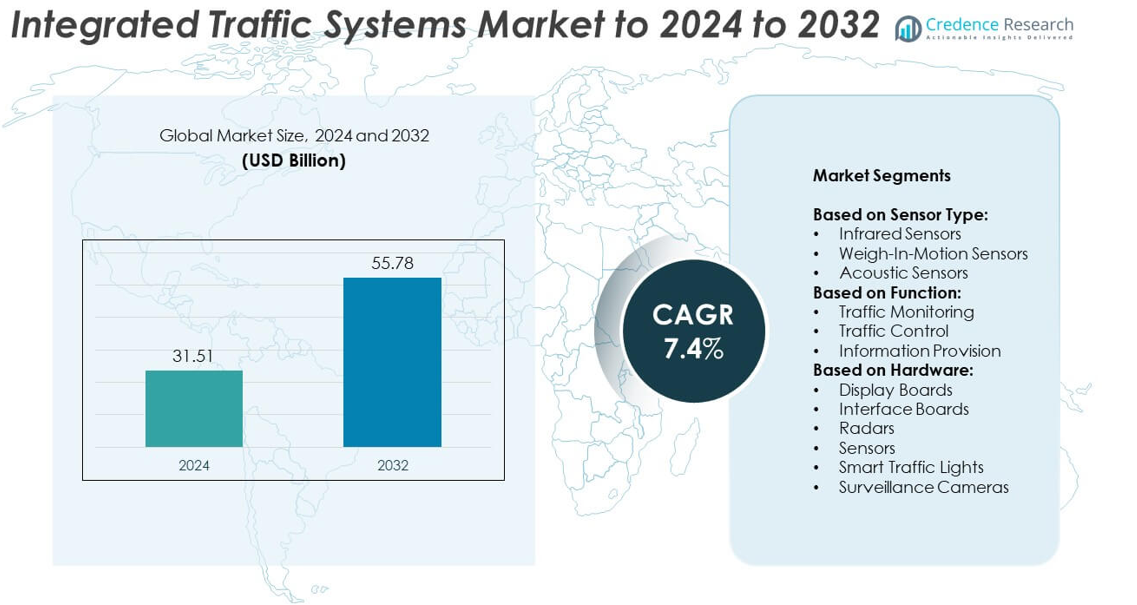
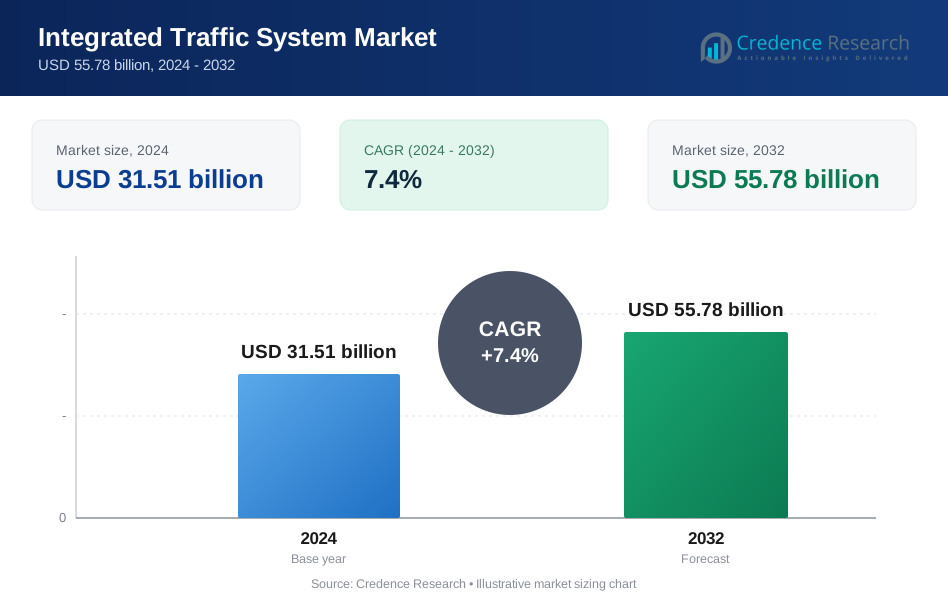
The Integrated Traffic Systems Market size was valued at USD 31.51 billion in 2024 and is anticipated to reach USD 55.78 billion by 2032, at a CAGR of 7.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Integrated Traffic Systems Market Size 2024 | USD 31.51 billion |
| Integrated Traffic Systems Market, CAGR | 7.4% |
| Integrated Traffic Systems Market Size 2032 | USD 55.78 billion |
The Integrated Traffic Systems Market is highly competitive, with leading players such as Iteris, Siemens, LG CNS, Swarco, KapschTrafficCom, Cubic, Jenoptik, Cisco, Flir, and Sumitomo driving innovation through advanced IoT, AI, and data analytics integration. These companies focus on expanding smart mobility solutions, adaptive traffic lights, and real-time monitoring platforms to meet growing urban mobility demands. Regional dynamics highlight North America as the dominant market, holding 34% share in 2024, supported by large-scale smart city investments and government funding. Europe follows with strong adoption driven by sustainability goals, while Asia Pacific is set to witness the fastest growth.
Market Insights
- The Integrated Traffic Systems Market was valued at USD 31.51 billion in 2024 and is projected to reach USD 55.78 billion by 2032, growing at a CAGR of 7.4%.
- Rising urbanization, congestion issues, and government-backed smart city projects are fueling strong adoption of intelligent traffic solutions across global markets.
- Key trends include the integration of IoT and AI for real-time traffic monitoring, as well as the emergence of connected vehicle communication systems enhancing safety and efficiency.
- The market is highly competitive, with global leaders focusing on adaptive traffic lights, surveillance systems, and advanced analytics, while regional players target cost-effective solutions for emerging economies.
- North America led with 34% share in 2024, followed by Europe at 28% and Asia Pacific at 25%, with Asia Pacific expected to record the fastest growth; infrared sensors held the largest segment share, supporting system efficiency in adaptive traffic management.
Market Segmentation Analysis:
By Sensor Type
Infrared sensors held the dominant share in the Integrated Traffic Systems Market in 2024, capturing nearly 38% of the segment. Their wide adoption is driven by reliability in detecting vehicle presence and motion in varying light and weather conditions. These sensors are vital in adaptive signal control and lane management applications. Growing demand for real-time traffic analytics and congestion reduction supports their integration. Meanwhile, weigh-in-motion sensors and acoustic sensors are expanding in freight management and urban noise monitoring, though their adoption trails behind infrared-based solutions.
- For instance, Teledyne FLIR's FC T2-Series thermal traffic camera is designed to operate in extreme temperatures, with an operating temperature range of (-50) to 75) degrees Celsius
By Function
Traffic monitoring accounted for the largest share of the function segment, representing about 42% of the market in 2024. Continuous vehicle tracking, congestion mapping, and accident detection make monitoring indispensable for urban road networks. Rising smart city initiatives and government-led safety programs further strengthen this sub-segment. Traffic control systems, including adaptive signal management, are also gaining momentum with increasing urbanization. Information provision, such as dynamic signboards and traveler alerts, plays a complementary role but holds a smaller portion compared to the dominance of monitoring solutions.
- For instance, Sensys Networks' wireless sensor systems for traffic management have been implemented in over 80 countries and 40 U.S. states.
By Hardware
Smart traffic lights emerged as the leading hardware sub-segment, holding around 36% share of the hardware category in 2024. Their dominance stems from the rising demand for adaptive signal control to reduce traffic congestion and emissions. Integration of sensors and AI-based analytics enhances real-time responsiveness, driving adoption across smart city projects worldwide. Surveillance cameras are also expanding rapidly due to their dual role in security enforcement and traffic management. Display boards, interface boards, radars, and stand-alone sensors remain critical, but their uptake is largely tied to supporting infrastructure investments.
Key Growth Drivers
Rising Urbanization and Congestion Management
Rapid urbanization and increasing vehicle ownership are intensifying traffic congestion worldwide, creating strong demand for integrated traffic systems. Governments are prioritizing intelligent traffic solutions to optimize vehicle flow, reduce travel times, and enhance commuter safety. Advanced systems such as adaptive signal control and smart traffic lights are being deployed in metropolitan areas. This driver is key to shaping market expansion, as smart city programs across Asia-Pacific, Europe, and North America continue to invest heavily in traffic optimization infrastructure to address urban mobility challenges.
- For instance, the Orange County Transportation Authority's Regional Traffic Signal Synchronization Program (RTSSP), which has involved various contractors including Iteris, has optimized signal timing on over 3,500 intersections. As a result, the program has achieved a 13% average travel time savings and reduced fuel consumption by more than 70 million gallons.
Government Smart City Initiatives
Government-backed smart city initiatives are a critical growth driver, accelerating the adoption of integrated traffic management solutions. Countries are deploying advanced monitoring systems, surveillance cameras, and data-driven traffic control technologies to improve public safety and urban mobility. Financial incentives, infrastructure grants, and public-private partnerships are fueling investments in digital mobility platforms. These initiatives not only promote traffic efficiency but also align with global sustainability goals by reducing emissions. As cities expand, government policies remain central to pushing large-scale integration of advanced traffic technologies.
- For instance, Miovision’s Opticom AI software claims it can reduce emergency response times by up to 25% and cut intersection crash risk by up to 70%-which implies handling large volumes of sensitive traffic and location data securely.
Technological Advancements in IoT and AI
The integration of IoT and AI in traffic systems is emerging as a key driver of growth. AI-powered algorithms enable real-time data analysis, predictive modeling, and automated traffic control, improving operational efficiency. IoT sensors provide continuous monitoring across road networks, feeding data into centralized platforms. These advancements support demand for adaptive traffic lights, congestion alerts, and smart surveillance systems. Increasing affordability of connected technologies further accelerates adoption, making IoT and AI crucial for scaling intelligent traffic solutions across both developed and emerging markets.
Key Trends & Opportunities
Adoption of Connected Vehicle Integration
A major trend shaping the market is the integration of connected vehicles with traffic systems. Vehicle-to-infrastructure (V2I) communication allows real-time exchange of data between vehicles and road systems, improving traffic coordination and reducing collision risks. Automakers and traffic authorities are collaborating to deploy these technologies under smart mobility projects. This opportunity is expected to expand as 5G connectivity becomes more widespread, providing seamless data transfer and enabling more efficient and safer urban transport environments.
- For instance, Siemens Mobility has deployed ~525 roadside units (RSUs) across 2,200 km of Austrian highways for cooperative intelligent transport systems.
Expansion of Sustainable Mobility Solutions
Sustainability goals are driving opportunities for integrated traffic systems designed to reduce emissions and energy use. Smart traffic lights and adaptive monitoring systems are being optimized to lower fuel consumption through reduced idling times. Cities across Europe and Asia are investing in eco-friendly traffic solutions to support climate targets. This trend is opening opportunities for vendors to offer energy-efficient hardware and software solutions, aligning with government regulations and corporate sustainability commitments, while meeting public demand for greener urban mobility.
- For instance, Audi’s Traffic Light Information system, which includes the Green Light Optimized Speed Advisory (GLOSA) feature, works with over 22,000 connected intersections in more than 60 U.S. cities and metropolitan areas, as of 2021.
Key Challenges
High Deployment and Maintenance Costs
A key challenge in the integrated traffic systems market is the high cost of deployment and maintenance. Advanced systems require significant upfront investment in infrastructure, hardware, and software integration, which may strain municipal budgets. Regular upgrades and ongoing technical support add to long-term expenses, limiting adoption in developing regions. While public-private partnerships are helping bridge funding gaps, affordability remains a barrier for widespread implementation, especially in smaller cities and low-income economies seeking to modernize traffic infrastructure.
Data Security and Privacy Concerns
The increased reliance on IoT and AI technologies raises significant concerns around data security and privacy. Continuous data collection from vehicles, cameras, and sensors exposes traffic systems to potential cyberattacks and misuse of personal information. Ensuring secure communication protocols and compliance with data protection regulations is critical. Failure to address these issues may hinder public acceptance and slow adoption rates. Vendors are under pressure to invest in robust cybersecurity solutions, making privacy concerns a persistent challenge for the industry’s growth trajectory.
Regional Analysis
North America
North America held the largest share of the Integrated Traffic Systems Market in 2024, accounting for 34%. The region benefits from advanced infrastructure, strong government funding, and widespread adoption of smart city projects. The United States leads with large-scale deployment of smart traffic lights, surveillance systems, and AI-based monitoring solutions. Canada is also investing in digital mobility technologies to enhance safety and reduce emissions. Increasing congestion in metropolitan areas and rising vehicle ownership drive further demand. Public-private partnerships and supportive policies ensure North America maintains its leadership through technological innovation and early adoption of connected solutions.
Europe
Europe captured 28% of the Integrated Traffic Systems Market share in 2024, supported by its strong commitment to sustainability and urban mobility. Countries such as Germany, the United Kingdom, and France are leading in smart traffic management adoption. European Union policies promoting emission reduction and road safety boost market growth. Large investments in adaptive signal control and vehicle-to-infrastructure communication enhance traffic efficiency across major cities. Surveillance cameras and radars are widely deployed for both traffic and security purposes. Continued investments in eco-friendly infrastructure and connected vehicle technologies strengthen Europe’s position as a major market contributor.
Asia Pacific
Asia Pacific accounted for 25% of the Integrated Traffic Systems Market share in 2024, driven by rapid urbanization and large-scale government investments in smart city initiatives. China, Japan, and India are at the forefront of implementing intelligent traffic solutions to address congestion and pollution. Growing vehicle ownership and infrastructure expansion fuel demand for adaptive traffic lights, sensors, and real-time monitoring systems. The region’s focus on digitalization and integration of IoT and AI technologies further accelerates adoption. Asia Pacific is expected to record the fastest growth rate, supported by population density and government-backed transportation modernization programs.
Latin America
Latin America held 7% of the Integrated Traffic Systems Market share in 2024, with growing adoption in countries such as Brazil, Mexico, and Chile. The region is witnessing rising investments in urban mobility projects, driven by increasing congestion in major cities. Smart traffic lights and surveillance cameras are gradually being integrated into public infrastructure to improve safety and efficiency. However, high deployment costs and budgetary constraints limit widespread adoption. Public-private partnerships and international funding are supporting gradual improvements. As urbanization accelerates, Latin America presents opportunities for vendors targeting cost-effective and scalable traffic system solutions.
Middle East and Africa
The Middle East and Africa represented 6% of the Integrated Traffic Systems Market share in 2024, with adoption primarily concentrated in the Gulf Cooperation Council countries. Nations such as the United Arab Emirates and Saudi Arabia are investing heavily in smart city projects as part of long-term development visions. Infrastructure upgrades focus on advanced traffic monitoring, smart lighting, and real-time data systems. In Africa, adoption remains limited to major urban centers due to financial and infrastructural challenges. However, ongoing projects supported by international organizations create opportunities for gradual expansion in traffic system deployment.
Market Segmentations:
By Sensor Type:
- Infrared Sensors
- Weigh-In-Motion Sensors
- Acoustic Sensors
By Function:
- Traffic Monitoring
- Traffic Control
- Information Provision
By Hardware:
- Display Boards
- Interface Boards
- Radars
- Sensors
- Smart Traffic Lights
- Surveillance Cameras
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The Integrated Traffic Systems Market is characterized by strong competition among leading players such as Iteris, Siemens, LG CNS, Swarco, KapschTrafficCom, Cubic, Jenoptik, Cisco, Flir, and Sumitomo. These companies compete through technological innovation, strategic partnerships, and large-scale project deployments across global markets. Vendors are focusing on integrating advanced IoT, AI, and data analytics solutions into traffic systems to enhance efficiency and safety. Expansion into emerging economies is becoming a strategic priority, supported by government-led smart city initiatives and infrastructure modernization programs. The competitive environment is also shaped by sustainability goals, pushing providers to develop energy-efficient hardware and software platforms. Intense rivalry encourages continuous investments in R&D, ensuring product differentiation and improved system reliability. Regional players in developing markets pose competition by offering cost-effective solutions, although global companies maintain an advantage through their broader portfolios and strong global presence. This dynamic landscape ensures steady innovation and market growth opportunities worldwide.
Key Player Analysis
Recent Developments
- In 2025, Kapsch TrafficCom Continued to refine its business portfolio with the deconsolidation of several smaller companies (e.g., in South Africa and Belarus), streamlining operations to focus on core markets in tolling and traffic management.
- In 2025, SWARCO Acquired a key German traffic management software firm (Heusch/Boesefeldt in August 2025). This move was explicitly aimed at strategically expanding its technological expertise in customized software solutions for traffic and tunnel management systems and strengthening its position in Cooperative, Connected, and Automated Mobility (CCAM).
- In 2023, Iteris, Inc. Unveiled the enhanced VantageCare program, transforming its support into a cloud-enabled managed service (Performance Assist) for its traffic detection systems. Continued to highlight its Vantage Vector and other sensor platforms, emphasizing sensor fusion (combining video and radar data) for reliable detection
Report Coverage
The research report offers an in-depth analysis based on Sensor Type, Function, Hardware and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rapid adoption of smart city initiatives worldwide.
- Increasing vehicle ownership will drive demand for advanced traffic monitoring solutions.
- Integration of AI and IoT will enhance real-time traffic control efficiency.
- Connected vehicle technologies will support safer and more coordinated road networks.
- Governments will invest heavily in adaptive traffic lights and surveillance systems.
- Sustainability goals will promote eco-friendly and energy-efficient traffic solutions.
- Public-private partnerships will fund large-scale deployment of intelligent traffic systems.
- Emerging economies will witness rising adoption despite cost-related challenges.
- Cybersecurity advancements will address growing concerns around data protection.
- The market will see faster growth in Asia Pacific due to urbanization and infrastructure expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Congestion Management
Rapid urbanization and increasing vehicle ownership are intensifying congestion in cities, prompting governments to invest in integrated traffic systems that optimize vehicle flow, reduce travel times, and enhance commuter safety.
Government Smart City Initiatives
Government-backed smart city projects are accelerating the deployment of intelligent traffic management solutions, with financial incentives and public-private partnerships fueling investments in digital mobility and advanced monitoring technologies.
Technological Advancements in IoT and AI
The integration of IoT sensors and AI-powered analytics enables real-time traffic monitoring, predictive modeling, and automated control, significantly improving operational efficiency and supporting the adoption of adaptive traffic lights and smart surveillance.
Adoption of Connected Vehicle Integration
The emergence of vehicle-to-infrastructure (V2I) communication is enabling real-time data exchange between vehicles and road systems, improving traffic coordination, reducing collision risks, and supporting the development of safer, more efficient urban transport networks.
Expansion of Sustainable Mobility Solutions
Sustainability goals are driving demand for integrated traffic systems that reduce emissions and energy use, with cities investing in eco-friendly traffic lights and adaptive monitoring to support climate targets and regulatory requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Integrated Traffic Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Integrated Traffic Systems Market projected to grow between 2025 and 2032?
What are the main drivers of the Integrated Traffic System Market?
How do technological advancements impact the traffic management system?
Which regions are leading the Integrated Traffic System Market?
How do electric and autonomous vehicles contribute to the market's growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Function
- 1.2.1 Traffic Monitoring
- 1.2.2 Traffic Control
- 1.2.3 Information Provision
- 1.3 By Hardware
- 1.3.1 Smart Traffic Lights
- 1.3.2 Surveillance Cameras
- 1.3.3 Display Boards
- 1.3.4 Interface Boards
- 1.3.5 Radars
- 1.3.6 Sensors
- 1.4 By Sensor Type
- 1.4.1 Infrared Sensors
- 1.4.2 Weigh-In-Motion Sensors
- 1.4.3 Acoustic Sensors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 31.51 billion → 2032: USD 55.78 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Integrated Traffic System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Integrated Traffic System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Integrated Traffic System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Integrated Traffic System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Integrated Traffic System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Integrated Traffic System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Integrated Traffic System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Integrated Traffic System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 31.51 billion → 2032: USD 55.78 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Integrated Traffic System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Function - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traffic Monitoring
- 12.3.7.2 Traffic Control
- 12.3.7.3 Information Provision
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Hardware - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smart Traffic Lights
- 12.4.7.2 Surveillance Cameras
- 12.4.7.3 Display Boards
- 12.4.7.4 Interface Boards
- 12.4.7.5 Radars
- 12.4.7.6 Sensors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sensor Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Infrared Sensors
- 12.5.7.2 Weigh-In-Motion Sensors
- 12.5.7.3 Acoustic Sensors
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Integrated Traffic System Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Integrated Traffic System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Integrated Traffic System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Iteris
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Siemens
- 17.4 LG CNS
- 17.5 Swarco
- 17.6 KapschTrafficCom
- 17.7 Cubic
- 17.8 Jenoptik
- 17.9 Cisco
- 17.10 Flir
- 17.11 Sumitomo
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

