
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Integrated Photovoltaic (PV) System Market Size 2024 | USD 15,952.29 million |
| Integrated Photovoltaic (PV) System Market, CAGR | 12.68% |
| Integrated Photovoltaic (PV) System Market Size 2032 | USD 44,274.27 million |
Market Overview
Integrated Photovoltaic (PV) System Market size was valued at USD 8,180.30 million in 2018 to USD 15,952.29 million in 2024 and is anticipated to reach USD 44,274.27 million by 2032, at a CAGR of 12.68% during the forecast period.
The Integrated Photovoltaic (PV) System Market is experiencing robust growth driven by increasing demand for clean and renewable energy solutions, rising government support through incentives and regulatory frameworks, and growing emphasis on sustainable construction practices. Rapid urbanization and expansion of smart city initiatives have accelerated the adoption of integrated PV systems in residential, commercial, and industrial sectors. Technological advancements have enhanced efficiency and lowered costs, making PV systems more accessible to a wider range of end users. Trends indicate a shift toward building-integrated photovoltaics (BIPV), where solar panels are seamlessly embedded into roofs, facades, and windows, supporting both energy generation and modern architectural design. Growing environmental awareness and stringent emission regulations further support market expansion. The integration of PV systems with smart grids and energy storage solutions also represents a key trend, enabling optimized energy management and resilience in power supply for urban and remote applications.
The Integrated Photovoltaic (PV) System Market exhibits strong regional diversification, with significant activity in North America, Europe, and Asia Pacific driven by robust policy support, rising adoption of renewable energy, and urban infrastructure development. North America and Europe benefit from advanced regulatory frameworks and widespread green building initiatives, while Asia Pacific experiences rapid growth fueled by large-scale solar projects and expanding urbanization, particularly in China, Japan, and India. Latin America, the Middle East, and Africa also present emerging opportunities as governments pursue energy diversification and sustainable urban planning. Leading players in the market include AGC Solar, renowned for its building-integrated photovoltaic solutions, NanoPV Solar Inc., specializing in high-efficiency thin film technologies, and Heliatek GmbH, a pioneer in organic solar film. These companies, along with firms like Hanergy Holding Group Limited, drive innovation and expand the reach of integrated PV systems across diverse geographies.
[caption id="attachment_98018" align="aligncenter" width="822"]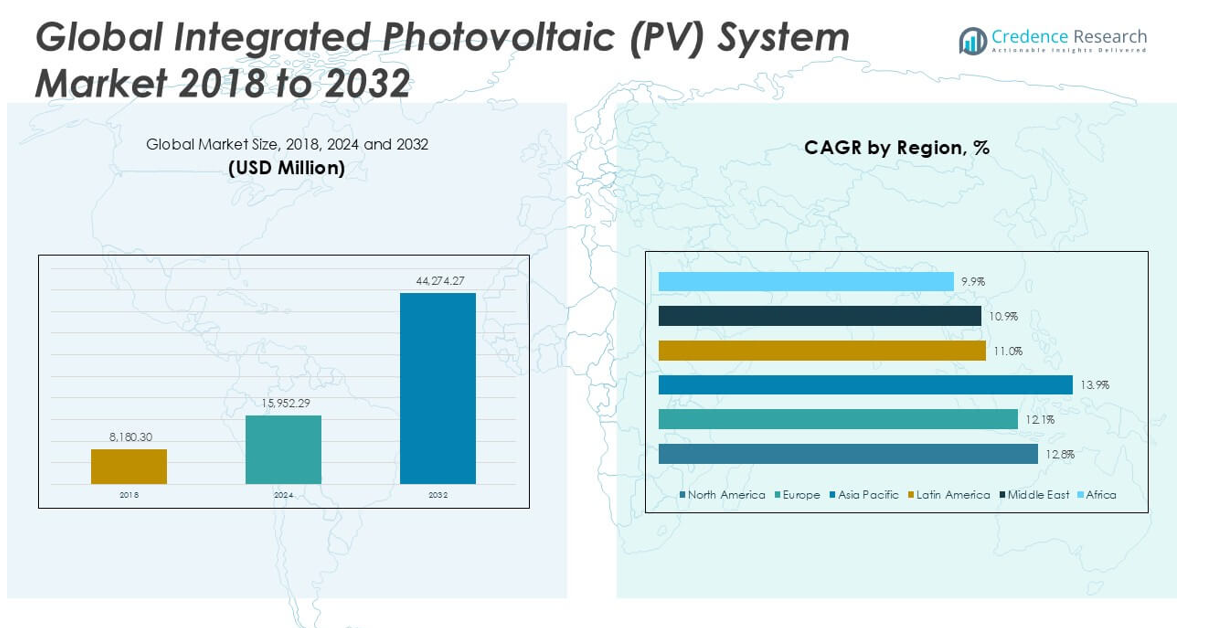 Integrated Photovoltaic (PV) System Market Size[/caption]
Market Insights
- The Integrated Photovoltaic (PV) System Market is valued at USD 15,952.29 million in 2024 and projected to reach USD 44,274.27 million by 2032, growing at a CAGR of 12.68%.
- Growing demand for renewable energy and supportive government policies drive rapid adoption of integrated PV systems in new and existing buildings.
- Building-integrated photovoltaics (BIPV) represent a major trend, with solar panels seamlessly embedded in roofs, facades, and windows for both energy generation and aesthetic enhancement.
- Key players such as AGC Solar, NanoPV Solar Inc., and Heliatek GmbH focus on technological advancements, efficient product offerings, and expansion into new markets to maintain competitive advantage.
- High initial investment costs, technical complexities in retrofitting, and regulatory barriers challenge market penetration in some regions.
- Asia Pacific leads growth with large-scale deployments in China, Japan, and India, while North America and Europe benefit from advanced regulatory frameworks and urban infrastructure development.
- The market continues to evolve with innovations in PV materials, energy management solutions, and strategic collaborations between technology providers and construction companies.
Market Drivers
Rising Demand for Renewable Energy Sources Drives Market Expansion
The Integrated Photovoltaic (PV) System Market benefits significantly from a global shift toward renewable energy adoption. Governments and organizations prioritize the reduction of carbon emissions, creating a strong foundation for PV system integration in new and existing infrastructures. Public awareness about climate change and the necessity for sustainable solutions continues to grow, fueling investments in solar energy technologies. Many countries offer incentives, subsidies, and policy frameworks that directly support the implementation of integrated PV systems. Urbanization and growing electricity consumption increase the need for clean, distributed power generation. It helps bridge the gap between conventional energy sources and the urgent need for sustainability. These factors collectively support the widespread adoption of integrated PV systems in various sectors.
- For instance, the International Energy Agency reported that the world added over 600 gigawatts of solar PV capacity in the last decade.
Government Policies and Regulatory Support Strengthen Market Fundamentals
Supportive government policies remain a primary market driver for the Integrated Photovoltaic (PV) System Market. Mandatory green building codes and renewable portfolio standards encourage property developers and businesses to adopt PV solutions. Tax incentives, feed-in tariffs, and grants reduce initial investment barriers, improving project feasibility. It receives a significant boost from long-term targets set by national energy strategies, aiming to increase renewable energy’s share in the overall energy mix. International agreements and regional initiatives encourage market participants to focus on environmentally friendly power generation. Supportive regulations accelerate PV system deployment in both residential and commercial spaces. Regulatory backing builds investor confidence and attracts significant capital inflows into the market.
- For instance, the European Commission’s Renewable Energy Directive has set binding national targets for all EU countries, spurring the construction of thousands of renewable energy projects.
Technological Advancements Enhance System Efficiency and Accessibility
Continuous innovation in photovoltaic materials and system design elevates the competitiveness of the Integrated Photovoltaic (PV) System Market. Advancements in cell efficiency, lightweight modules, and flexible designs enable seamless integration into building materials. It has led to the emergence of building-integrated photovoltaics (BIPV), transforming rooftops and facades into power-generating assets. These technological improvements reduce installation and maintenance costs, improving return on investment. Standardization of components and growing use of automation simplify system deployment. Research and development focus on durability and aesthetics, making PV solutions more appealing for architects and developers. Improved system reliability and enhanced performance accelerate market growth.
Increasing Urbanization and Smart City Initiatives Propel Market Adoption
The Integrated Photovoltaic (PV) System Market aligns closely with rising urbanization trends and the rapid expansion of smart cities. Urban centers require innovative approaches to address energy demands and environmental concerns. It offers an efficient means to integrate clean energy into urban infrastructure without consuming additional land. Municipalities and developers incorporate PV systems into new buildings and public projects to meet sustainability goals. Smart grid deployment and the need for decentralized energy generation further enhance market potential. Integration with storage solutions and digital management platforms optimizes energy use across city networks. This alignment with modern urban planning and green architecture continues to drive the market forward.
Market Trends
Growing Integration of Photovoltaics in Building Architecture Shapes Market Evolution
The Integrated Photovoltaic (PV) System Market is witnessing a strong trend toward the seamless incorporation of solar technologies into building materials and design. Building-integrated photovoltaics (BIPV) replace conventional construction elements, such as facades, windows, and roofs, with functional solar components that generate power. This trend aligns with modern architectural preferences and supports green building certifications. It appeals to property developers, architects, and sustainability consultants who seek both energy efficiency and aesthetic value in projects. Market participants introduce customizable PV modules, allowing for flexible installation across diverse building types. Innovations in transparent and semi-transparent solar panels further expand integration possibilities. This trend transforms buildings from passive structures to active contributors to renewable energy generation.
- For instance, according to the Fraunhofer Institute, over 20,000 buildings in Europe now use BIPV technology. This trend aligns with modern architectural preferences and supports green building certifications.
Increasing Adoption of Smart Energy Management and Storage Solutions
The integration of PV systems with advanced energy management and storage technologies marks a significant trend in the Integrated Photovoltaic (PV) System Market. Smart inverters, monitoring platforms, and battery storage systems enable real-time control and optimization of energy use. It supports efficient energy balancing, peak shaving, and resilience during grid interruptions, making PV systems more attractive for urban and remote applications. Utilities and consumers benefit from improved grid stability and the ability to maximize self-consumption of solar power. Digital platforms empower users to monitor system performance and make data-driven decisions. Growing focus on distributed energy resources encourages the deployment of integrated PV systems with robust storage capabilities. This trend paves the way for more intelligent and autonomous energy networks.
- For instance, Wood Mackenzie reported that more than five hundred thousand residential battery systems were installed worldwide last year, many paired with PV systems.
Advancements in PV Materials and Manufacturing Technologies Drive Market Differentiation
Continuous improvements in photovoltaic cell technology, module durability, and manufacturing processes influence trends within the Integrated Photovoltaic (PV) System Market. Innovations in thin-film, perovskite, and organic PV materials enable lighter, more versatile, and higher-efficiency solutions. It results in modules that can adapt to non-traditional surfaces and challenging environmental conditions. Enhanced manufacturing techniques reduce production costs and enable scalable deployment for both small- and large-scale projects. Companies invest in research and development to address performance and longevity, positioning PV systems as reliable long-term assets. The trend toward environmentally friendly and recyclable materials aligns with global sustainability objectives. These technological advancements support market differentiation and growth.
Rise of Policy-Driven Urban and Industrial Applications Expands Market Reach
The Integrated Photovoltaic (PV) System Market sees growing adoption in urban and industrial environments, driven by regulatory mandates and sustainability targets. Municipal governments and private sector stakeholders pursue net-zero energy goals by integrating PV systems into public infrastructure, industrial facilities, and large-scale commercial projects. It supports the transition to low-carbon cities and promotes energy independence. The trend extends to applications such as transportation hubs, warehouses, and data centers, where large surfaces allow for significant power generation. Incentive programs and green procurement policies fuel this expansion, making PV systems a core component of future-proof infrastructure. Widespread urban and industrial deployment further solidifies the market’s role in global energy transformation.
Market Challenges Analysis
High Initial Investment and Complexity in Integration Hinder Market Growth
The Integrated Photovoltaic (PV) System Market faces significant challenges due to the high initial investment required for advanced PV modules and system integration. Upfront costs often deter developers and building owners, particularly in regions where subsidies or incentives remain limited. Complexities in retrofitting existing buildings with integrated PV systems add further financial and technical barriers. It demands specialized design, engineering, and skilled labor, driving project costs higher. Regulatory compliance and adherence to strict building codes increase project timelines and expenses. Uncertainty around long-term returns makes potential investors cautious, slowing market penetration in cost-sensitive segments. The industry must address cost reduction and streamline integration processes to accelerate widespread adoption.
Technical Limitations and Environmental Constraints Impact System Performance
Operational and technical hurdles present ongoing challenges for the Integrated Photovoltaic (PV) System Market. Variability in solar resource availability due to geographic and climatic factors affects system output and reliability. It requires careful site selection and system design to optimize energy generation. Architectural constraints, shading, and structural load limits reduce the effectiveness of PV integration in certain projects. Interconnection issues with existing electrical infrastructure and limited compatibility with legacy systems further complicate deployment. Maintenance requirements, durability concerns, and evolving standards introduce risks for long-term performance. These technical and environmental challenges necessitate continued innovation and tailored solutions for sustainable market growth.
[caption id="attachment_98019" align="aligncenter" width="843"]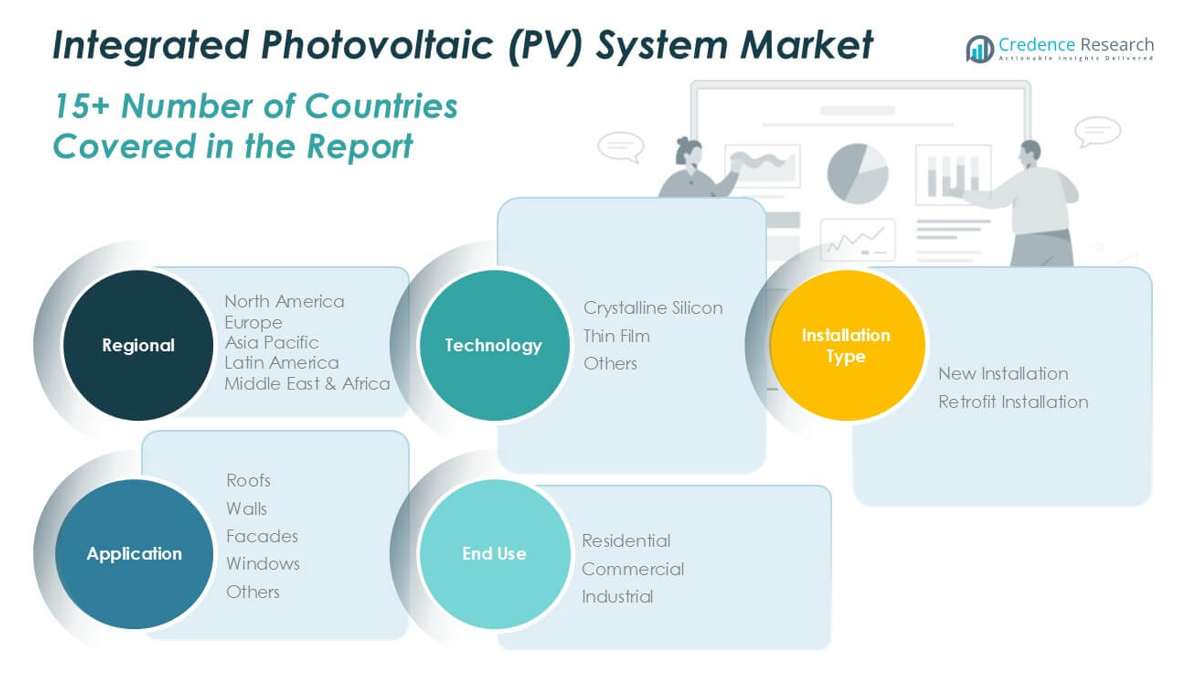 Integrated Photovoltaic (PV) System Market segmentation[/caption]
Market Opportunities
Expansion of Green Building Initiatives and Urban Development Fuels Market Potential
The Integrated Photovoltaic (PV) System Market stands to benefit from the growing momentum behind green building initiatives and large-scale urban development projects. Cities worldwide prioritize sustainable construction practices and implement policies that favor renewable energy adoption. It offers developers a compelling solution to meet energy efficiency standards and achieve green certifications, such as LEED and BREEAM. Emerging markets with rapid urbanization present new opportunities for integrated PV systems in both residential and commercial buildings. Public and private sector investment in smart cities and eco-friendly infrastructure expands the market’s addressable scope. Projects that combine energy generation with innovative architecture position integrated PV as a core component of future urban landscapes.
Technological Innovations and Hybrid System Integration Open New Revenue Streams
Advancements in PV materials, system design, and digital energy management unlock fresh opportunities for the Integrated Photovoltaic (PV) System Market. Breakthroughs in flexible, lightweight, and transparent modules enable application in non-traditional surfaces and diverse climatic regions. It allows for seamless integration with other distributed energy resources, such as battery storage and smart grid technologies, optimizing energy consumption and resilience. Research and development investments yield products that appeal to both commercial clients and consumers seeking modern, sustainable solutions. Collaboration with technology providers and utility companies drives the deployment of hybrid systems in industrial, agricultural, and remote settings. These innovations create new business models and revenue streams for market participants.
Market Segmentation Analysis:
By Technology:
The Integrated Photovoltaic (PV) System Market demonstrates strong performance across distinct technology segments, with crystalline silicon holding a prominent position due to its high efficiency, durability, and established manufacturing base. Crystalline silicon modules remain the preferred choice for most commercial and residential applications because they deliver reliable output and a long service life. Thin film technology appeals to projects requiring flexibility, lightweight construction, or installation on unconventional surfaces. It finds application in architectural projects where aesthetics and versatility are critical. The "Others" category covers emerging technologies such as organic photovoltaics and multi-junction cells, which attract interest in niche and experimental deployments but currently represent a small portion of overall market revenue.
- For instance, BloombergNEF found that global production of crystalline silicon solar modules exceeded 150,000,000 units last year, supplying a wide range of commercial and residential projects.
By Installation Type:
The market divides into new installations and retrofit installations. New installation projects drive the bulk of market activity, fueled by global construction of energy-efficient buildings and large-scale infrastructure development. It enables seamless incorporation of PV systems into building designs from the outset, maximizing both performance and integration with structural elements. Retrofit installation serves existing buildings, offering property owners a means to improve energy efficiency and reduce operating costs. It presents unique challenges due to structural limitations, design compatibility, and cost factors, but regulatory support and energy cost savings sustain interest in this segment.
- For instance, the U.S. Department of Energy highlighted that more than 40,000 new buildings integrated PV systems in the last reporting year.
By Application:
Application analysis reveals that roofs constitute the dominant segment in the Integrated Photovoltaic (PV) System Market, reflecting widespread acceptance of solar rooftops in residential, commercial, and industrial environments. Roof-based systems provide ample surface area for effective solar energy capture and support compliance with modern building codes. Walls, facades, and windows follow as architects and engineers embrace building-integrated photovoltaics to blend renewable energy generation with advanced aesthetics. It enables the development of energy-positive buildings that meet both functional and visual requirements. The "Others" application segment includes specialty installations on canopies, shading systems, and unique architectural features, broadening the scope of market adoption and driving innovation in product design.
Segments:
Based on Technology:
- Crystalline Silicon
- Thin Film
- Others
Based on Installation Type:
- New Installation
- Retrofit Installation
Based on Application:
- Roofs
- Walls
- Facades
- Windows
- Others
Based on End Use (Component):
- Residential
- Commercial
- Industrial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Integrated Photovoltaic (PV) System Market
North America Integrated Photovoltaic (PV) System Market grew from USD 1,753.36 million in 2018 to USD 3,346.87 million in 2024 and is projected to reach USD 9,342.09 million by 2032, reflecting a compound annual growth rate (CAGR) of 12.8%. North America is holding a 21% market share. The United States leads the region with strong policy frameworks, tax credits, and increasing adoption of solar technologies across commercial and residential buildings. Canada follows with a focus on clean energy investments and government-backed sustainability programs. Mexico is seeing gradual growth supported by solar-friendly climates and improving regulatory conditions. Rising demand for energy-efficient construction and building-integrated PV solutions propels market expansion in major metropolitan areas. The presence of key industry players supports ongoing innovation and wider deployment of integrated PV systems.
Europe Integrated Photovoltaic (PV) System Market
Europe Integrated Photovoltaic (PV) System Market grew from USD 3,251.26 million in 2018 to USD 6,177.09 million in 2024 and is anticipated to reach USD 16,435.61 million by 2032, with a CAGR of 12.1%. Europe accounts for 37% of the global market share. Germany, France, and the United Kingdom drive adoption through stringent environmental regulations, attractive feed-in tariffs, and ambitious net-zero targets. Solar mandates in new construction projects accelerate market growth, particularly in urban environments. Italy and Spain also contribute through robust renewable energy programs. The European Union’s emphasis on green building standards and energy independence sustains long-term market potential. Technological advancements and cross-border collaborations foster the integration of advanced PV solutions across the continent.
Asia Pacific Integrated Photovoltaic (PV) System Market
Asia Pacific Integrated Photovoltaic (PV) System Market grew from USD 2,342.39 million in 2018 to USD 4,825.25 million in 2024 and is projected to reach USD 14,615.82 million by 2032, posting a CAGR of 13.9%. Asia Pacific holds a 33% market share. China dominates the region with large-scale urban projects and investments in renewable technologies. Japan and South Korea implement advanced smart city initiatives and government incentives to boost PV integration. India sees rapid growth in commercial and industrial sectors, supported by national solar missions and urban expansion. Southeast Asian countries such as Australia and Singapore show rising adoption in both public and private infrastructure. The region’s high solar resource potential and population density drive sustained demand for integrated PV systems.
Latin America Integrated Photovoltaic (PV) System Market
Latin America Integrated Photovoltaic (PV) System Market grew from USD 397.24 million in 2018 to USD 765.28 million in 2024 and is expected to reach USD 1,886.65 million by 2032, with a CAGR of 11.0%. Latin America represents 4% of the global market share. Brazil leads the regional market, leveraging abundant solar resources and favorable regulatory reforms. Chile and Mexico also experience growth through government auctions and the introduction of new solar policies. Colombia and Argentina are emerging markets with increasing focus on distributed solar solutions and sustainable urban planning. Cost-effective project development and the availability of large commercial surfaces support broader market adoption. National and regional programs encourage ongoing investment in integrated PV technology.
Middle East Integrated Photovoltaic (PV) System Market
Middle East Integrated Photovoltaic (PV) System Market grew from USD 289.09 million in 2018 to USD 525.36 million in 2024 and is set to reach USD 1,281.01 million by 2032, at a CAGR of 10.9%. The Middle East holds a 3% market share. The United Arab Emirates and Saudi Arabia drive regional adoption with ambitious renewable energy targets and investments in flagship smart city projects such as Masdar City and NEOM. Qatar and Israel contribute through supportive government initiatives and research in high-efficiency PV modules. The region’s high solar irradiance and the drive to diversify energy sources accelerate the deployment of integrated PV systems. Government-backed pilot programs in urban infrastructure support market development and awareness.
Africa Integrated Photovoltaic (PV) System Market
Africa Integrated Photovoltaic (PV) System Market grew from USD 146.96 million in 2018 to USD 312.44 million in 2024 and is forecasted to reach USD 713.08 million by 2032, recording a CAGR of 9.9%. Africa accounts for 2% of the global market share. South Africa leads with established renewable energy policies and incentives for PV integration in commercial and public buildings. Egypt and Morocco are investing in solar projects and public-private partnerships to boost market presence. Nigeria and Kenya are emerging markets leveraging solar PV to address electrification challenges and reduce dependence on traditional energy sources. Distributed generation and off-grid solar solutions drive market growth across rural and peri-urban regions. International development funds and local government initiatives stimulate demand for integrated PV systems.
Key Player Analysis
- AGC Solar
- NanoPV Solar Inc.
- Heliatek GmbH
- ISSOL SA
- Dow Solar
- BIPVco Limited
- Carmanah Technologies Corporation
- Ertex solartechnik GmbH
- Hanergy Holding Group Limited
- Solaxness
Competitive Analysis
The competitive landscape of the Integrated Photovoltaic (PV) System Market features leading players such as AGC Solar, NanoPV Solar Inc., Heliatek GmbH, ISSOL SA, Dow Solar, BIPVco Limited, Carmanah Technologies Corporation, Ertex solartechnik GmbH, Hanergy Holding Group Limited, and Solaxness. These companies compete by focusing on product innovation, advanced technology portfolios, and strategic market expansion. Many market participants emphasize the development of thin film and flexible photovoltaic technologies to address the needs of modern architecture and urban infrastructure. Companies compete by expanding their global reach, enhancing manufacturing capabilities, and providing turnkey solutions that support seamless integration into both new constructions and retrofit projects. Collaborative ventures with construction firms, technology providers, and energy companies strengthen market positions and foster product differentiation. Competitive pressures drive continuous improvement in cost structure, performance, and sustainability, ultimately accelerating market adoption across residential, commercial, and industrial sectors. The focus remains on delivering reliable, visually appealing, and high-performing integrated PV systems that meet evolving client requirements.
Recent Developments
- In February 2025, Microquanta launched the world's largest building-integrated photovoltaic (BIPV) project, harnessing perovskite panels, at the University Student Entrepreneurship Center in Shanxi. The installation, perched atop the translucent roof of the center in Shenchi County, Shanxi Province, boasts a capacity of 17.92 kWp. The double-glass perovskite modules, each measuring 1,200 mm x 1,000 mm, are engineered for a light transmittance of approximately 40%.
- In February 2025, Avancis unveiled its newest module series for building-integrated photovoltaics (BIPV), signaling a shift from traditional thin-film technology. The newly launched Skala Matrix range harnesses crystalline solar technology, boasting superior output compared to the Skala Prime panels, which utilize CIGS technology. However, the Skala Prime panels continue to be offered in the lineup.
- In October 2024, AGC Glass Europe and ROSI entered into a strategic partnership to enhance circularity in the glass industry. This collaboration focuses on recycling end-of-life photovoltaic (PV) panels to produce high-purity raw materials for flat glass manufacturing. By utilizing cullet from solar panel cover glass, AGC aims to reduce greenhouse gas emissions and conserve virgin materials in glass production.
- In July 2024, LONGi and Kingspan formed a strategic partnership to collaborate on Integrated (BIPV) and Applied (BAPV) solar PV systems, potentially including joint manufacturing and marketing efforts. Kingspan's expertise in high-performance insulation and building envelope solutions complements LONGi's leadership in solar technology. The partnership aims to provide compatible, tested systems to support customers in achieving Net-Zero Energy goals in the construction sector.
Market Concentration & Characteristics
The Integrated Photovoltaic (PV) System Market demonstrates moderate market concentration with a mix of established global manufacturers and innovative niche players competing for market share. It features a diverse landscape, with companies differentiating through technology, customization, and integration capabilities. The market’s characteristics include rapid technological advancements, a strong focus on research and development, and a trend toward building-integrated solutions that merge energy generation with architectural design. Regulatory support, sustainability goals, and urbanization drive demand, while cost sensitivity and technical challenges shape market entry. It attracts investment from both established energy firms and new entrants seeking to capitalize on growing interest in renewable energy and green buildings. Product offerings often emphasize durability, efficiency, and visual appeal, aligning with evolving customer expectations. Regional dynamics, such as policy frameworks and construction trends, further influence competitive strategies and market development. The market’s adaptability and emphasis on innovation continue to shape its evolution and future growth prospects.
Report Coverage
The research report offers an in-depth analysis based on Technology, Installation Type, Application, End Use (Component)and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Integrated Photovoltaic (PV) System Market is projected to grow significantly, driven by increasing demand for sustainable energy solutions and advancements in photovoltaic technologies.
- Government incentives and supportive policies are encouraging the adoption of integrated PV systems in both residential and commercial sectors.
- Technological innovations, such as the development of flexible and transparent solar panels, are expanding the applications of integrated PV systems in modern architecture.
- The integration of PV systems into building materials is enhancing the aesthetic appeal and functionality of structures, leading to increased market acceptance.
- Challenges such as high initial installation costs and technical complexities in retrofitting existing buildings may hinder market growth in certain regions.
- Asia Pacific is expected to lead the market growth, with countries like China, Japan, and India investing heavily in renewable energy infrastructure.
- Europe and North America are also anticipated to witness substantial growth due to stringent environmental regulations and increasing awareness of sustainable building practices.
- The market is characterized by a mix of established players and emerging startups, fostering a competitive environment that drives innovation and cost reduction.
- Collaborations between technology providers, construction companies, and government bodies are crucial in overcoming market barriers and promoting widespread adoption.
- Continuous research and development efforts are expected to improve the efficiency and affordability of integrated PV systems, further propelling market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Incentives and Regulatory Support
Mandatory green building codes, renewable portfolio standards, and financial incentives such as tax credits and feed-in tariffs are accelerating the adoption of integrated PV systems in both new and existing buildings, making projects more financially viable and attractive to developers.
Technological Advancements in PV Materials and Design
Continuous innovation in photovoltaic cell efficiency, lightweight and flexible modules, and building-integrated solutions is reducing costs and expanding the range of applications, enabling seamless integration into modern architecture and increasing market accessibility.
Urbanization and Smart City Initiatives
Rapid urban growth and the expansion of smart city projects are driving demand for integrated PV systems as cities seek sustainable, decentralized energy solutions that can be embedded into urban infrastructure without consuming additional land.
Stringent Environmental Regulations and Sustainability Goals
Increasingly strict emission regulations and global sustainability targets are compelling property developers and industries to adopt integrated PV systems to meet energy efficiency standards and achieve green building certifications.
Integration with Smart Grids and Energy Storage
The growing trend of coupling PV systems with smart grid technologies and energy storage solutions is enhancing energy management, grid resilience, and self-consumption, making integrated PV systems more attractive for both urban and remote applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Integrated Photovoltaic (PV) System Market?
What factors are driving the growth of the Integrated Photovoltaic (PV) System Market?
What are some challenges faced by the Integrated Photovoltaic (PV) System Market?
Who are the major players in the Integrated Photovoltaic (PV) System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Technology
- 1.3.1 Crystalline Silicon
- 1.3.2 Thin Film
- 1.3.3 Others
- 1.4 By Application
- 1.4.1 Roofs
- 1.4.2 Walls
- 1.4.3 Facades
- 1.4.4 Windows
- 1.4.5 Others
- 1.5 By Installation Type
- 1.5.1 New Installation
- 1.5.2 Retrofit Installation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,952.29 million → 2032: USD 44,274.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Integrated Photovoltaic (PV) System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Integrated Photovoltaic (PV) System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Integrated Photovoltaic (PV) System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Integrated Photovoltaic (PV) System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Integrated Photovoltaic (PV) System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Integrated Photovoltaic (PV) System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Integrated Photovoltaic (PV) System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Integrated Photovoltaic (PV) System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,952.29 million → 2032: USD 44,274.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Integrated Photovoltaic (PV) System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Crystalline Silicon
- 12.4.7.2 Thin Film
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Roofs
- 12.5.7.2 Walls
- 12.5.7.3 Facades
- 12.5.7.4 Windows
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Installation Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 New Installation
- 12.6.7.2 Retrofit Installation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Integrated Photovoltaic (PV) System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Integrated Photovoltaic (PV) System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Integrated Photovoltaic (PV) System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Integrated Photovoltaic (PV) System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AGC Solar
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 NanoPV Solar Inc.
- 18.4 Heliatek GmbH
- 18.5 ISSOL SA
- 18.6 Dow Solar
- 18.7 BIPVco Limited
- 18.8 Carmanah Technologies Corporation
- 18.9 Ertex solartechnik GmbH
- 18.10 Hanergy Holding Group Limited
- 18.11 Solaxness
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

