
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
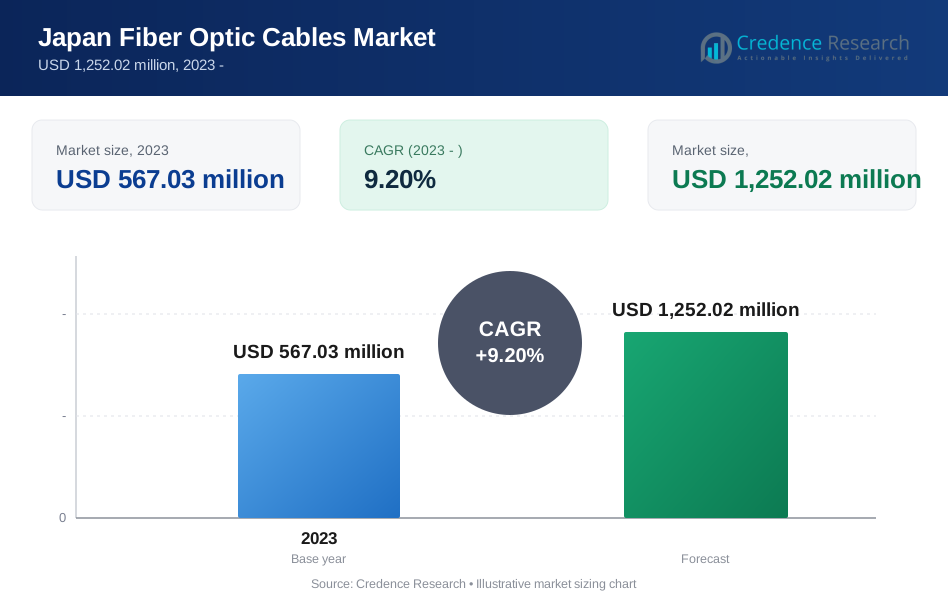
| Japan Fiber Optic Cables Market Size 2023 | USD 567.03 Million |
| Japan Fiber Optic Cables Market, CAGR | 9.20% |
| Japan Fiber Optic Cables Market Size 2032 | USD 1,252.02 Million |
Market Overview
The Japan Fiber Optic Cables Market is projected to grow from USD 567.03 million in 2023 to USD 1,252.02 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.20%.
The Japan Fiber Optic Cables Market is driven by increasing demands for high-speed internet connectivity and robust investment in telecommunications infrastructure. The rising adoption of fiber to the home (FTTH) and expanding 5G networks are key factors accelerating market growth. Additionally, technological advancements in fiber optic technology, alongside government initiatives to enhance digital infrastructure, are propelling the market forward. These trends, coupled with Japan's strategic push towards greater bandwidth and lower latency in communications, are setting a dynamic pace for the expansion of the fiber optic cables market in the region.
The Japan Fiber Optic Cables Market is a dynamic segment within the Asia-Pacific region, characterized by advanced technological infrastructure and robust demand for high-speed data communication systems. Key players such as Corning Inc., Sumitomo Electric Industries Ltd., and Furukawa Electric Co. Ltd., dominate the market, driving innovation and supply. These companies are pivotal in deploying state-of-the-art fiber optic solutions across various applications, from telecommunications to industrial networks. Their presence underlines Japan's strategic role in the global fiber optics landscape, supported by a strong domestic market and export capabilities.
Market Drivers
Rapid Digitalization and Broadband Expansion
The Japanese market is witnessing a transformative phase with significant investments in telecommunications infrastructure to bolster rapid digitalization and broadband expansion. For instance, Japan is experiencing significant growth in broadband adoption, with the number of broadband subscribers reaching 43.8 million. Of these, 36.6 million are FTTH subscribers, highlighting the widespread deployment of fiber optic networks. This strategic upgrade aims to enhance connectivity and support burgeoning digital needs across the nation. Key initiatives include the widespread deployment of Fiber-to-the-Home (FTTH) networks, ensuring high-speed internet access is available to both households and businesses, thus creating a robust foundation for digital services and applications.
Advancements in 5G Network Deployment
The rollout of 5G networks is a critical driver, demanding high-bandwidth solutions to manage increased data from applications like virtual reality, augmented reality, and autonomous driving technologies. For example, a consortium in Japan achieved the world’s first demonstration of 5G communication from an altitude of 4km using the 38GHz band. Fiber optic cables, known for their high capacity and low latency, are becoming the backbone of these 5G infrastructures. Their ability to handle extensive data traffic efficiently makes them indispensable in the development and expansion of next-generation network technologies.
Integration with Data Centers and Cloud Computing
As the adoption of cloud computing escalates and the number of data centers grows, there is a consequent surge in data traffic, which further propels the demand for high-capacity fiber optic cables. These cables are pivotal in linking data centers and cloud platforms, ensuring seamless, efficient, and fast data transmission and storage solutions that are critical for modern computing needs.
Enhancement of Smart Cities and IoT Integration
The expansion of smart cities and the integration of IoT devices necessitate a reliable and high-speed network infrastructure. Fiber optic cables meet these requirements by providing the essential bandwidth and reliability to support a vast array of connected devices. Furthermore, their resilience makes them a preferred choice for maintaining communication and supporting emergency responses during natural disasters, thus ensuring continuity and effective disaster management.
Market Trends
Expanding Capacities and Technological Enhancements
The Japan Fiber Optic Cables Market is experiencing significant transformations with a strategic shift towards higher-core-count cables, driven by the escalating need for bandwidth due to increasing data traffic. For instance, the market is witnessing rapid advancements in fiber optic technology, including the development of new fiber types such as bend-insensitive and low-loss fibers. These cables offer cost-efficient solutions by maximizing fiber utilization, effectively meeting the growing demands of modern telecommunications. Concurrently, the market is witnessing rapid advancements in fiber optic technology, including the development of new fiber types such as bend-insensitive and low-loss fibers, which enhance network performance and reliability. Additionally, Wavelength Division Multiplexing (WDM) technology is being increasingly adopted, allowing for multiple data streams to be transmitted simultaneously over a single fiber, thereby boosting network capacity.
Integration with Emerging Technologies and Sustainable Practices
The integration of fiber optic cables with cutting-edge wireless technologies, such as Fiber-to-the-Antenna (FTTA), is broadening the scope of high-speed internet connectivity, merging the benefits of optical and wireless networks. This is complemented by advancements in optical networking technologies, including coherent optical systems and optical amplifiers, which are pivotal in enhancing the performance and scalability of fiber networks. Moreover, there is a growing focus on sustainability and energy efficiency within the sector. Manufacturers and network operators are prioritizing the development of energy-efficient components and adopting sustainable practices, such as recycling and waste reduction, to mitigate environmental impacts. The role of the private sector is also becoming increasingly prominent, as competition and innovation spurred by private investments lead to the rapid deployment of fiber optic infrastructure, especially in areas previously underserved, thus shaping a dynamic and forward-looking market landscape.
Market Challenges Analysis
Market Dynamics and Competitive Landscape
The Japan Fiber Optic Cables Market faces considerable challenges from international competition. These players introduce advanced products and services, intensifying the competitive environment and exerting significant price pressure on local manufacturers. This scenario challenges Japanese firms to innovate while maintaining profitability. Concurrently, the market is susceptible to economic uncertainties. For instance, between March 2023 and March 2024, the exports of Japan’s Optical fibers and cables have decreased by ¥-1.31B (-36.9%) from ¥3.55B to ¥2.24B, while imports decreased by ¥-21.9M (-2.15%) from ¥1.02B to ¥996M. These fluctuations in global economic conditions, including trade disputes and downturns, directly impact the demand for fiber optic cables.
Infrastructure and Regulatory Hurdles
Deploying fiber optic infrastructure, especially in less accessible rural or mountainous regions, presents logistical challenges marked by high costs and operational complexity. Issues such as land acquisition and the extensive permitting process add layers of difficulty, prolonging project timelines. Moreover, the rapid pace of technological advancements poses a dual threat: keeping abreast with emerging trends and the risk of obsolescence. As new technologies surface, existing infrastructures may require substantial upgrades or complete overhauls, leading to significant investment demands. Environmental concerns also play a critical role, as the deployment activities could disrupt local ecosystems and wildlife habitats, necessitating stringent sustainability measures. Adding to these operational challenges is a complex regulatory framework specific to the industry, including compliance with data privacy laws and industry standards, which not only complicates business operations but also adds to the cost burdens faced by manufacturers and network operators in the fiber optic cable sector.
Market Segmentation Analysis:
By Fiber Type:
The Japan Fiber Optic Cables Market is segmented by fiber type into single-mode fiber, multi-mode fiber, and others. Single-mode fibers, known for their ability to transmit optical signals over long distances without much attenuation, dominate the market due to their extensive use in telecommunications and broadband networks. Multi-mode fibers, although offering higher bandwidth over shorter distances, cater primarily to data center applications, industrial, and campus settings where high data transmission rates are required over moderate distances. The 'others' category includes specialized fibers designed for niche applications, showcasing the market's versatility and alignment with emerging technological needs.
By Cable Design:
In terms of cable design, the market features a variety of configurations including ribbon tube, loose tube, tight buffered, central core, and others. Ribbon tube cables are preferred in high-density applications and mass-fusion splicing, making them ideal for network upgrades and expansions. Loose tube cables, offering high crush resistance and the ability to expand and contract with temperature changes, are widely used in outdoor environments. Tight buffered cables are favored for their durability and ease of handling in indoor applications, such as within buildings or across campuses. Central core designs, typically used in high-performance data communication systems, provide robust protection for the fiber cores. The 'others' segment includes custom designs tailored to specific industrial requirements, highlighting the market's adaptability to diverse operational demands.
Segments:
Based on Fiber Type:
- Single-mode Fiber
- Multi-mode Fiber
- Others
Based on Cable Design:
- Ribbon Tube
- Loose Tube
- Tight Buffered
- Central Core
- Others
Based on Deployment:
- Underground
- Underwater
- Aerial
- Others
Based on End-use:
- IT & Telecommunication
- Energy & Power
- Healthcare
- Aerospace & Defense
- Others
Based on the Region:
- Kanto region
- Chubu region
- Kansai region
- Kyushu region
- Tohoku
- Chugoku
- Shikoku
Regional Analysis
Kanto region
The Kanto region, which includes Tokyo and its surrounding prefectures, holds the largest market share at approximately 40% of Japan's fiber optic cables market value. This dominance is largely due to the region's high population density, advanced technological infrastructure, and the presence of major telecommunications companies and data centers. Tokyo, as the country's economic and technological hub, drives significant demand for high-speed internet and data transmission capabilities. The region's focus on smart city initiatives, 5G network expansion, and the growing number of tech-savvy businesses further fuels the demand for fiber optic cables. Additionally, the preparations for the digital transformation of various industries in Kanto contribute to the steady growth of the fiber optic cable market in this region.
Chubu region
The Chubu region, centered around Nagoya and encompassing several central Japanese prefectures, accounts for about 25% of the country's fiber optic cables market share. This region's significant market presence is attributed to its strong manufacturing base, particularly in the automotive and aerospace industries, which increasingly rely on high-speed data transmission for their operations. Chubu's focus on industrial IoT applications and the development of smart factories drive the demand for robust fiber optic networks. The region also benefits from government initiatives to improve connectivity in semi-urban and rural areas, leading to extensive fiber optic cable installations. Furthermore, Chubu's growing importance as a data center location, due to its geographical position and relatively lower disaster risks compared to other regions, contributes to the increasing demand for fiber optic infrastructure in this area.
Key Player Analysis
- Corning Inc.
- Finisar Corporation
- Prysmian Group
- Sumitomo Electric Industries Ltd
- Leoni AG (Weinert Industries)
- HTGD
- Sterlite Tech
- Furukawa Electric Co Ltd.
Competitive Analysis
In the Japan Fiber Optic Cables Market, the competitive landscape is shaped by leading players including Corning Inc., Sumitomo Electric Industries Ltd., Furukawa Electric Co. Ltd., Finisar Corporation, Prysmian Group, Leoni AG, HTGD, and Sterlite Tech. These companies significantly contribute to the market's dynamics through continuous technological advancements and strategic partnerships. Their competitive edge is enhanced by extensive R&D activities and comprehensive product portfolios that meet diverse industry needs. The competition is further intensified by their efforts to expand their footprint and capacity, not only in Japan but globally, leveraging Japan’s reputation for quality and innovation. This competitive environment fosters a market that is constantly evolving, with each player striving to improve fiber optic technology and deployment techniques to better serve an increasingly digital and connected world.
Recent Developments
- In August 2024, Corning Inc. reached a supply agreement with Lumen Technologies for a substantial supply of next-generation optical cable.
- In March 2024, Prysmian Group’s full suite of fiber optic cable products met the ‘Build America, Buy America’ requirements and was available to ship.
- In July 2024, Sterlite Tech introduced its Optical Connectivity portfolio for the US market.
- In April 2024, Sterlite Tech launched a series of optical fiber cables–Rapid–to add to its “In America, For America” portfolio.
- In May 2022, Weinert Industries completed the acquisition procedure of the Fiber Optics Unit from Leoni AG.
Market Concentration & Characteristics
The Japan Fiber Optic Cables Market is characterized by a moderate to high level of market concentration, with a few key players dominating the industry. These leading companies, such as Corning Inc., Sumitomo Electric Industries Ltd., and Furukawa Electric Co. Ltd., hold significant market shares due to their established brand reputations, technological expertise, and comprehensive product portfolios. This concentration enhances their ability to influence market trends and pricing strategies significantly. The market's characteristics are defined by a strong focus on innovation and sustainability, driving advancements in fiber optic technology that cater to the increasing demands for high-speed data transmission and network reliability. Additionally, strategic collaborations and mergers among top players are common, aiming to leverage each other's strengths to enhance market presence and operational efficiencies. This dynamic market structure supports robust competition and continuous improvement, making Japan a critical player in the global fiber optics arena.
Report Coverage
The research report offers an in-depth analysis based on Fiber Type, Cable Design, Deployment, End-use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in demand for high-speed internet services will drive expansion in the fiber optic cables market.
- Increased investments in 5G infrastructure will significantly boost the need for high-capacity fiber optic cables.
- Expansion of IoT and smart city projects will escalate the requirement for advanced fiber optic networks.
- Innovations in fiber optic technology, such as development of more efficient and durable fibers, are expected to enhance market offerings.
- Government initiatives aimed at improving digital infrastructure will provide sustained support for the fiber optic cables market.
- Efforts to extend fiber connectivity to rural and remote areas will open new market opportunities.
- Environmental sustainability concerns will lead to the adoption of greener manufacturing practices and eco-friendly materials.
- Partnerships and collaborations between major players and tech companies will enhance product development and distribution channels.
- The market will face challenges from alternative technologies but remain resilient due to the unmatched capacity and reliability of fiber optics.
- Ongoing advancements in network security solutions will integrate with fiber optic deployments to address rising cybersecurity concerns.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Fiber Optic Cables Market?
What factors are driving the growth of the Japan Fiber Optic Cables Market?
What are the key segments within the Japan Fiber Optic Cables Market?
What are some challenges faced by the Japan Fiber Optic Cables Market?
Who are the major players in the Japan Fiber Optic Cables Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Fiber Optic Cables Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Fiber Optic Cables Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (the forecast period) (2023: USD 567.03 million → forecast year: USD 1,252.02 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Fiber Optic Cables Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Fiber Optic Cables Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Fiber Optic Cables Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Fiber Optic Cables Market Drivers
- 3.3 Japan Fiber Optic Cables Market Restraints & Challenges
- 3.4 Japan Fiber Optic Cables Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Fiber Optic Cables Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Fiber Optic Cables Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Fiber Optic Cables category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Fiber Optic Cables Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Fiber Optic Cables Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Fiber Optic Cables market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Fiber Optic Cables Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Fiber Optic Cables Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Fiber Optic Cables Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Fiber Optic Cables (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Fiber Optic Cables Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Fiber Optic Cables Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Fiber Optic Cables Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Fiber Optic Cables Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Fiber Optic Cables Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Fiber Optic Cables Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Fiber Optic Cables Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Fiber Optic Cables Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Fiber Optic Cables Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
