
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Knitting Machines Market Size 2024 | USD 11,860.398 Million |
| Knitting Machines Market, CAGR | 6.84% |
| Knitting Machines Market Size 2032 | USD 20,135.86 Million |
Market Overview:
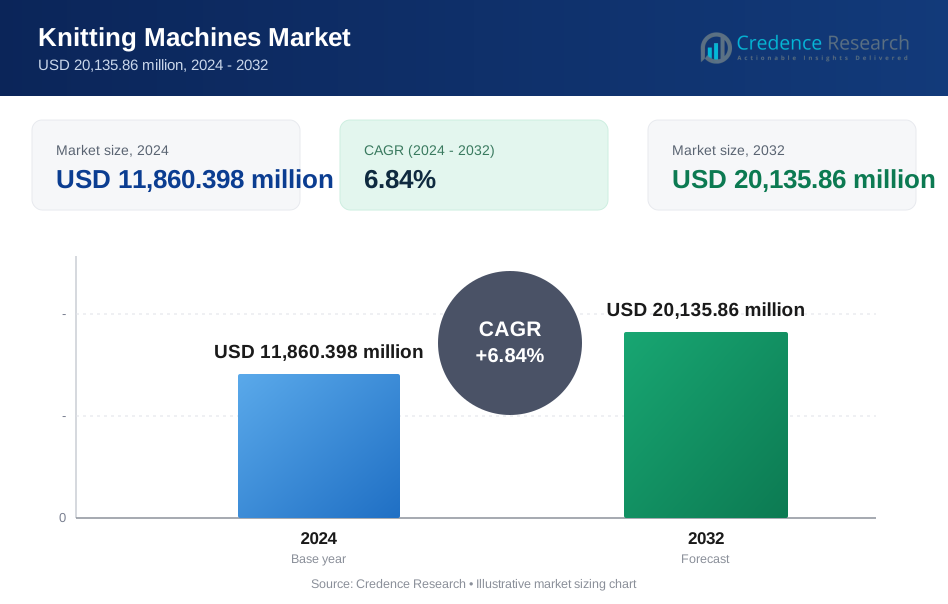
The Knitting Machines Market is projected to grow from USD 11,860.398 million in 2024 to an estimated USD 20,135.86 million by 2032, with a compound annual growth rate (CAGR) of 6.84% from 2024 to 2032.
Key drivers of the knitting machines market include the rising demand for textile products globally, advancements in knitting technology, and increasing consumer preference for high-quality, custom-made apparel. Innovations such as computerized knitting machines, automation, and integration with Industry 4.0 technologies are significantly enhancing production efficiency, precision, and design capabilities. Additionally, the growing trend of sustainable fashion is encouraging the adoption of energy-efficient and eco-friendly knitting solutions, further expanding the market.
Regionally, Asia Pacific is expected to hold a dominant share of the knitting machines market due to the strong presence of textile manufacturing hubs in countries like China, India, and Bangladesh. The high demand for knitted garments, along with the availability of skilled labor and cost-effective manufacturing processes, is driving the market growth in this region. Europe and North America are also contributing to market expansion, driven by the demand for high-quality knitting machines in apparel and technical textiles, as well as the integration of advanced technologies. In Latin America and the Middle East & Africa, there is an increasing adoption of modern knitting machines to enhance production capabilities and meet the growing demand for textiles, further supporting global market growth.
Market Drivers:
Technological Advancements in Knitting Machines:
The incorporation of advanced technologies like automation, computerized systems, and smart technologies in knitting machines is improving efficiency and enhancing production capabilities. These innovations help textile manufacturers produce high-quality, customized products at faster speeds. For instance, in 2020, Shima Seiki, a leading manufacturer of computerized knitting machines, introduced a new line of machines designed to handle complex, multi-color patterns and high-performance fabrics, boosting production efficiency by 25%. Similarly, Santoni has developed seamless knitting technologies that reduce material waste by approximately 40%, addressing both cost efficiency and environmental concerns.
Rising Demand for Customized and High-Quality Apparel:
Consumers are increasingly looking for high-quality, personalized clothing options, prompting the knitting machines market to innovate for higher levels of customization and intricate designs. This trend is especially prominent in sectors like sportswear, luxury fashion, and athleisure, where the demand for unique and detailed apparel is growing rapidly. For instance, Nike has been using advanced knitting machines to produce customized sports apparel, including the Nike Flyknit line, which uses precision knitting to create lightweight, performance-driven shoes. Since the introduction of Flyknit in 2012, Nike has sold over 30 million pairs of Flyknit shoes, showcasing the significant consumer demand for custom-made, high-performance apparel.
Sustainability and Eco-friendly Solutions in Fashion:
Sustainability has become a core focus in the global textile industry, with increasing pressure on manufacturers to reduce their environmental impact. This has led to the adoption of energy-efficient, eco-friendly knitting machines that produce less waste and consume fewer resources. For instance, The International Finance Corporation (IFC) supported a project in Bangladesh aimed at promoting the adoption of energy-efficient knitting technologies in textile factories. As a result, over 100 factories in the region adopted more sustainable practices, which resulted in a 20% reduction in energy consumption and a 15% reduction in carbon emissions per unit of production.
Growing Textile Manufacturing in Emerging Markets:
Emerging markets, particularly in Asia Pacific, are experiencing rapid growth in textile manufacturing, which is driving the demand for knitting machines. Countries like China, India, and Bangladesh continue to be the global centers of textile production due to lower labor costs, an expanding middle class, and a focus on improving manufacturing capabilities. For instance, China alone produces over 60% of the world’s knitted garments, with the government aiming to upgrade its manufacturing technologies through its “Made in China 2025” initiative. This initiative is focused on modernizing production processes, including the integration of more advanced knitting machinery, to boost overall textile production efficiency by 30% within the next decade. The Asian Development Bank (ADB) has forecasted that China's textile exports will grow by 5% annually through 2030, further driving the demand for advanced knitting machines.
Market Trends:
Sustainability and Eco-friendly Innovations:
Sustainability has become a key focus for the textile industry, and this is influencing the knitting machines market. Consumers are becoming more aware of the environmental impact of fashion, which has prompted manufacturers to adopt eco-friendly and energy-efficient knitting solutions. In response to this demand, companies are developing machines that minimize waste, reduce energy consumption, and use eco-friendly materials. For instance, the World Bank has highlighted the importance of sustainable manufacturing practices in emerging markets, where knitting machines are being upgraded to reduce environmental footprints. A study on sustainable textile production conducted by the United Nations Industrial Development Organization (UNIDO) noted that energy-efficient knitting machines can cut energy consumption by up to 20% in comparison to traditional machines. Companies are adopting such innovations to meet the growing demand for eco-conscious production processes.
Integration of Smart Technology and Automation:
The integration of smart technologies, such as artificial intelligence (AI), automation, and data-driven analytics, is another major trend influencing the knitting machines market. These technologies are making knitting machines more efficient, flexible, and capable of producing more intricate designs and customized products. By using automated systems, manufacturers can optimize production, reduce human error, and improve overall operational efficiency. For instance, according to a report by the International Labour Organization (ILO), automated and smart knitting machines are expected to enhance labor productivity in the textile industry by automating routine tasks, which will reduce the cost of production while increasing output. The International Finance Corporation (IFC) notes that the shift toward Industry 4.0 technologies in textile production is set to reshape global manufacturing strategies, making processes more streamlined and responsive to market demands. These trends of sustainability and automation are pivotal in shaping the future of the knitting machines market. As manufacturers continue to adopt energy-efficient technologies and smart systems, the industry is likely to experience growth driven by innovation, environmental responsibility, and more efficient production capabilities.
Market Challenge Analysis:
Technological and Cost Barriers:
One of the primary challenges facing the knitting machines market is the high cost associated with advanced technologies, particularly for small and medium-sized manufacturers. While innovations such as computerized, automated, and smart knitting machines have revolutionized the industry by improving production efficiency, reducing labor costs, and enabling the creation of more complex designs, the initial investment required for these machines is substantial. Small manufacturers, especially in emerging markets, often face difficulties in adopting these advanced technologies due to the high upfront costs and the need for specialized training. As a result, many textile manufacturers in regions like South Asia and Latin America continue to rely on older, manual machines, which are less efficient and unable to meet the rising demand for higher-quality and more intricate textile products. This technology gap can limit their competitiveness on a global scale, particularly as more developed markets continue to invest in cutting-edge knitting solutions. Moreover, the integration of Industry 4.0 technologies into knitting machines, such as the Internet of Things (IoT), big data analytics, and artificial intelligence (AI), requires significant infrastructure and expertise, which can be a barrier for companies that lack the resources or technical knowledge to implement these systems. While automation and data-driven processes can lead to improved operational efficiencies and reduced downtime, the complexity of these systems often demands a skilled workforce to manage and maintain the machines. Manufacturers must invest not only in the machinery itself but also in workforce training, system integration, and ongoing maintenance, which can pose significant challenges for companies with limited financial resources or technical capabilities. This creates a disparity in the market, where larger players with greater resources are able to capitalize on these advancements, leaving smaller players behind.
Sustainability and Environmental Compliance:
Another key challenge in the knitting machines market is the increasing pressure to meet sustainability standards and comply with environmental regulations. The textile industry, one of the largest polluters globally, faces heightened scrutiny from both consumers and governments regarding its environmental impact. While the trend toward sustainable fashion is growing, knitting machine manufacturers are required to innovate and adapt their production processes to align with stricter environmental regulations and consumer demand for eco-friendly products. This includes reducing energy consumption, minimizing water usage, and decreasing waste generation in the manufacturing process. However, upgrading to energy-efficient machines and adopting eco-friendly production techniques often requires significant capital investment, which can be a challenge for manufacturers operating in price-sensitive markets. Additionally, the rising cost of raw materials, such as sustainable fibers and eco-friendly dyes, can further complicate efforts to reduce the environmental footprint of textile production. While many knitting machine manufacturers are working to develop solutions that use less water, energy, and chemicals, the overall shift toward more sustainable practices often involves a complex overhaul of production processes that can be both time-consuming and costly. For instance, companies in countries like China, which have historically been major textile producers, face pressure to comply with international environmental standards, especially as key markets in Europe and North America implement stricter regulations around textile production. This can lead to higher operational costs and reduced profitability for manufacturers that fail to adapt to these evolving market demands. Furthermore, brands and consumers increasingly demand transparency about production practices, forcing manufacturers to implement traceability systems and certifications that confirm their sustainability claims.
Market Segmentation Analysis:
By Type
The knitting machines market is divided into various types, including single jersey, double jersey, jacquard, interlock, raschel, and fully fashioned knitting machines. Among these, single jersey knitting machines are the most commonly used due to their versatility and widespread application in the garment manufacturing industry. Double jersey machines, known for their ability to produce more complex fabric structures, are gaining traction in high-quality garment production. Jacquard knitting machines, which allow for intricate and customizable designs, are in high demand for producing patterned textiles and specialty fabrics. Raschel knitting machines, used primarily for producing lace, nets, and other specialty fabrics, are seeing increased adoption in home textiles and technical textile applications. Fully fashioned knitting machines, which are used to produce finished garments with minimal post-production, are also experiencing growth as manufacturers look to improve efficiency and reduce labor costs. Each type caters to different needs within the textile and garment industries, with varying degrees of complexity and output capabilities.
By Technology
The knitting machines market is segmented based on technology, primarily distinguishing between computerized, manual, semi-automatic, fully automatic, and smart (IoT-enabled) machines. Computerized knitting machines are the most advanced and have become the industry standard due to their ability to handle complex patterns and designs with high precision. These machines also offer greater flexibility and faster production times, making them popular in apparel manufacturing. Manual knitting machines, while less commonly used today, still hold value in specialized, small-scale production where customization and intricate handcrafting are required. Semi-automatic machines combine the flexibility of manual machines with some automation, offering a middle ground for manufacturers who need higher productivity but still desire some degree of manual control. Fully automatic knitting machines, which can run with minimal human intervention, are gaining popularity for their efficiency in large-scale production environments. Additionally, the rise of smart knitting machines, integrated with Internet of Things (IoT) technologies, allows for real-time monitoring and data-driven decision-making, providing manufacturers with enhanced operational insights and efficiency gains.
By End-User
The knitting machines market serves various end-user industries, with significant demand coming from apparel and garment manufacturing, home textiles, technical textiles, sportswear, medical textiles, and automotive textiles. Apparel and garment manufacturing remain the largest segment, driven by the ever-growing demand for fashion and ready-made clothing. The home textiles sector, including items like blankets, bed sheets, and upholstery fabrics, is also a key consumer of knitting machines, particularly for the production of knitted fabrics. Technical textiles, which include fabrics used in industrial applications like filtration, construction, and geotextiles, are increasingly adopting advanced knitting machines for their durability and performance characteristics. The sportswear industry, driven by the need for flexible, high-performance fabrics, is seeing a rise in demand for specialized knitting machines that can produce breathable, moisture-wicking, and stretchable textiles. Medical textiles, including compression garments, wound care products, and other health-related fabrics, are another growing segment where knitting machines play a vital role in producing functional, high-quality materials. Lastly, the automotive textile market is expanding, with knitting machines used to produce fabrics for car seats, airbags, and other automotive components, requiring durability and compliance with safety standards.
Segmentation:
Based on Product Type:
- Single Jersey Knitting Machines • Double Jersey Knitting Machines • Jacquard Knitting Machines • Interlock Knitting Machines • Raschel Knitting Machines • Fully Fashioned Knitting Machines • Other Knitting Machines
Based on Machine Technology:
- Computerized Knitting Machines • Manual Knitting Machines • Semi-Automatic Knitting Machines • Fully Automatic Knitting Machines • Smart Knitting Machines (IoT-enabled)
Based on End-User Industry:
- Apparel and Garment Manufacturing • Home Textiles • Technical Textiles • Sportswear • Medical Textiles • Automotive Textiles • Other End-User Industries
Based on Region:
- Asia Pacific
- China
- India
- Japan
- Bangladesh
- Vietnam
- Indonesia
- Europe
- Germany
- Italy
- United Kingdom
- France
- Spain
- Netherlands
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Chile
- Middle East & Africa
- Turkey
- South Africa
- United Arab Emirates
- Egypt
- Saudi Arabia
Regional Analysis:
Asia Pacific
Asia Pacific is the largest and fastest-growing region in the global knitting machines market, accounting for a significant share of the market. The region is expected to continue holding the dominant position due to the presence of key textile manufacturing hubs, particularly in countries like China, India, Bangladesh, and Vietnam. These countries have well-established textile industries, a large workforce, and a robust supply chain infrastructure, which make them ideal locations for knitting machine manufacturing and production. In fact, Asia Pacific is estimated to hold nearly 55% of the global market share in 2024, a figure that is expected to grow further due to the region’s rapid industrialization and expansion of textile production. China, in particular, remains the world’s largest producer and exporter of knitted garments, and it is heavily investing in upgrading its textile machinery to maintain its competitive edge. The government’s "Made in China 2025" initiative focuses on modernizing the textile sector by adopting advanced technologies, including more energy-efficient and automated knitting machines. India and Bangladesh, on the other hand, are experiencing a rise in demand for modern knitting machines as their textile industries expand to meet global demand. These countries are investing in advanced knitting technologies to improve production efficiency and quality. Moreover, the increasing demand for high-quality garments and sustainable production practices has encouraged the adoption of smart and eco-friendly knitting machines in the region.
Europe
Europe holds the second-largest share of the global knitting machines market, with a market share of approximately 25% in 2024. The region is characterized by its demand for high-quality knitting machines, which are used in apparel, technical textiles, and luxury fashion segments. Countries like Germany, Italy, the United Kingdom, and France are key players in the market, with strong manufacturing and technological capabilities. European manufacturers are known for their focus on high-performance knitting machines that can produce intricate designs and cater to niche markets such as technical textiles, medical textiles, and automotive textiles. In Europe, the trend towards automation and digitalization in the textile industry is driving the adoption of advanced knitting technologies. The rise of smart knitting machines, integrated with IoT and Industry 4.0 capabilities, is particularly prominent in countries like Germany, which is a leader in industrial automation and technological innovation. Additionally, the European Union’s stringent environmental regulations are pushing manufacturers to invest in energy-efficient and sustainable knitting machines, further promoting the adoption of modern technologies. The shift toward eco-friendly manufacturing and circular fashion is expected to influence the market dynamics in this region, encouraging the development of machines that can support sustainable textile production.
North America
North America, with a market share of around 15% in 2024, is another key region driving growth in the knitting machines market. The United States and Canada are at the forefront of technological advancements, with a strong emphasis on high-tech knitting machines used in the production of high-performance fabrics, sportswear, and luxury apparel. The North American market is characterized by a demand for precision, customization, and automation in knitting machines. As a result, manufacturers in the region are adopting smart knitting machines that offer greater flexibility, efficiency, and customization capabilities to meet the changing needs of the market. Moreover, sustainability is a major factor shaping the North American market. Consumers are increasingly focused on ethical and sustainable fashion, prompting manufacturers to invest in energy-efficient and eco-friendly knitting solutions. The U.S. government’s focus on promoting sustainable manufacturing and reducing carbon emissions is also encouraging the adoption of greener technologies within the knitting machine industry. Additionally, the rise of circular fashion, which emphasizes recycling and reusing textiles, is expected to increase the demand for knitting machines capable of handling sustainable fibers and minimizing waste during the manufacturing process.
Key Player Analysis:
- Shima Seiki Manufacturing Ltd.
- Santoni S.r.l.
- Stoll GmbH
- Vardhman Textiles Ltd.
- Karl Mayer Textilmaschinenfabrik GmbH
- Jung Sohn Co. Ltd.
- Sucker Maschinenbau GmbH
- Pailung Machinery Mill Co., Ltd.
- Mayer & Cie. GmbH & Co. KG
- Terrot GmbH
Competitive Analysis:
The knitting machines market is highly competitive, with several key players vying for market share through technological innovation, product diversification, and strategic partnerships. Leading manufacturers, such as Shima Seiki Manufacturing Ltd., Santoni S.r.l., Vardhman Textiles Ltd., and Stoll GmbH, dominate the market by offering advanced, high-performance knitting machines tailored to meet the growing demand for precision, automation, and sustainability. These companies invest heavily in research and development to introduce next-generation technologies, such as computerized knitting machines, IoT-enabled systems, and smart knitting solutions that integrate with Industry 4.0 frameworks. They focus on producing machines capable of handling intricate designs, customization, and high-quality fabric production, which are in high demand, especially in premium apparel, sportswear, and technical textiles. Competition is also driven by regional manufacturers, especially in Asia Pacific, where countries like China and India have become significant production hubs. Local companies are focusing on cost-effective solutions while gradually integrating more advanced technologies to compete with global players. Additionally, market consolidation is evident, with larger players acquiring smaller, regional companies to expand their technological capabilities and market presence. As sustainability becomes a priority, companies are innovating to produce energy-efficient, eco-friendly machines that align with the growing trend for sustainable and circular fashion. The competitive landscape is further shaped by government policies and environmental regulations, pushing manufacturers to adopt green technologies and comply with international standards, particularly in Europe and North America. Overall, the market remains dynamic, with key players striving for continuous innovation and operational efficiency to maintain their competitive edge.
Recent Developments:
- In May 2022, KM. ON, the software company of the KARL MAYER Group, continued to innovate and digitalize the textile value chain with its advanced offerings. The company is committed to developing new digital solutions that enhance the customer experience, reduce complexity in day-to-day operations, and ultimately increase profitability for its clients.
- In May 2022, Mayer & Cie., a leading manufacturer of circular knitting machines, launched upgrade kits for machines already in use by customers. With tailored packages, the company aims to enable users to benefit from technological advancements in their existing machines. The upgrades are designed to improve machine performance and extend their service life.
Market Concentration & Characteristics:
The knitting machines market exhibits moderate to high concentration, with a few dominant players controlling a significant share of the global market. Leading manufacturers, such as Shima Seiki Manufacturing Ltd., Santoni S.r.l., Stoll GmbH, and Vardhman Textiles Ltd., hold a substantial market presence due to their technological expertise, established reputations, and large-scale production capabilities. These companies invest heavily in research and development to maintain their competitive advantage, constantly innovating with advanced knitting technologies like computerized machines, automation, and smart, IoT-enabled systems. The market is characterized by a trend toward consolidation, with larger players acquiring smaller companies or forming strategic partnerships to expand their product portfolios and access new markets. Despite this concentration, the market also features a growing number of regional players, particularly in Asia Pacific, where countries like China and India play a critical role in driving production and consumption. These regional manufacturers typically focus on cost-effective, high-volume production of standard knitting machines, aiming to serve the expanding textile industries in emerging markets. The market is characterized by a high degree of product diversification, as manufacturers offer machines tailored to a wide range of applications, from basic garment production to specialized technical textiles and luxury fabrics. Additionally, sustainability is becoming an increasingly important characteristic, as companies face pressure to develop eco-friendly, energy-efficient machines that align with global trends in sustainable fashion. Overall, the market exhibits a balance between large, technology-driven players and regional, price-sensitive manufacturers, fostering a competitive yet collaborative environment.
Report Coverage:
This report provides a comprehensive analysis of the global knitting machines market, offering insights into key trends, market drivers, challenges, regional dynamics, and competitive landscapes. It covers a broad spectrum of market segments, including product types (such as single jersey, double jersey, jacquard, and raschel knitting machines), machine technologies (ranging from computerized and manual machines to smart, IoT-enabled systems), and end-user industries (including apparel, home textiles, sportswear, medical textiles, and technical textiles). The report also delves into the market by region, with a particular focus on the dominant markets of Asia Pacific, Europe, and North America, examining their market share, growth potential, and key drivers of demand. Through detailed analysis, the report identifies the major challenges faced by manufacturers, such as high technological investment costs, the need for skilled labor, and sustainability pressures. Furthermore, it highlights the latest technological advancements, such as automation, Industry 4.0 integration, and energy-efficient solutions, that are shaping the market’s future. The report also evaluates the competitive landscape, profiling key players and their strategies to maintain a competitive edge. It includes market share analysis, strategic initiatives, and growth opportunities for both established and emerging players in the knitting machines market. Overall, this report offers valuable insights for stakeholders, helping them navigate market dynamics, identify growth opportunities, and make informed business decisions.
Future Outlook:
- The knitting machines market is expected to witness continued growth as technological advancements in automation and AI-driven solutions revolutionize production processes.
- Sustainability will remain a key focus, with manufacturers increasingly adopting energy-efficient and eco-friendly knitting machines to reduce waste and carbon footprints.
- Smart knitting machines integrated with IoT and Industry 4.0 technologies will drive enhanced production efficiency and enable real-time monitoring for better decision-making.
- The demand for customized and high-quality apparel will push the market to further innovate and develop machines capable of intricate designs and personalized products.
- Emerging markets in Asia Pacific, particularly China, India, and Bangladesh, will continue to dominate production, supported by low labor costs and expanding textile industries.
- Europe and North America will experience steady demand for advanced knitting machines, particularly in technical textiles and luxury fashion sectors.
- The rise in digitalization and adoption of smart factories will streamline textile manufacturing, enhancing operational flexibility and reducing production costs.
- Integration of sustainability into the supply chain will drive demand for eco-friendly knitting solutions, including machines that utilize organic fibers and reduce water consumption.
- The industry will see a shift towards automated and semi-automated systems, reducing dependency on manual labor and improving manufacturing accuracy.
- Continued government support and investment in technological innovation will further accelerate the growth of the knitting machines market worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Knitting Machines
The integration of automation, computerized controls, and smart technologies is enabling manufacturers to produce high-quality, customized textiles at greater speed and efficiency. These innovations are making it possible to handle complex patterns and reduce production costs, driving adoption across the textile industry.
Sustainability and Eco-friendly Solutions
Growing environmental concerns and regulatory pressures are pushing manufacturers to adopt energy-efficient and eco-friendly knitting machines. These machines help reduce waste, lower energy consumption, and support the production of sustainable textiles, aligning with the global shift toward greener manufacturing.
Rising Demand for Customized and High-Quality Apparel
Consumer preferences are shifting toward personalized, high-quality garments, especially in sportswear, luxury fashion, and athleisure. Advanced knitting machines enable intricate designs and rapid customization, meeting the needs of brands and consumers seeking unique products.
Expansion of Textile Manufacturing in Emerging Markets
Countries in Asia Pacific, such as China, India, and Bangladesh, are expanding their textile manufacturing capabilities due to low labor costs and supportive government initiatives. This growth is fueling demand for modern knitting machines to increase production capacity and improve product quality.
Integration of Industry 4.0 and Smart Factory Solutions
The adoption of IoT-enabled and data-driven knitting machines is transforming textile production by enabling real-time monitoring, predictive maintenance, and enhanced operational efficiency. This digital transformation is helping manufacturers optimize processes and remain competitive in a rapidly evolving market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the knitting machines market from 2024 to 2032
What are the main drivers of the knitting machines market
How is technology impacting the knitting machines market
Which region is leading the knitting machines market
What trends are influencing the global knitting machines market
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Single Jersey Knitting Machines
- 1.2.2 Double Jersey Knitting Machines
- 1.2.3 Jacquard Knitting Machines
- 1.2.4 Interlock Knitting Machines
- 1.2.5 Raschel Knitting Machines
- 1.2.6 Fully Fashioned Knitting Machines
- 1.2.7 Other Knitting Machines
- 1.3 By End-User Industry
- 1.3.1 Apparel and Garment Manufacturing
- 1.3.2 Home Textiles
- 1.3.3 Technical Textiles
- 1.3.4 Sportswear
- 1.3.5 Medical Textiles
- 1.3.6 Automotive Textiles
- 1.3.7 Other End-User Industries
- 1.4 By Machine Technology
- 1.4.1 Computerized Knitting Machines
- 1.4.2 Manual Knitting Machines
- 1.4.3 Semi-Automatic Knitting Machines
- 1.4.4 Fully Automatic Knitting Machines
- 1.4.5 Smart Knitting Machines (IoT-enabled)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,860.398 million → 2032: USD 20,135.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Knitting Machines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Knitting Machines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Knitting Machines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Knitting Machines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Knitting Machines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Knitting Machines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Knitting Machines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Knitting Machines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,860.398 million → 2032: USD 20,135.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Knitting Machines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Jersey Knitting Machines
- 12.3.7.2 Double Jersey Knitting Machines
- 12.3.7.3 Jacquard Knitting Machines
- 12.3.7.4 Interlock Knitting Machines
- 12.3.7.5 Raschel Knitting Machines
- 12.3.7.6 Fully Fashioned Knitting Machines
- 12.3.7.7 Other Knitting Machines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Apparel and Garment Manufacturing
- 12.4.7.2 Home Textiles
- 12.4.7.3 Technical Textiles
- 12.4.7.4 Sportswear
- 12.4.7.5 Medical Textiles
- 12.4.7.6 Automotive Textiles
- 12.4.7.7 Other End-User Industries
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Machine Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Computerized Knitting Machines
- 12.5.7.2 Manual Knitting Machines
- 12.5.7.3 Semi-Automatic Knitting Machines
- 12.5.7.4 Fully Automatic Knitting Machines
- 12.5.7.5 Smart Knitting Machines (IoT-enabled)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Knitting Machines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Knitting Machines Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Knitting Machines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Knitting Machines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Shima Seiki Manufacturing Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Santoni S.r.l.
- 18.4 Stoll GmbH
- 18.5 Vardhman Textiles Ltd.
- 18.6 Karl Mayer Textilmaschinenfabrik GmbH
- 18.7 Jung Sohn Co. Ltd.
- 18.8 Sucker Maschinenbau GmbH
- 18.9 Pailung Machinery Mill Co., Ltd.
- 18.10 Mayer & Cie. GmbH & Co. KG
- 18.11 Terrot GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

