
Lightweight Conveyor Belting Market Overview:
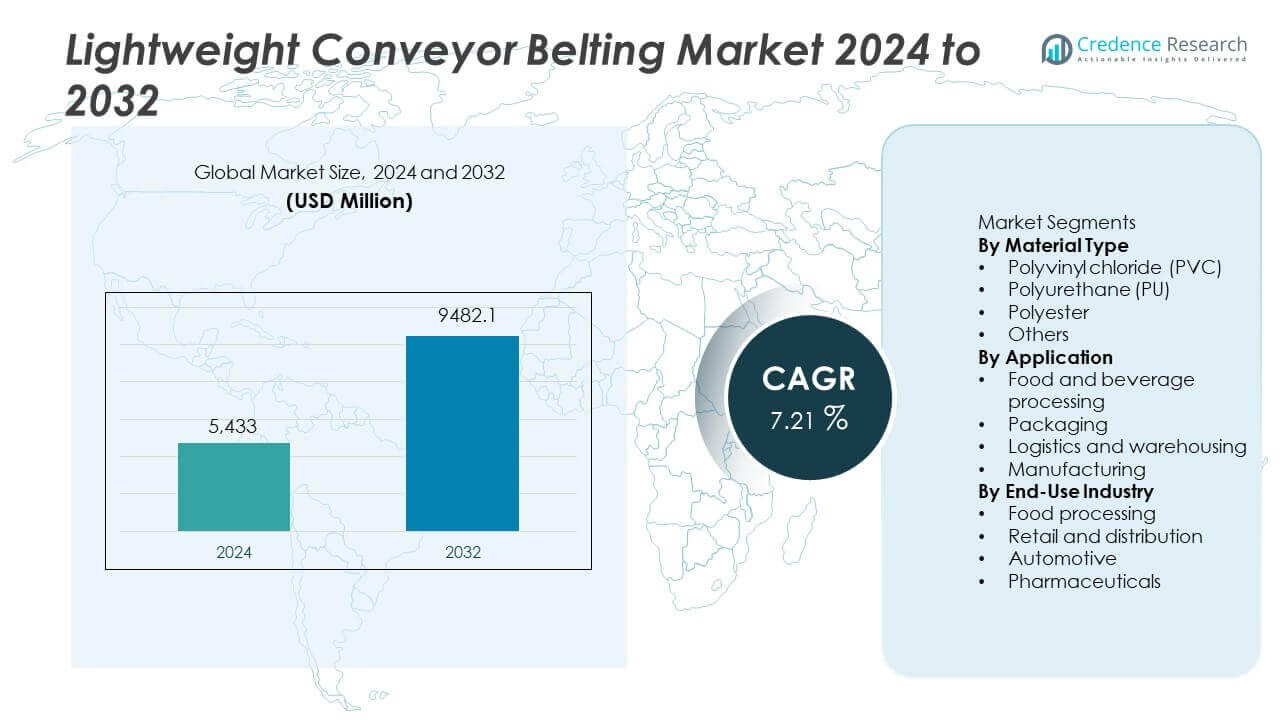
The lightweight conveyor belting market was valued at USD 5,433 million in 2024 and is anticipated to reach USD 9,482.1 million by 2032, growing at a CAGR of 7.21% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lightweight Conveyor Belting Market Size 2024 | USD 5,433 million |
| Lightweight Conveyor Belting Market, CAGR | 7.21% |
| Lightweight Conveyor Belting Market Size 2032 | USD 9,482.1 million |
Lightweight Conveyor Belting Market Insights
- Market growth is driven by rising automation in manufacturing and warehousing, with food processing leading end use at a segment share of 36.3% due to hygiene and continuous operation needs.
- Market trends show strong preference for PVC-based belts, which hold a segment share of 38.6%, supported by flexibility, cost efficiency, and wide industrial applicability.
- Competitive analysis indicates moderate consolidation, where leading players focus on material innovation, hygienic belt designs, and automation-ready solutions to strengthen long-term customer relationships.
- Regional analysis highlights Asia Pacific as the leading market with a share of 38.4%, followed by North America at 26.9% and Europe at 24.7%, driven by industrial expansion, food processing growth, and e-commerce logistics development.
Lightweight Conveyor Belting Market Segmentation Analysis:
By Material Type
The material type segment is led by polyvinyl chloride belts, which hold a market share of 38.6%. Manufacturers prefer PVC belts due to cost efficiency, flexibility, and resistance to abrasion. These belts perform well in light- to medium-duty conveying tasks. Polyurethane belts follow with a share of 31.4%, driven by demand for hygiene, oil resistance, and durability. PU belts see strong use in food and pharmaceutical environments. Polyester belts account for 19.2%, supported by tensile strength and dimensional stability. Growth is driven by material versatility, lifecycle performance, and maintenance efficiency.
- For instance, Ammeraal Beltech supplies PU belts certified for direct food contact and capable of tensile strengths exceeding 20 N/mm.
By Application
Food and beverage processing dominates the application segment with a market share of 34.8%. Lightweight conveyor belts support hygienic handling and smooth product flow. Compliance with food safety standards drives belt replacement demand. Packaging applications hold a share of 27.1%, supported by automation and high-speed operations. Logistics and warehousing account for 22.9%, driven by e-commerce growth and material handling needs. Manufacturing represents 15.2%, focused on assembly and intra-plant movement. Application growth depends on automation adoption, throughput efficiency, and reduced downtime requirements across facilities.
- For instance, Continental AG supplies lightweight belts engineered for continuous operation exceeding 20,000 running hours in automated packaging plants.
By End-Use Industry
Food processing leads the end-use industry segment with a market share of 36.3%. Rising packaged food consumption drives belt demand. Lightweight belts enable clean, efficient, and continuous processing. Retail and distribution follow with a share of 29.6%, supported by warehouse automation and order fulfillment growth. Automotive holds 19.1%, driven by component handling and assembly line efficiency. Pharmaceuticals account for 15.0%, supported by hygienic and precise conveying needs. End-use demand grows due to automation investment, operational efficiency goals, and rising throughput across industrial sectors.
Key Growth Drivers
Rising Automation in Manufacturing and Logistics
Industries increasingly adopt automated material handling to improve productivity and accuracy. Lightweight conveyor belting supports high-speed and continuous operations. Logistics centers rely on belts for sorting, packing, and order fulfillment. Manufacturing plants use conveyors to reduce manual handling and downtime. Growth of e-commerce accelerates warehouse automation investments. Lightweight belts offer flexibility and easy integration with automated systems. Reduced energy consumption supports cost control. This driver remains strong as industries scale operations and optimize workflow efficiency.
- For instance, Intralox LLC deployed lightweight modular belts operating at conveyor speeds up to 120 m/min in automated sortation lines, enabling continuous 24-hour operation.
Expansion of Food and Beverage Processing Industries
Food and beverage processors drive strong demand for lightweight conveyor belting. Hygiene standards require belts with smooth surfaces and easy cleaning. Lightweight belts support gentle handling of food products. Rising packaged and processed food consumption boosts conveyor installations. Automation improves throughput and quality consistency. Compliance with food safety regulations accelerates belt replacement cycles. PU and PVC belts see higher adoption. This driver supports steady demand growth across processing facilities worldwide.
- For instance, Forbo Movement Systems developed monolithic belts with surface roughness below 1 µm, reducing residue buildup during continuous processing.
Growth in E-commerce and Warehousing Infrastructure E-commerce growth increases demand for efficient material handling systems. Warehouses expand capacity to manage higher order volumes. Lightweight conveyor belting enables fast sorting and distribution. Flexible layouts support changing fulfillment needs. Retailers invest in automated distribution centers. Belts reduce handling errors and labor dependency. Rising last-mile delivery operations strengthen demand. This driver aligns with long-term digital commerce expansion.
Key Trends & Opportunities
Shift Toward Hygienic and Specialty Belt Materials
Manufacturers increasingly demand belts with enhanced hygiene properties. PU belts gain traction in food and pharmaceutical applications. Oil and chemical resistance improve operational reliability. Specialty coatings support longer service life. Compliance with strict sanitation norms drives upgrades. Suppliers develop application-specific belt solutions. This trend creates opportunities for premium products. Demand rises for customized and certified belting systems.
- For instance, Volta Belting Technology introduced monolithic belts with sealed edges and hardness levels reaching 92 Shore A, reducing bacterial ingress and edge wear during long production cycles.
Integration of Smart Conveyor Systems
Smart conveyors incorporate sensors and monitoring systems. Lightweight belts support data-driven maintenance strategies. Predictive maintenance reduces downtime and operating costs. Digital monitoring improves belt life management. Integration with factory automation systems enhances efficiency. End users seek intelligent material handling solutions. This trend opens opportunities for value-added services. Technology integration strengthens supplier differentiation.
- For instance, Habasit AG engineered belts compatible with embedded condition-monitoring sensors, enabling real-time tracking of belt tension and detecting deviations below 0.5 mm elongation per meter.
Key Challenges
Volatility in Raw Material Prices
Raw material price fluctuations affect belt manufacturing costs. PVC and PU feedstock prices impact margins. Cost volatility complicates pricing strategies. Manufacturers face pressure to absorb cost increases. Supply chain disruptions increase procurement risks. Smaller suppliers face higher exposure. Long-term contracts become difficult to manage. This challenge affects profitability and market stability.
Wear, Tear, and Replacement Costs
Lightweight conveyor belts experience regular wear under continuous use. High-speed operations increase abrasion and fatigue. Frequent replacements raise maintenance costs. Downtime during belt change impacts productivity. End users seek durable solutions at competitive prices. Improper maintenance shortens belt life. Balancing performance and cost remains challenging. This factor influences purchasing and lifecycle decisions.
Regional Analysis
North America
North America holds a market share of 26.9% in the lightweight conveyor belting market. Strong demand comes from food processing, logistics, and retail distribution. The United States leads adoption due to advanced warehouse automation and high labor costs. E-commerce expansion drives conveyor installations in fulfillment centers. Food safety regulations support frequent belt replacement and upgrades. Manufacturers invest in hygienic and energy-efficient belting solutions. Automotive assembly plants also contribute to steady demand. Technological maturity and strong aftermarket services support stable regional growth.
Europe Europe accounts for a market share of 24.7%, supported by advanced manufacturing and strict regulatory standards. Germany, France, and the United Kingdom drive
demand across food processing and packaging industries. Emphasis on hygiene and sustainability boosts PU belt adoption. Automated production lines increase replacement demand for lightweight belts. Retail distribution centers support steady consumption. Pharmaceutical manufacturing adds niche demand. Energy-efficient operations encourage lightweight solutions. Strong focus on quality and compliance sustains consistent market expansion across the region.
Asia Pacific
Asia Pacific leads the global lightweight conveyor belting market with a market share of 38.4%. Rapid industrialization and urbanization drive high demand. China, India, and Southeast Asia dominate manufacturing and logistics growth. Expansion of food processing and e-commerce fuels conveyor installations. Cost-efficient production supports large-scale adoption. Warehousing infrastructure grows with rising online retail. Automotive and electronics manufacturing add volume demand. Increasing automation investments strengthen long-term regional leadership.
Rest of the World
The Rest of the World region holds a market share of 10.0%. Latin America shows demand from food processing and retail distribution. Brazil and Mexico lead regional consumption. The Middle East supports logistics and warehouse expansion. Africa shows gradual adoption linked to industrial development. Price sensitivity influences material choice. Import dependence affects supply availability. Manual and semi-automated systems remain common. Infrastructure development and retail modernization support gradual market growth.
Lightweight Conveyor Belting Market Segmentations:
By Material Type
- Polyvinyl chloride (PVC)
- Polyurethane (PU)
- Polyester
- Others
By Application
- Food and beverage processing
- Packaging
- Logistics and warehousing
- Manufacturing
By End-Use Industry
- Food processing
- Retail and distribution
- Automotive
- Pharmaceuticals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights Habasit AG, Ammeraal Beltech, Forbo Movement Systems, Intralox LLC, Continental AG, Fenner Dunlop, Yokohama Rubber Co., Ltd., Bridgestone Corporation, Mitsuboshi Belting Ltd., and Volta Belting Technology as the core participants shaping the lightweight conveyor belting market. These companies compete through material innovation, product durability, and application-specific solutions. Strong focus remains on hygienic and energy-efficient belts for food processing and logistics. Global players leverage wide distribution networks and strong aftermarket support. Product portfolios emphasize PU and PVC belts to meet regulatory and operational needs. Strategic investments target automation compatibility and longer belt life. Mid-sized suppliers compete through customization and quick delivery. Competitive intensity remains moderate, driven by technology upgrades, service capabilities, and long-term customer relationships across industrial sectors.
Key Player Analysis
- Habasit AG
- Ammeraal Beltech
- Forbo Movement Systems
- Intralox LLC
- Fenner Dunlop
- Continental AG
- Yokohama Rubber Co., Ltd.
- Bridgestone Corporation
- Mitsuboshi Belting Ltd.
- Volta Belting Technology
Recent Developments
- In May 2025, Continental AG completed its Brazil plant expansion and launched “Total Conveyance.”
- In December 2024, Forbo Movement Systems added three Siegling Fullsan PD2+ belt types.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Application, End-Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Lightweight Conveyor Belting market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Lightweight Conveyor Belting market projected to grow between 2024 and 2032?
Which Lightweight Conveyor Belting market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Lightweight Conveyor Belting market?
Who are the leading companies in the Lightweight Conveyor Belting market?
Which region commanded the largest share of the Lightweight Conveyor Belting market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,433 million → 2032: USD 9,482.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lightweight Conveyor Belting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lightweight Conveyor Belting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lightweight Conveyor Belting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lightweight Conveyor Belting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lightweight Conveyor Belting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lightweight Conveyor Belting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lightweight Conveyor Belting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lightweight Conveyor Belting Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,433 million → 2032: USD 9,482.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lightweight Conveyor Belting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lightweight Conveyor Belting Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Lightweight Conveyor Belting Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Lightweight Conveyor Belting Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

