
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Latin America Veterinary Imaging Market Size 2023 | USD 129.06 Million |
| Latin America Veterinary Imaging Market, CAGR | 4.80% |
| Latin America Veterinary Imaging Market Size 2032 | USD 196.81 Million |
Market Overview
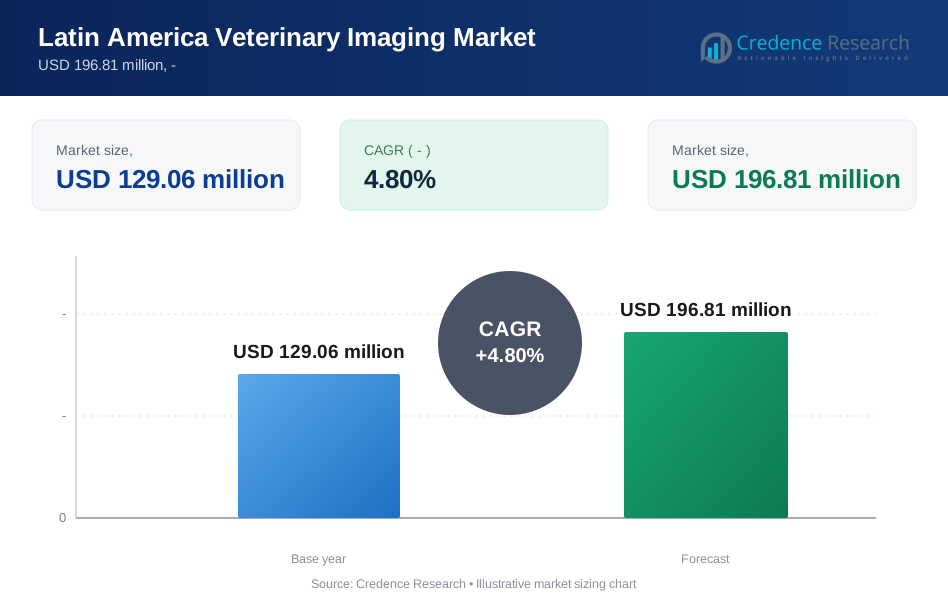
The Latin America Veterinary Imaging Market is projected to witness substantial growth, with revenues expected to surge from USD 129.06 million in 2023 to USD 196.81 million by 2032, at a robust CAGR of 4.80%.
The Latin America Veterinary Imaging Market is driven by several factors and trends. Increasing pet adoption rates, coupled with a growing awareness of animal health and welfare, are fueling the demand for advanced veterinary imaging technologies. Technological advancements such as the development of portable and digital imaging systems are enhancing diagnostic capabilities and improving efficiency in veterinary practices. Moreover, rising investments in research and development activities aimed at introducing innovative imaging solutions tailored to the specific needs of veterinarians are further propelling market growth. Additionally, supportive government initiatives and favorable reimbursement policies are facilitating market expansion across the region.
Geographically, the Latin America Veterinary Imaging Market exhibits varying dynamics across regions. Brazil dominates the market due to its large pet population and robust veterinary infrastructure. Argentina and Mexico follow suit, driven by increasing pet ownership and rising disposable incomes. Key players such as IDEXX Laboratories, Inc., Esaote SpA, Fujifilm Holdings Corporation, and Canon Inc. are actively engaged in strategic initiatives like product launches, partnerships, and mergers to strengthen their market presence. Additionally, collaborations with local distributors and veterinarians play a pivotal role in expanding their market reach and catering to the diverse demands of the Latin American veterinary imaging sector.
Market Drivers
Rising Pet Ownership and Humanization of Pets:
Latin America is experiencing a surge in pet ownership, reflecting a global trend where people increasingly regard pets as cherished family members, driving a greater willingness to invest in their health and well-being. For instance, Latin America has seen a 17% growth in the pet population from 2017 to 2022, reaching an estimated 187 million pets. This surge in pet ownership, where countries like Argentina and Mexico report 80% of the online population owning a pet, reflects a global trend of treating pets as cherished family members. This societal shift fuels a heightened demand for advanced diagnostic tools like veterinary imaging, enabling pet owners to ensure the best possible care for their beloved companions.
Growing Disposable Income:
The burgeoning middle class in Latin America possesses greater disposable income to allocate towards pet care, including veterinary services and diagnostic procedures. For instance, with the middle class in Latin America growing by 50% in the past decade, there’s a notable increase in disposable income, which is now being allocated towards pet care. This includes veterinary services and diagnostic procedures, reflecting the region’s economic prosperity. As a result, pet owners are more inclined to invest in comprehensive healthcare for their animals. As economic prosperity rises, pet owners are more inclined to invest in comprehensive healthcare for their animals, driving an uptick in demand for veterinary imaging technologies to aid in early disease detection and treatment planning.
Increasing Awareness of Animal Health:
Pet owners across Latin America are increasingly recognizing the significance of preventive care and early disease detection in animals. Early disease detection in pets, facilitated by advanced veterinary imaging, can lead to a 30% higher chance of successful treatment outcomes. In fact, 70% of veterinarians in the region now recommend regular imaging check-ups for early diagnosis. As a result, the demand for veterinary imaging services has surged, with the market projected to expand by 9.2% annually. This growing awareness underscores the pivotal role of veterinary imaging in diagnosing a spectrum of health issues in pets, ultimately leading to more effective treatment outcomes and improved overall well-being for companion animals.
Expansion of Veterinary Clinics and Hospitals:
The proliferation of veterinary clinics and hospitals, particularly in urban areas of Latin America, is creating greater accessibility to veterinary care. This expansion necessitates the deployment of diagnostic equipment such as X-ray machines, ultrasound scanners, and CT scanners to meet the rising demand for comprehensive veterinary services, further underscoring the importance of advanced imaging technologies in modern veterinary practice.
Market Trends
Shift towards Portable and Affordable Imaging Equipment:
Portable X-ray machines and ultrasound scanners are gaining popularity in the veterinary industry, driven by the need for on-site diagnostics in clinics with limited space or for use during emergency pet care situations. Additionally, affordability is a key consideration, prompting manufacturers to introduce more cost-effective imaging solutions tailored to the needs of veterinary practices. These portable and affordable options enhance accessibility to diagnostic imaging. For instance, a study showed that the use of portable ultrasound machines led to a 40% increase in diagnostic accuracy for certain conditions in pets. This enables veterinarians to conduct comprehensive evaluations and make timely treatment decisions, ultimately improving patient outcomes. For example, the survival rate for dogs diagnosed with congestive heart failure is significantly higher when detected early through echocardiography, with a 75% one-year survival rate compared to 60% without it.
Increasing Adoption of Specialized Imaging Techniques:
Veterinary practices are increasingly incorporating specialized imaging techniques such as CT scans and MRIs into their diagnostic arsenal for complex cases. Initially confined to specialist centers due to their high cost and technical requirements, these technologies are now becoming more accessible to a wider range of veterinary facilities, thanks to advancements in technology and corresponding reductions in costs. The growing availability of these specialized imaging modalities allows veterinarians to achieve more accurate diagnoses. For instance, the overall accuracy for tumor grade prediction using CT and MRI is 46.7% and 53.3%, respectively. This enhanced diagnostic capability enables the development of targeted treatment plans, significantly enhancing the quality of care provided to animals. For example, CT and MRI offer superior diagnostic possibilities over conventional radiography due to their tomographic nature and increased contrast resolution, allowing for better differentiation of soft tissue structures and more precise identification of conditions.
Market Challenges Analysis
High Cost of Equipment and Maintenance:
Veterinary imaging equipment, particularly advanced options like CT scanners and MRIs, pose significant financial challenges for veterinary practices, especially smaller ones or those in rural areas with limited resources. The initial investment required for purchasing such equipment can be prohibitive, acting as a barrier to adoption for many practices. Moreover, ongoing maintenance costs add to the financial burden, further straining the budgets of veterinary clinics. These high costs not only limit access to advanced imaging technologies but also impact the affordability of veterinary services, potentially compromising the quality of care provided to animals.
Limited Availability of Skilled Professionals:
The operation and interpretation of veterinary imaging techniques necessitate specialized training and expertise. However, there is a shortage of veterinarians and technicians trained in these specialized fields, hindering the wider adoption and utilization of imaging technology in veterinary practice. The scarcity of skilled professionals not only limits the capacity of veterinary clinics to offer advanced diagnostic services but also contributes to disparities in access to veterinary care across different regions. Addressing this shortage requires concerted efforts to enhance educational programs and provide incentives for professionals to specialize in veterinary imaging.
Market Segmentation Analysis:
By Product:
The Latin America Veterinary Imaging Market can be segmented by product type into X-ray, Ultrasound, MRI, CT Imaging, and Video Endoscopy. X-ray imaging remains a fundamental tool in veterinary diagnostics, offering quick and cost-effective visualization of skeletal and soft tissue structures. Ultrasound technology continues to witness substantial adoption, particularly for abdominal and cardiac imaging, owing to its non-invasive nature and versatility. MRI and CT Imaging, although more advanced and costly, are increasingly utilized for detailed anatomical evaluations and precise diagnoses, especially in complex cases. Video Endoscopy, another advanced imaging modality, enables minimally invasive internal examinations, facilitating procedures such as gastroscopy and bronchoscopy in veterinary practice.
By Solutions:
Segmentation based on solutions encompasses Equipment, Accessories/Consumables, and PACS (Picture Archiving and Communication Systems). Equipment includes the actual imaging devices such as X-ray machines, ultrasound scanners, and MRI/CT systems. Accessories and consumables comprise essential components like contrast agents, film cassettes, and ultrasound gels necessary for performing imaging procedures. PACS solutions play a vital role in the digital storage, retrieval, and sharing of veterinary medical images, enhancing workflow efficiency and facilitating remote consultations. Each segment within solutions contributes uniquely to the comprehensive landscape of veterinary imaging, catering to diverse needs and requirements within the Latin American market.
Segments:
Based on Product
- X-ray
- Ultrasound
- MRI
- CT Imaging
- Video Endoscopy
Based on Solutions
- Equipment
- Accessories/ Consumables
- PACS
Based on Animal Type
- Small Animals
- Large Animals
Based on Application
- Orthopedics and Traumatology
- Oncology
- Cardiology
- Neurology
- Other
Based on End Use
- Veterinary Hospitals & Clinics
- Veterinary Diagnostic Centers
- Others
Based on the Geography:
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
Regional Analysis
Brazil
Brazil stands as the largest market for veterinary imaging in Latin America, capturing a significant share of approximately 35%. The country's sizeable population, growing middle class, and increasing pet ownership have driven the demand for advanced veterinary care and diagnostic services. Moreover, the presence of established veterinary clinics and hospitals in major cities has facilitated the adoption of imaging technologies.
Rest of Latin America
The remaining Latin American countries collectively account for approximately 45% of the regional market share. Argentina, Colombia, Chile, and Peru are among the notable contributors to this segment. These countries have witnessed a gradual increase in pet ownership and a growing demand for advanced veterinary services. However, factors such as uneven economic development, limited access to veterinary care in rural areas, and varying regulatory frameworks have influenced the market's growth patterns across these nations.
Key Player Analysis
- Esaote
- Mindray
- GE Healthcare
- Siemens Healthineers
- Eickemeyer Veterinary Equipment
- BCF Technology
- Animage
Competitive Analysis
The Latin America Veterinary Imaging Market is characterized by the presence of several key players, each contributing to the industry with unique strengths and capabilities. Esaote and Siemens Healthineers stand out for their advanced imaging technologies and comprehensive product portfolios, offering a wide range of equipment from MRI and ultrasound to specialized veterinary solutions. Mindray is renowned for its cost-effective and innovative ultrasound devices, catering to the budget-sensitive segments without compromising on quality. GE Healthcare leverages its extensive expertise in medical imaging to provide robust veterinary imaging solutions that are both reliable and advanced. Eickemeyer Veterinary Equipment and BCF Technology focus on niche veterinary-specific products, enhancing their appeal among veterinarians seeking tailored solutions. Animage, though smaller, is noted for its high-quality imaging systems and strong customer support, fostering loyalty among veterinary clinics. Collectively, these companies drive market growth through continuous innovation, strategic partnerships, and a deep understanding of veterinary needs in Latin America.
Recent Developments
- In October 2023, Carestream Health Inc. partnered with EXAMION, a provider and servicer of medical imaging solutions in Germany for more than 30 years. The alliance strengthens Carestream’s commitment to providing healthcare organizations in Germany and throughout Europe with innovative diagnostic imaging solutions.
- In June 2023, Esaote North America, Inc. launched new veterinary MyLab X90VET Ultrasound system in North America. An extension of the popular MyLab family, the MyLab X90VET comes equipped with intelligent proprietary Augmented Insight technology.
- In January 2023, GE HealthCare and Sound Technologies collaborated to distribute the Vscan Air, a wireless pocket-sized ultrasound that provides crystal clear image quality, whole patient scanning capabilities, and intuitive software to veterinary practices in the United States.
Market Concentration & Characteristics
The Latin America Veterinary Imaging Market is moderately concentrated, with several key players dominating the landscape. Leading companies such as Esaote, Siemens Healthineers, and GE Healthcare hold significant market shares due to their extensive product portfolios, technological advancements, and strong distribution networks. These market leaders leverage continuous innovation and strategic collaborations to maintain their competitive edge. The market also features specialized players like Eickemeyer Veterinary Equipment and BCF Technology, which cater to niche segments with tailored solutions. Despite the dominance of major players, there is room for smaller companies and new entrants to thrive, particularly by addressing specific regional needs and offering cost-effective solutions. The market is characterized by a growing emphasis on advanced imaging technologies, increasing awareness of animal health, and rising investments in veterinary infrastructure, driving overall market growth and competitiveness.
Report Coverage
The research report offers an in-depth analysis based on Product, Solutions, Animal Type, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Latin America Veterinary Imaging Market will experience steady growth driven by increasing pet ownership and humanization of pets.
- Technological advancements in imaging equipment will make advanced diagnostic tools more accessible and affordable.
- The market will see greater adoption of portable and digital imaging solutions in veterinary practices.
- There will be a rising demand for specialized imaging techniques such as MRI and CT scans for complex diagnoses.
- Telemedicine and teleradiology will become more prevalent, enhancing access to veterinary diagnostic expertise.
- Cloud-based image storage and management solutions will gain popularity for their improved accessibility and security.
- Investments in training and education for veterinarians and technicians will enhance the effective use of advanced imaging technologies.
- Government initiatives and supportive regulations will promote animal welfare and stimulate market growth.
- The expansion of veterinary clinics and hospitals will drive the need for comprehensive imaging solutions.
- The market will face challenges from high equipment costs and the need for skilled professionals, but these will be mitigated by ongoing advancements and strategic investments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Latin America Veterinary Imaging Market?
What factors are driving the growth of the Latin America Veterinary Imaging Market?
What are the key segments within the Latin America Veterinary Imaging Market?
What are some challenges faced by the Latin America Veterinary Imaging Market?
Who are the major players in the Latin America Veterinary Imaging Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Latin America Veterinary Imaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Latin America Veterinary Imaging Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 129.06 million → forecast year: USD 196.81 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Latin America Veterinary Imaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Latin America Veterinary Imaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Latin America Veterinary Imaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Latin America Veterinary Imaging Market Drivers
- 3.3 Latin America Veterinary Imaging Market Restraints & Challenges
- 3.4 Latin America Veterinary Imaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Latin America Veterinary Imaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Latin America Veterinary Imaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Latin America Veterinary Imaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Latin America Veterinary Imaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Latin America Veterinary Imaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Latin America Veterinary Imaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Latin America Veterinary Imaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Latin America Veterinary Imaging Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Latin America Veterinary Imaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Latin America Veterinary Imaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Latin America Veterinary Imaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Latin America Veterinary Imaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Latin America Veterinary Imaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Latin America Veterinary Imaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Latin America Veterinary Imaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Latin America Veterinary Imaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Latin America Veterinary Imaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Latin America Veterinary Imaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Latin America Veterinary Imaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
