
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Veterinary Artificial Insemination Market Size 2023 | USD 3,158 Million |
| Veterinary Artificial Insemination Market, CAGR | 5.10% |
| Veterinary Artificial Insemination Market Size 2032 | USD 5,239 Million |
Market Overview
The veterinary artificial insemination market has witnessed substantial growth over the past decade, reflecting a burgeoning demand for advanced reproductive technologies in animal breeding practices. With a market size of $3,158 million in 2023, the industry has demonstrated a robust trajectory, underpinned by evolving trends in livestock management and the growing emphasis on genetic improvement. Key factors driving this expansion include the rising awareness among livestock producers regarding the benefits of artificial insemination, such as enhanced breeding efficiency and genetic diversity preservation. Moreover, advancements in technology and the increasing adoption of precision breeding techniques have further propelled market growth, fostering a conducive environment for innovation and investment within the sector.
As of 2024, the veterinary artificial insemination market continues to exhibit promising prospects, driven by a compound annual growth rate (CAGR) of 5.10%. This steady growth trajectory underscores the sustained demand for artificial insemination services and related products across diverse animal species, including cattle, swine, poultry, and equine. With a growing global population and escalating demand for animal-derived products, stakeholders in the livestock industry are increasingly turning to artificial insemination as a means to optimize breeding outcomes, mitigate genetic diseases, and enhance overall herd productivity. As a result, market players are actively investing in research and development initiatives to introduce innovative solutions and streamline the artificial insemination process, thereby catering to the evolving needs of livestock producers worldwide.
Looking ahead, the veterinary artificial insemination market is poised for significant expansion, with industry analysts projecting a market size of $5,239 million by 2032. This bullish forecast reflects the anticipated surge in demand for reproductive technologies, fueled by factors such as increasing per capita meat consumption, expanding dairy production, and the growing popularity of companion animals. Furthermore, shifting consumer preferences towards sustainably sourced and ethically raised livestock products are expected to drive investments in genetic improvement programs and reproductive management practices, thereby augmenting market growth. Against this backdrop, market participants are poised to capitalize on emerging opportunities by leveraging technological innovations, expanding their product portfolios, and forging strategic partnerships to consolidate their foothold in the competitive landscape.
The veterinary artificial insemination market represents a dynamic ecosystem characterized by steady growth and evolving trends in animal reproductive health management. With a projected CAGR of 5.10% from 2023 to 2032, the market is poised to witness substantial expansion driven by increasing demand for advanced breeding solutions and genetic enhancement techniques. As stakeholders continue to prioritize efficiency, productivity, and sustainability in livestock production systems, artificial insemination is poised to play a pivotal role in shaping the future of the global agriculture industry. By fostering collaboration, innovation, and knowledge exchange, market participants can unlock new opportunities and contribute to the advancement of animal welfare, genetic diversity, and food security on a global scale.
Segmentation Analysis
By Animal Type:
- Bovine: This segment dominates the veterinary artificial insemination market owing to the substantial demand for improved genetics in dairy and beef cattle breeding programs.
- Swine: The swine segment exhibits significant growth potential fueled by the increasing adoption of artificial insemination to enhance litter size, meat quality, and disease resistance in pig production.
- Equine: Despite being a niche segment, the equine market for artificial insemination is witnessing steady growth, driven by the demand for superior bloodlines and performance attributes in horse breeding operations.
By Solutions:
- Equipment: This segment encompasses the sale of artificial insemination instruments, including semen straws, catheters, and thawing devices, catering to the needs of veterinary clinics and breeding facilities.
- Services: Veterinary services related to artificial insemination procedures, such as semen collection, storage, and insemination techniques, constitute a significant portion of the market, offering convenience and expertise to livestock producers.
By Distribution Channels:
- Direct Sales: Manufacturers and suppliers of artificial insemination products often engage in direct sales channels, leveraging their expertise to provide customized solutions and technical support to end users.
- Distributors: Distribution networks play a pivotal role in reaching a wider customer base, facilitating product availability and logistical support across diverse geographic regions.
By End User:
- Veterinary Clinics: Veterinary clinics and hospitals are key end users of artificial insemination services, offering reproductive health management solutions to pet owners and livestock producers.
- Animal Breeders: Commercial animal breeders and genetic improvement programs rely heavily on artificial insemination techniques to optimize breeding outcomes and achieve desired genetic traits in their livestock populations.
By Region:
- North America: The North American market for veterinary artificial insemination is driven by robust investments in livestock genetics, stringent quality standards, and a progressive regulatory environment.
- Europe: Europe boasts a mature market for artificial insemination, characterized by high adoption rates, advanced reproductive technologies, and a strong network of veterinary services and research institutions.
- Asia Pacific: The Asia Pacific region presents lucrative growth opportunities fueled by the burgeoning demand for animal protein, increasing disposable incomes, and the adoption of modern farming practices across emerging economies.
Segments
By Animal Type:
- Bovine
- Swine
- Equine
By Solutions:
- Equipment
- Services
By Distribution Channels:
- Direct Sales
- Distributors
By End User:
- Veterinary Clinics
- Animal Breeders
By Region:
- North America
- Europe
- Asia Pacific
Market Drivers
The veterinary artificial insemination market is propelled by several key drivers that collectively contribute to its sustained growth and prominence within the global agricultural landscape. One primary driver is the escalating global demand for animal-derived products, including meat, dairy, and other livestock commodities. As the world population continues to grow, particularly in emerging economies, there is an increased need for efficient and sustainable methods of livestock production to meet the rising demand for protein. Veterinary artificial insemination emerges as a critical solution in this context, enabling livestock producers to enhance breeding efficiency, improve genetic traits, and optimize herd productivity. The method empowers farmers to selectively breed animals with desirable characteristics, such as higher milk yield, superior meat quality, and disease resistance, thereby addressing the challenge of feeding a growing population while maintaining the overall health and quality of livestock.
Another significant driver of the veterinary artificial insemination market is the ongoing technological advancements in reproductive technologies and genetic improvement programs. Continuous innovation in artificial insemination techniques, equipment, and genetic screening tools has revolutionized the field of animal breeding, providing breeders and veterinarians with powerful tools to optimize breeding outcomes. Advanced semen processing methods, including sexed semen technology, have allowed for more precise genetic selection, enabling producers to choose the gender of offspring and enhance the overall genetic quality of their herds. Moreover, the integration of artificial intelligence and data analytics in reproductive management has streamlined decision-making processes for livestock producers, leading to more informed breeding strategies. These technological advancements not only enhance the efficiency of artificial insemination procedures but also contribute to the overall modernization of the livestock industry, fostering sustainable and responsible practices in animal husbandry.
In addition to addressing the global demand for animal products and technological advancements, regulatory support and awareness among livestock producers play pivotal roles in driving the veterinary artificial insemination market. Many governments and regulatory bodies worldwide recognize the importance of improving livestock genetics for economic development and food security. Consequently, they have implemented supportive policies, incentives, and research funding to encourage the adoption of advanced reproductive technologies, including artificial insemination. Furthermore, increasing awareness among livestock producers about the benefits of artificial insemination, such as cost-effectiveness, reduced disease transmission, and improved breeding outcomes, has led to a widespread acceptance of these technologies. As education and outreach initiatives continue to highlight the long-term advantages of veterinary artificial insemination, more farmers are likely to integrate these practices into their breeding programs, further fueling market growth.
Market Trends
Adoption of Sexed Semen Technology:
There is a growing trend towards the adoption of sexed semen technology in the veterinary artificial insemination market. This technology enables livestock producers to predetermine the sex of offspring, allowing for more precise breeding strategies and efficient herd management.
Expansion of Genomic Selection:
Genomic selection techniques are gaining prominence in the veterinary artificial insemination market. By analyzing the genetic makeup of animals, breeders can identify desirable traits and select superior sires and dams for breeding, thereby enhancing the overall genetic quality of livestock populations.
Rising Demand for Companion Animal Reproductive Services:
With the increasing importance of pet ownership and companion animal welfare, there is a rising demand for reproductive services in the veterinary artificial insemination market. Pet owners are seeking advanced reproductive solutions, such as artificial insemination and in vitro fertilization, to facilitate breeding and preserve valuable genetic lines in companion animal species.
Integration of Artificial Intelligence and Data Analytics:
The integration of artificial intelligence (AI) and data analytics is a notable trend in the veterinary artificial insemination market. AI-powered algorithms analyze large datasets to identify patterns, predict breeding outcomes, and optimize breeding strategies, thereby improving the efficiency and accuracy of artificial insemination procedures.
Emphasis on Sustainable Breeding Practices:
There is a growing emphasis on sustainable breeding practices in the veterinary artificial insemination market. Livestock producers are increasingly prioritizing traits such as feed efficiency, disease resistance, and environmental adaptability, aiming to reduce the environmental footprint of animal agriculture while maintaining profitability and productivity.
Development of Novel Insemination Techniques:
Market players are investing in the development of novel insemination techniques to enhance reproductive success rates and minimize procedural risks. Innovations such as transvaginal and laparoscopic insemination methods offer improved precision and efficacy, particularly in challenging breeding scenarios.
Expansion of Online Distribution Channels:
The veterinary artificial insemination market is witnessing a shift towards online distribution channels for the sale and distribution of insemination supplies and services. E-commerce platforms provide convenience, accessibility, and a wide range of product options for livestock producers and veterinary professionals seeking reproductive solutions.
Collaborative Partnerships and Strategic Alliances:
Collaboration and strategic alliances among industry stakeholders are becoming increasingly prevalent in the veterinary artificial insemination market. Partnerships between technology providers, research institutions, and livestock producers facilitate knowledge exchange, innovation, and the development of customized solutions to address evolving market needs.
Focus on Genetic Diversity Preservation:
Preserving genetic diversity is a key trend shaping the veterinary artificial insemination market. Breed associations, conservation organizations, and genetic banks are collaborating to safeguard rare and endangered breeds, leveraging artificial insemination techniques to maintain genetic diversity and prevent genetic erosion.
Regulatory Compliance and Quality Assurance:
Regulatory compliance and quality assurance standards are driving trends in the veterinary artificial insemination market. Adherence to stringent regulatory requirements and quality control measures ensures the safety, efficacy, and ethical use of artificial insemination technologies, fostering trust and confidence among consumers and stakeholders alike.
Market Restraints and Challenges
Cost Barriers:
One of the primary challenges facing the veterinary artificial insemination market is the significant upfront costs associated with implementing and maintaining artificial insemination programs. The initial investment in equipment, semen procurement, and specialized training can pose financial barriers, particularly for small-scale livestock producers and veterinary clinics operating with limited budgets. High operational expenses may deter potential adopters from embracing artificial insemination technologies, limiting market penetration and adoption rates.
Technological Complexity:
The technological complexity of artificial insemination procedures presents a significant challenge for veterinary practitioners and livestock producers alike. Mastery of specialized techniques and equipment operation requires extensive training and hands-on experience, which may not be readily available in all geographic regions. Furthermore, the intricacies of reproductive physiology and breeding management demand a nuanced understanding of animal biology and reproductive cycles, posing additional challenges for inexperienced practitioners and novices entering the field.
Limited Access to Genetic Resources:
Access to high-quality genetic resources is another constraint facing the veterinary artificial insemination market. Breed diversity and genetic variability are essential for maintaining robust livestock populations and breeding programs. However, limited access to genetically superior sires and dams, particularly in niche or rare breeds, can hinder breeding efforts and restrict the genetic diversity of livestock populations. Challenges related to semen collection, storage, and distribution further exacerbate the issue, hindering the availability of diverse genetic material for artificial insemination purposes.
Regulatory Hurdles and Compliance Requirements:
Regulatory hurdles and compliance requirements pose significant challenges for stakeholders in the veterinary artificial insemination market. The industry is subject to stringent regulations governing the collection, processing, storage, and distribution of reproductive materials, including semen and embryos. Adherence to complex regulatory frameworks and quality assurance standards is essential to ensure the safety, efficacy, and ethical use of artificial insemination technologies. However, navigating regulatory complexities and ensuring compliance with evolving legal frameworks can be time-consuming, resource-intensive, and financially burdensome for market participants.
Ethical and Welfare Concerns:
Ethical and welfare considerations surrounding the use of artificial insemination techniques in animal breeding present inherent challenges for the veterinary artificial insemination market. Critics argue that certain insemination practices may compromise animal welfare, raise ethical concerns, or perpetuate genetic disorders and hereditary diseases. Balancing the principles of animal welfare with the objectives of genetic improvement and breeding optimization requires careful consideration and stakeholder engagement to address potential ethical dilemmas and ensure responsible use of artificial insemination technologies.
Key Players
- Genus plc
- Sexing Technologies
- ABS Global
- Select Sires Inc.
- Alta Genetics
- Zoetis Inc.
- Genex Cooperative Inc.
- Cogent
- Viking Genetics
- Semex Alliance
Recent Developments
Genus plc, a global leader in animal genetics, has recently announced significant advancements in its reproductive technologies portfolio. The company has introduced innovative sexed semen solutions, leveraging cutting-edge genetic selection techniques to enhance breeding efficiency and gender-specific genetic improvement in livestock populations. Additionally, Genus plc has expanded its distribution network and strategic partnerships to improve market access and customer support, catering to the evolving needs of livestock producers worldwide.
Sexing Technologies, a pioneer in sexed semen technology, has unveiled groundbreaking developments aimed at revolutionizing reproductive management in livestock species. The company has introduced next-generation sexed semen products with enhanced fertility rates and improved sorting accuracy, offering livestock producers unprecedented control over breeding outcomes. Furthermore, Sexing Technologies has invested in research and development initiatives to explore novel applications of reproductive technologies, including embryo sexing and genomic selection, positioning itself at the forefront of innovation in the veterinary artificial insemination market.
ABS Global, a leading provider of bovine genetics and reproductive solutions, has announced strategic initiatives to enhance its product offerings and customer engagement capabilities. The company has launched a comprehensive suite of genetic testing services, enabling livestock producers to assess the genetic merit of breeding animals and optimize mating decisions for improved herd performance. Moreover, ABS Global has leveraged digital platforms and data analytics to deliver personalized breeding recommendations and actionable insights to its customers, fostering greater efficiency and productivity in animal agriculture.
Select Sires Inc., a renowned cooperative of artificial insemination centers, has introduced innovative genetic programs and breeding strategies aimed at meeting the evolving needs of dairy and beef producers worldwide. The company has expanded its genetic selection criteria to include traits related to environmental sustainability, animal welfare, and consumer preferences, reflecting a growing emphasis on holistic breeding objectives. Additionally, Select Sires Inc. has implemented state-of-the-art reproductive technologies and semen processing techniques to ensure the quality and reliability of its genetic products, maintaining its reputation as a trusted partner in the veterinary artificial insemination market.
Zoetis Inc., a leading animal health company, has made notable investments in research and development to advance reproductive health management in companion animals and livestock species. The company has launched innovative pharmaceuticals and biologics designed to optimize reproductive performance, prevent reproductive disorders, and enhance fertility outcomes in breeding animals. Furthermore, Zoetis Inc. has collaborated with industry partners and academic institutions to drive scientific innovation and knowledge exchange in the field of veterinary artificial insemination, contributing to improved animal welfare and sustainable agricultural practices globally.
Regional Analysis
North America holds a prominent position in the veterinary artificial insemination market, accounting for a significant share of global revenues. With advanced infrastructure, robust research capabilities, and a progressive regulatory environment, the region boasts a market share percentage of approximately 35%. The United States and Canada are key contributors to market growth, driven by a strong culture of innovation, high adoption rates of reproductive technologies, and a thriving livestock industry. Moreover, increasing investments in genetic improvement programs, coupled with rising demand for high-quality animal products, propel the adoption of artificial insemination solutions across diverse animal species, including cattle, swine, and poultry.
Europe represents another major market for veterinary artificial insemination, capturing a substantial market share percentage of around 30%. The region is characterized by a mature market landscape, extensive government support, and a well-established network of veterinary services and research institutions. Countries such as Germany, France, and the Netherlands are at the forefront of technological innovation and genetic research in animal breeding, driving market growth and adoption of advanced reproductive technologies. Furthermore, stringent quality standards, regulatory compliance, and emphasis on animal welfare contribute to the high acceptance of artificial insemination practices among European livestock producers.
The Asia Pacific region is witnessing rapid growth in the veterinary artificial insemination market, with a market share percentage of approximately 25%. Rising population, increasing disposable incomes, and changing dietary preferences are driving the demand for animal-derived products, particularly in emerging economies such as China, India, and Southeast Asian countries. Livestock producers in the region are increasingly embracing artificial insemination techniques to improve breeding outcomes, enhance genetic traits, and optimize herd productivity. Moreover, government initiatives aimed at modernizing agriculture, improving livestock genetics, and promoting sustainable farming practices further accelerate market growth across the Asia Pacific region.
Latin America emerges as a significant market for veterinary artificial insemination, accounting for a market share percentage of approximately 8%. Countries like Brazil, Argentina, and Mexico are leading contributors to market expansion, driven by a thriving livestock industry, favorable climatic conditions, and increasing investments in animal genetics and reproductive technologies. The adoption of artificial insemination solutions is gaining momentum among livestock producers seeking to improve the genetic quality of their herds, increase productivity, and mitigate disease risks. Additionally, supportive government policies, technological advancements, and strategic collaborations with international players fuel market development across the Latin American region.
The Middle East and Africa region represent a growing market opportunity for veterinary artificial insemination, with a market share percentage of approximately 2%. Despite facing challenges related to limited access to technology and infrastructure, the region holds significant potential for market expansion driven by increasing urbanization, rising demand for animal protein, and government initiatives to modernize agriculture. Countries such as South Africa, Kenya, and Saudi Arabia are witnessing increased investments in livestock genetics and reproductive health management, driving the adoption of artificial insemination solutions to enhance breeding efficiency and genetic diversity in domestic animal populations. Continued efforts to address regulatory barriers, improve access to technology, and promote knowledge transfer are essential for unlocking the full potential of the veterinary artificial insemination market in the Middle East and Africa region.
Analyst Opinion
In the veterinary artificial insemination market, analysts hold a positive outlook driven by several factors. Firstly, the increasing global demand for animal-derived products continues to stimulate market growth, prompting livestock producers to seek efficient reproductive solutions to enhance breeding outcomes and genetic diversity. Secondly, advancements in technology, including sexed semen technology and genomic selection, offer unprecedented precision and efficacy in breeding programs, driving adoption rates and market expansion. Additionally, supportive regulatory frameworks and government initiatives aimed at promoting sustainable agriculture and genetic improvement further bolster market dynamics. However, analysts acknowledge challenges such as cost barriers, technological complexities, and regulatory compliance as potential constraints to market growth. Nonetheless, with strategic investments in research and development, collaborative partnerships, and outreach efforts to educate stakeholders, the veterinary artificial insemination market is poised for continued innovation and sustainable growth, catering to the evolving needs of the global livestock industry.
Future Outlook
- The veterinary artificial insemination market is poised for steady expansion driven by rising global demand for high-quality animal genetics and increased adoption of advanced reproductive technologies.
- Ongoing research and development efforts will lead to the emergence of more efficient and precise artificial insemination techniques, enhancing breeding outcomes and genetic selection capabilities.
- There will be a growing emphasis on sustainable breeding practices, with stakeholders prioritizing traits related to environmental resilience, resource efficiency, and animal welfare.
- Emerging economies, particularly in Asia Pacific and Latin America, will present lucrative growth opportunities fueled by increasing urbanization, rising disposable incomes, and changing dietary preferences.
- Digitalization of reproductive management processes will streamline data collection, analysis, and decision-making, empowering livestock producers with actionable insights and predictive analytics.
- Strategic collaborations between industry players, research institutions, and government agencies will foster innovation, knowledge exchange, and market expansion in the veterinary artificial insemination sector.
- Stringent regulatory standards and quality assurance measures will drive market consolidation, ensuring the safety, efficacy, and ethical use of artificial insemination technologies.
- Genetic improvement programs will evolve to incorporate new traits and breeding objectives, aligning with consumer preferences, market trends, and environmental sustainability goals.
- Continued investment in research and development will fuel breakthrough innovations, addressing key challenges and unlocking new opportunities for growth and innovation in the veterinary artificial insemination market.
- Precision breeding techniques, including genomic selection and marker-assisted breeding, will become increasingly mainstream, enabling livestock producers to optimize genetic diversity, improve disease resistance, and enhance overall herd productivity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the veterinary artificial insemination market in 2023 and projected market size for 2032?
What is the Compound Annual Growth Rate (CAGR) of the veterinary artificial insemination market from 2023 to 2032?
What is driving the growth of the veterinary artificial insemination market?
How are technological advancements shaping the future of the veterinary artificial insemination market?
What are some of the challenges faced by stakeholders in the veterinary artificial insemination market?
How is the market expected to evolve in the future?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Veterinary Artificial Insemination Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Veterinary Artificial Insemination Market Snapshot
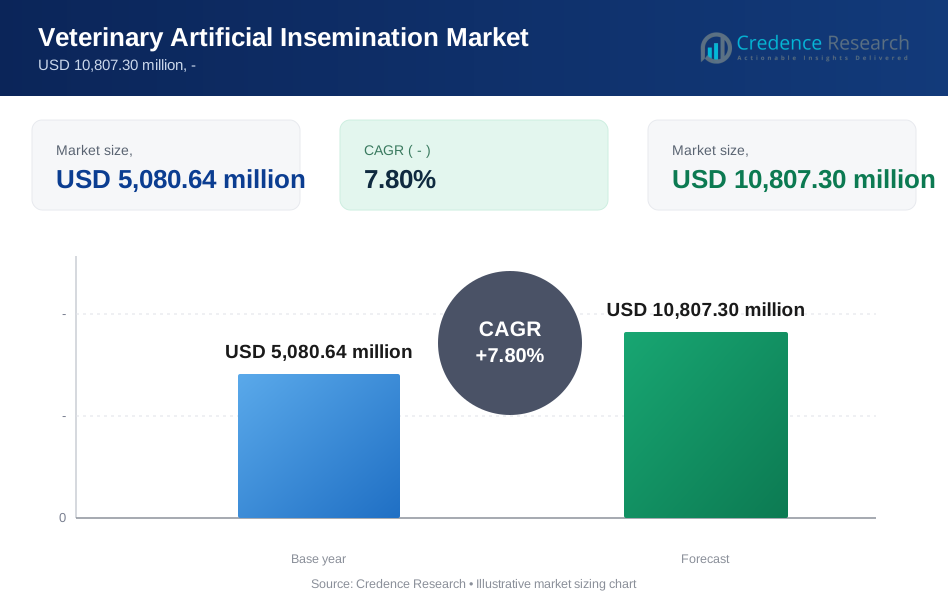
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 5,080.64 million → forecast year: USD 10,807.30 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Veterinary Artificial Insemination Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Veterinary Artificial Insemination Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Veterinary Artificial Insemination Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Veterinary Artificial Insemination Market Drivers
- 3.3 Veterinary Artificial Insemination Market Restraints & Challenges
- 3.4 Veterinary Artificial Insemination Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Veterinary Artificial Insemination Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Veterinary Artificial Insemination Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Veterinary Artificial Insemination category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Veterinary Artificial Insemination Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Veterinary Artificial Insemination Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Veterinary Artificial Insemination market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Veterinary Artificial Insemination Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Veterinary Artificial Insemination Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Veterinary Artificial Insemination Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Veterinary Artificial Insemination (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Veterinary Artificial Insemination Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Veterinary Artificial Insemination Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Veterinary Artificial Insemination Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Veterinary Artificial Insemination Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Veterinary Artificial Insemination Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Veterinary Artificial Insemination Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Veterinary Artificial Insemination Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Veterinary Artificial Insemination Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Veterinary Artificial Insemination Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
