
Market Overview
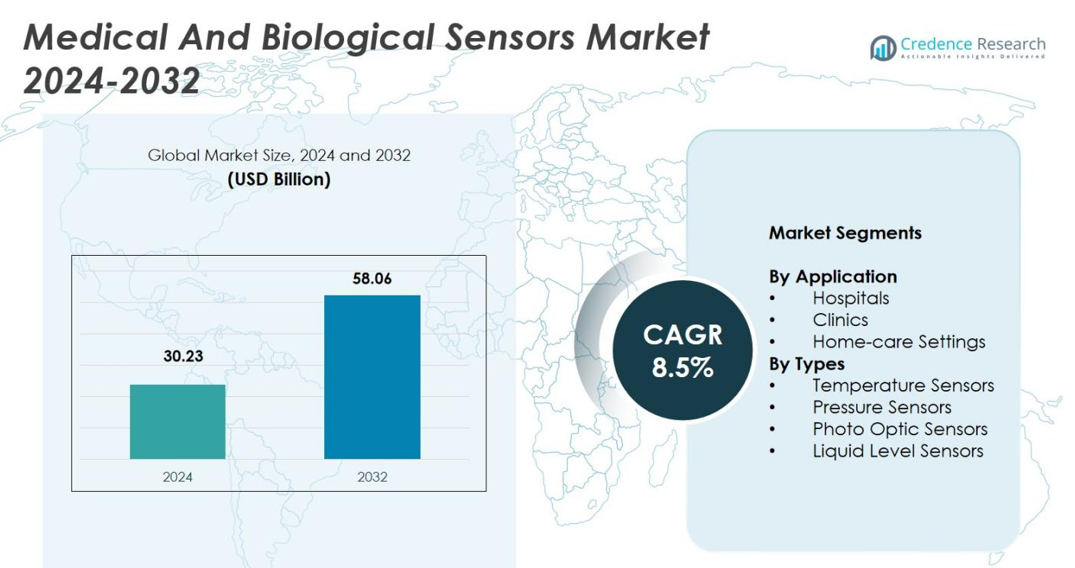
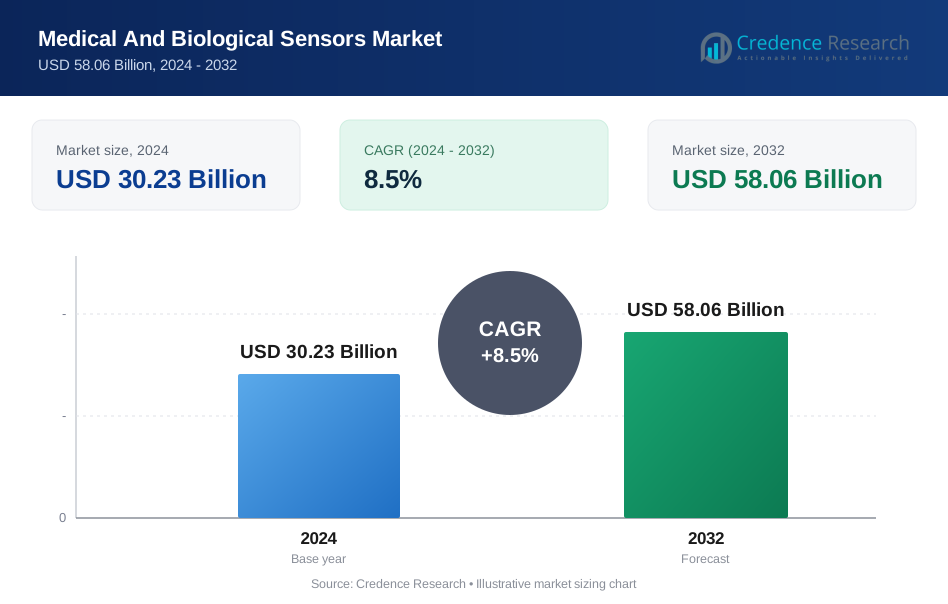
The Medical and Biological Sensors Market size was valued at USD 30.23 Billion in 2024 and is anticipated to reach USD 58.06 Billion by 2032, at a CAGR of 8.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical and Biological Sensors Market Size 2024 | USD 30.23 Billion |
| Medical and Biological Sensors Market, CAGR | 8.5% |
| Medical and Biological Sensors Market Size 2032 | USD 58.06 Billion |
The Medical and Biological Sensors Market is dominated by key players such as Medtronic, Honeywell, GE, TE Connectivity, Analog Devices, and STMicroelectronics. These companies lead through extensive product portfolios, continuous innovation, and strategic partnerships. Medtronic is a major player in the field, particularly in the development of advanced implantable and wearable sensors. Honeywell and GE are prominent in integrating sensor technologies into healthcare systems, driving advancements in diagnostic and monitoring solutions. North America holds the largest market share at 34.6% in 2024, driven by robust healthcare infrastructure and high adoption of advanced medical technologies. Europe follows with 28.3% of the market share, while Asia Pacific, with its rapidly expanding healthcare infrastructure, is the fastest-growing region, accounting for 22.1% of the market in 2024. These regions remain central to the growth trajectory of the medical and biological sensors market.
Market Insights
- The Medical and Biological Sensors Market reached USD 30.23 Billion in 2024 and is forecast to grow at a CAGR of 8.5% through 2032.
- Rapid growth stems from rising prevalence of chronic diseases and increasing demand for continuous monitoring in hospitals, clinics, and home‑care settings.
- Wearable and non‑invasive sensor devices are gaining momentum, enabling real‑time monitoring outside traditional clinical settings and driving higher adoption rates globally.
- Leading application segment Hospitals held 64.0% share in 2024 while temperature sensors accounted for 35.7% of type‑based share, highlighting strong demand for vital‑sign monitoring solutions.
- Regionally, North America remains dominant with 34.6% share in 2024, followed by Europe with 28.3% and Asia Pacific with 22.1%, reflecting robust infrastructure and growing healthcare investments across these geographies.
Market Segmentation Analysis:
By Application
The Hospitals application segment dominates the medical and biological sensors market, accounting for 64.0% of the market share in 2024. This dominance is driven by the increasing patient load, rising cases of chronic diseases, and the need for real-time monitoring of patient vitals in intensive care units (ICUs) and during surgeries. Hospitals continue to invest in advanced sensor technologies to enhance patient outcomes and improve the efficiency of medical workflows. The demand for sensors is particularly strong in critical care environments, where they are essential for monitoring heart rate, blood pressure, oxygen levels, and other vital parameters.
- For instance, GE Healthcare’s CARESCAPE Monitor B650 integrates multiple sensors to provide comprehensive ICU patient monitoring, improving response times.
By Type
Temperature sensors lead the market within the "By Type" category, holding the largest share due to their widespread use in medical diagnostics and patient monitoring systems. These sensors are vital in tracking body temperature, a key indicator in detecting infections and other medical conditions. They are used extensively in hospitals, clinics, and home-care settings, with a market share of 35.7% in 2024. The growth of wearable temperature sensors and the integration of these devices into telemedicine platforms are further driving market expansion. Temperature sensors are favored for their accuracy, low cost, and ability to provide continuous monitoring of patients in diverse care settings.
- For instance, Texas Instruments’ TMP117 sensor offers an accuracy of ±0.1°C and is used in clinical thermometers and wearable health devices.
Key Growth Drivers
Rising Prevalence of Chronic Diseases and Aging Population
The global increase in chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions is fueling demand for continuous monitoring solutions using medical sensors. Simultaneously, the growing elderly population drives demand for long‑term care and remote monitoring - a key factor that expands adoption of medical and biological sensors in both clinical and home‑care environments. This demographic shift underpins strong growth for sensors used in chronic‑disease management and elderly care monitoring.
- For instance, Dexcom's continuous glucose monitoring system has improved real-time diabetes management for millions worldwide.
Advancements in Sensor Miniaturization and IoMT / Connectivity
Progress in micro‑ and nano‑fabrication techniques and the integration of sensors into connected medical devices (IoMT) significantly boost the market. These advances enable compact, non‑invasive, wearable, and implantable sensors with high precision - expanding usability across hospitals, clinics, and home‑care settings. The resulting ease of deployment and improved patient comfort drive accelerated adoption of sensor‑based solutions worldwide.
- For instance, Abbott’s FreeStyle Libre system uses a small, wearable sensor that provides painless glucose monitoring without finger pricks, improving diabetes management.
Growing Shift Toward Home‑Healthcare & Remote Patient Monitoring
Increasing acceptance of home‑based care, coupled with rising healthcare costs and limited hospital capacity in many regions, pushes demand for remote patient monitoring systems. Sensors embedded in wearable or portable devices allow continuous health tracking outside hospitals. This trend gains strength from both patient preference and the need for efficient chronic‑disease management, particularly in regions with aging demographics and growing burden of chronic illness.
Key Trends & Opportunities
Expansion of Wearable and Non‑Invasive Sensor Devices
Wearable and non‑invasive sensor devices including patches, wristbands, and other portable monitors are emerging as a dominant format in medical sensing. Their growth is propelled by demand for comfortable, continuous, real‑time vitals monitoring, preventive care, and fitness–health convergence. This shift opens opportunities for manufacturers to develop user‑friendly, regulatory‑compliant wearables targeting both clinical and consumer segments.
- For instance, Apple's Apple Watch Series 8 features advanced sensors that monitor blood oxygen levels and ECG, enabling users to track heart health continuously.
Integration of AI, Data Analytics and IoT Platforms
Increasing adoption of IoT‑enabled sensors, combined with AI-driven analytics and healthcare data platforms, is transforming traditional medical sensing into integrated health‑management solutions. This convergence enables predictive diagnostics, early disease detection, remote monitoring, and personalized care offering major growth opportunities in telehealth, chronic‑care management, and value-based healthcare models globally.
- For instance, Medtronic's connected insulin pumps leverage data analytics and IoT to personalize diabetes management in real time, improving patient outcomes and reducing hospital visits.
Key Challenges
High Cost of Advanced, High‑Precision Sensors
While advanced wearable and implantable sensors offer rich functionality, their high manufacturing cost driven by precise microfabrication, regulatory compliance, and integration efforts remains a major barrier. This restricts adoption in cost‑sensitive geographies and limits scalability in emerging markets. As a result, the high unit cost of cutting‑edge sensors can hamper broader market penetration.
Regulatory Complexity and Market Fragmentation
The medical sensors market faces challenges stemming from stringent regulatory standards across regions, divergent reimbursement policies, and fragmented healthcare systems. These factors can delay product approval, complicate market entry, and increase compliance costs. Such regulatory and systemic barriers can hinder rapid adoption, especially for innovative sensor technologies and cross‑border deployments.
Regional Analysis
North America
North America leads the global medical and biological sensors market, commanding a market share of 34.6% in 2024. The region’s dominance reflects its advanced, well‑established healthcare infrastructure, robust reimbursement mechanisms, and high adoption of cutting‑edge medical technologies. The presence of major device manufacturers and continuous investment in R&D further strengthen the region’s leadership. Demand is particularly strong in the United States, where chronic disease prevalence, rising health‑consciousness, and widespread use of sensor‑enabled devices in hospitals and home‑care settings drive growth.
Europe
Europe represents the second‑largest regional market for medical and biological sensors, accounting for 28.3% of the global market share in 2024. The region benefits from a large geriatric population, increasing chronic disease incidence, and strong public healthcare expenditure. Well‑defined regulatory frameworks and supportive reimbursement policies facilitate faster adoption of sensor‑based diagnostics and monitoring devices. Continued investments in portable and wearable medical technologies, along with rising demand for non‑invasive diagnostics and preventive care, sustain steady growth in Europe.
Asia Pacific
Asia Pacific stands out as the fastest‑growing regional market, accounting for 22.1% of the global market share in 2024. The region is propelled by rapid urbanization, rising healthcare awareness, and expanding medical infrastructure in countries such as China, India, and Japan. The region sees increasing demand for cost‑effective sensor‑enabled devices in hospitals, clinics, and home‑care settings, fueled by a growing elderly population and rising incidence of chronic diseases. Entry of local manufacturers and rising affordability further drives market penetration, creating significant growth opportunities over the forecast period.
Latin America
Latin America’s medical and biological sensors market is gradually expanding, holding 9.8% of the global market share in 2024. The region is supported by improving healthcare infrastructure, growing public and private investments, and rising adoption of modern medical technologies. As governments and private players upgrade diagnostic and monitoring capabilities, demand for sensor‑based devices in hospitals and clinics increases. The growing prevalence of chronic diseases and rising patient awareness further support uptake. However, the pace of growth remains moderate compared to more mature regions, leaving room for gradual scaling over the forecast period.
Middle East & Africa
The Middle East & Africa region shows emerging potential for medical and biological sensors, representing 5.2% of the global market share in 2024. The region is driven by growing healthcare investment, expanding hospital networks, and increasing demand for modern diagnostics. Rising prevalence of chronic and communicable diseases, together with improving access to healthcare services, propels adoption of sensor‑based monitoring and diagnostic tools. While current market share remains limited compared to developed regions, improving economic conditions and public health initiatives indicate rising growth prospects over the coming years.
Market Segmentations:
By Application
- Hospitals
- Clinics
- Home-care Settings
By Types
- Temperature Sensors
- Pressure Sensors
- Photo Optic Sensors
- Liquid Level Sensors
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive analysis in the medical and biological sensors market reveals a dynamic landscape with key players such as Medtronic, Honeywell, GE, TE Connectivity, Analog Devices, and STMicroelectronics leading the charge. These companies are focusing on expanding their product portfolios, incorporating advanced sensor technologies, and investing in strategic partnerships and acquisitions to maintain market dominance. The competitive environment is marked by a strong emphasis on innovation, with major players integrating cutting-edge technologies like IoT, AI, and miniaturized sensor designs into their offerings. Market growth is fueled by the increasing adoption of wearable, non-invasive, and implantable sensors, with companies targeting both clinical and home-care applications. Additionally, regulatory compliance and robust distribution networks are pivotal for capturing market share, particularly in North America and Europe. To differentiate themselves, leading players are also emphasizing cost-effective solutions and improved patient outcomes, positioning themselves to cater to the growing demand for preventive healthcare and chronic disease management worldwide.
Key Player Analysis
- STMicroelectronics
- Medtronic
- Honeywell
- GE
- Texas Instruments
- NXP
- First Sensor
- Smiths Group
- TE Connectivity
- Analog Devices
Recent Developments
- In October 2024, STMicroelectronics introduced a new bio‑sensing chip designed for next‑generation healthcare wearables including smartwatches, sports bands, connected rings, and smart glasses.
- In June 2025, Sensirion partnered with Sintropy.ai and Repcom and acquired Kuva Systems to accelerate AI‑driven sensor technologies and expand its IoT sensor portfolio.
- In October 2025, a new flexible, antenna‑integrated capacitive sensing platform MAiCaS demonstrated wireless, passive cardiovascular monitoring capabilities, offering a promising route for long‑term patient monitoring without bulky hardware.
Report Coverage
The research report offers an in-depth analysis based on Application, Types and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to experience strong growth due to the increasing demand for wearable and non-invasive sensors.
- Advancements in IoT and AI technologies will enhance the capabilities and efficiency of medical sensors.
- The aging global population will drive significant demand for sensors in chronic disease management and elderly care.
- The rise in home healthcare and remote patient monitoring will open new opportunities for sensor adoption.
- There will be an increasing focus on the development of personalized healthcare solutions powered by medical sensors.
- Rising healthcare costs will accelerate the need for cost-effective, preventative, and home-based monitoring solutions.
- Miniaturization of sensors will enable more compact, portable, and user-friendly devices, improving patient compliance.
- The integration of medical sensors with telemedicine platforms will boost the growth of remote diagnostics and treatment.
- Regulatory advancements and new reimbursement models will facilitate faster adoption of innovative medical sensor technologies.
- Competition will intensify as new entrants and existing players innovate to meet the diverse needs of both clinical and home-care settings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Medical and Biological Sensors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical and Biological Sensors Market projected to grow between 2025 and 2032?
Which technology type segment will post the highest CAGR during the forecast period?
Who are the major global medical and biological sensor market players?
What is the major market driver of the medical and biological sensors industry?
What are the major market restraints of the medical and biological sensors industry?
What are the major market opportunities of the medical and biological sensors industry?
Who are the leading companies in the Medical and Biological Sensors Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Medical And Biological Sensors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Medical And Biological Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 30.23 Billion → 2032: USD 58.06 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Medical And Biological Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Medical And Biological Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Medical And Biological Sensors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Medical And Biological Sensors Market Drivers
- 3.3 Medical And Biological Sensors Market Restraints & Challenges
- 3.4 Medical And Biological Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Medical And Biological Sensors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Medical And Biological Sensors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Medical And Biological Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Medical And Biological Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Medical And Biological Sensors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Medical And Biological Sensors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Medical And Biological Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Medical And Biological Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Medical And Biological Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Medical And Biological Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Medical And Biological Sensors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Medical And Biological Sensors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Medical And Biological Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Medical And Biological Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Medical And Biological Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Medical And Biological Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Medical And Biological Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Medical And Biological Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Medical And Biological Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
