
Key Highlights of the Report
How are the major segments performing in the Medical Packaging Films market?
- In 2022, the polyethylenes (PE)segment accounted for the largest share of the market. The growth can be attributed to its superior chemical resistance, conformability, high flexibility, and good moisture barrier to prevent contamination in the product.
- In 2022, the thermoformable film segment was anticipated to hold a prominent market share in global medical packaging films. With the help of the thermoforming film packaging technique, the packaging sector has seen positive outcomes.
- In 2022, the bags segment was anticipated to hold a prominent share of the global medical packaging film market. Plastic films are still widely used to produce medical bags because they extend shelf life, decrease bacterial contamination, and make them durable for shipping in plastic bags.
- In 2022, the laminations segment was anticipated to hold a prominent share of the global medical packaging film market.
- In 2022, the pharmaceutical segment was anticipated to hold a prominent share of the global medical packaging film market. The pharmaceutical business has experienced a huge increase in packaging demand due to the expanding drug market.
What is the Market Size of Medical Packaging Films regarding value?
The global medical packaging film market is anticipated to grow at a substantial CAGR of 5.20% in the upcoming years. The global medical packaging film industry was estimated to be worth USD 5.9 billion in 2022 and was expected to be worth USD 8.41 billion by 2030.
Which region dominated the Medical Packaging Films market?
In 2022, the Asia Pacific region was anticipated to hold a prominent share of the global Medical Packaging Films market. Due to the increased demand for medical packaging films due to several characteristics like lightweight, sustainability, safety, and cost-effectiveness and the expanding acceptance of sustainable packaging solutions, Asia-Pacific dominates the market for medical packaging films. Because customers in this region are becoming more aware of trash management, Europe is anticipated to have the highest growth rate.
Which are the key countries in the Medical Packaging Films market?
In 2022, the U.S. region was anticipated to hold a prominent share of the North American medical packaging film market. One of the things accelerating this trend is the rising geriatric population. Packaging suppliers have the largest potential for growth possibilities in the region throughout the projected period as pharmaceutical manufacturing as a whole pick-up steam. Additionally, the pharmaceutical packaging sector in the United States is being strengthened by expanding pharmaceutical manufacturing, greater international investments, and expansion in local manufacturing.
In 2022, the China region was anticipated to hold a prominent share of the Asia Pacific medical packaging films market. The market for flexible packaging is very competitive in China, largely due to the country's expanding plastics industry. The flexible packaging market is expanding as more consumers choose practical packaging options. Furthermore, the medical packaging films market in APAC is expanding due to rising chronic diseases and rising healthcare spending in the region, which is the region with the greatest percentage of older people. The primary driver propelling the medical packaging film market is the increase in flexible packaging linked to the rise in plastics used in the medical sector.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Medical Packaging Films Market by Value | Yes |
| Medical Packaging Films Market, Tornado Analysis | Yes |
| Medical Packaging Films Market, STAR Analysis | Yes |
| Medical Packaging Films Market, SRC Analysis | Yes |
| Medical Packaging Films Market Pricing Analysis | Yes (On Demand) |
| Medical Packaging Films Market Segment Analysis | By Material (Polyethylenes (PE), Polypropylene (PP), Polyamide (PA), Polyvinyl Chloride (PVC), and Others) By Type (Thermoformable Film, High Barrier Film, Metallized Film, Others) By Application (Bags, Tubes, Others) By Film Structure (Laminations, Coextrusions, Single Films), End-User (Medical Device, Pharmaceutical) |
| Medical Packaging Films Market, Regional Analysis | North America (US, Canada, Mexico) Europe (Germany, UK, France, Italy, Spain, and Rest of Europe) Asia Pacific (China, India, Japan, South Korea, South East Asia, and Rest of Asia Pacific) Latin America (Brazil, Argentina, and Rest of Latin America) Middle East and Africa (GCC Countries, South Africa, and Rest of the Middle East and Africa) |
| Medical Packaging Films Market Key Companies | Amcor plc; Berry Global Inc.; DuPont.; RENOLIT SE; Weigao group; POLYCINE GmbH; Covestro AG; Glenroy, Inc.; 3M; Wihuri Group; TORAY INTERNATIONAL, INC.; Klöckner Pentaplast; DUNMORE.; TEKRA, LLC.; Coveris.; WINPAK LTD.; Honeywell International Inc; Celanese Corporation; AMERICAN POLYFILM, INC.; Majilite Corporation.; among other domestic and global players. |
| Medical Packaging Films Market Competitive Landscape | Market Share Analysis Competitive Benchmarking Key Players Market Positioning Geographical Presence Analysis Major Strategies Adopted |
How is the economy impacting the growth of global Medical Packaging Films growth?
The lockdown has had several negative effects, including supply chain disruption, labor shortages, and price swings that have caused the product to be overpriced and overproduced due to transportation, finances, etc. Along with losses in other healthcare product manufacturing industries, there was also a decrease in the production of medical packaging. The need for medical packaging has decreased even more due to this general packaging drop.
What is the competitive environment of the Medical Packaging Films market?
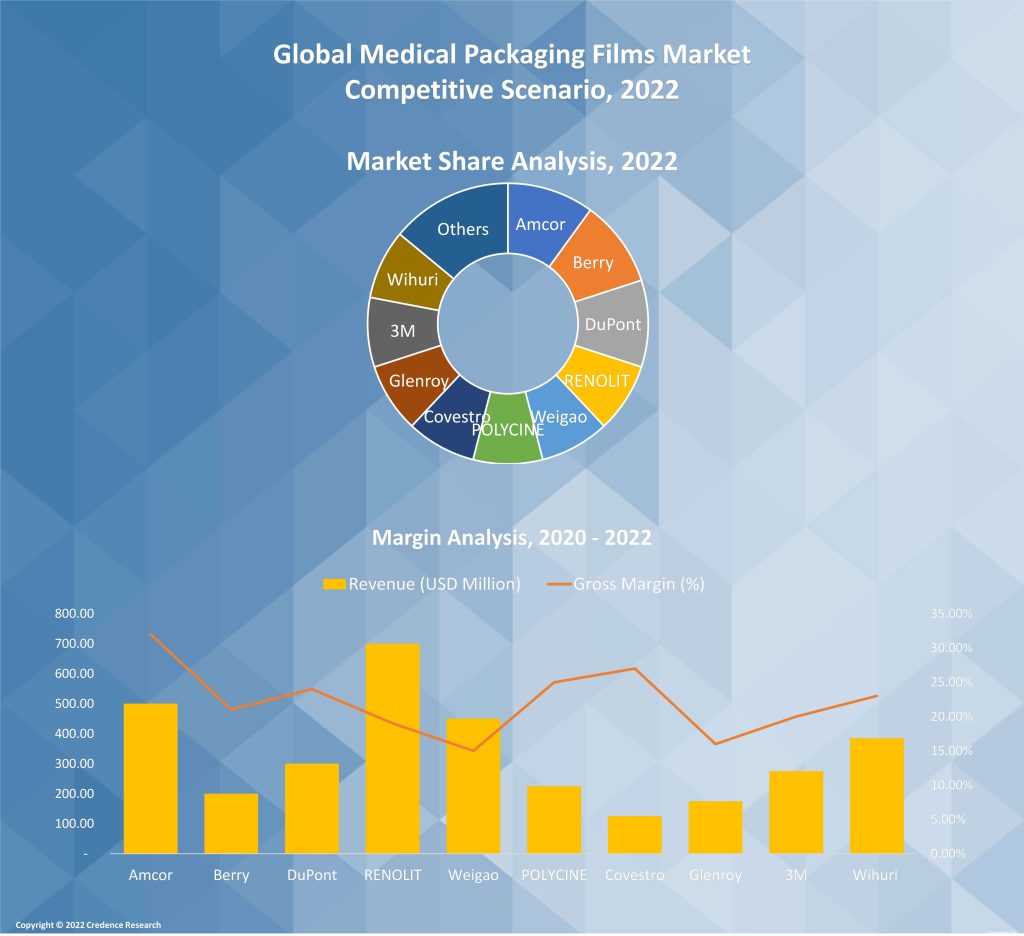
The competitive environment of the medical packaging films industry provides data on the total economic profit made by suppliers and businesses, the sales and revenues generated in this industry, the global market share of medical packaging films, a summary of the business organisation, the launch of new products, and the opportunities for the industrial medical packaging films market. For instance, in July 2021, an investment of roughly USD 80 million was made in a new blown film extrusion factory by Pregis, a global supplier of inventive protective packaging materials, to develop the most recently designed films to produce medical device packaging solutions. Furthermore, in May 2022, to assist manufacturers of pharmaceutical packaging, medical equipment, and associated products in reducing their carbon footprint, Avient launched new bio-based polymer solutions for use in healthcare and pharmaceutical applications at Pharmapack Europe 2022.
Executive Summary
What are the key trends in the Medical Packaging Films market?
Due to the depth and gradient in pocket size that may be created with medical packaging films, blister strips using formed aluminum foil or laminate for the base layer often have a larger footprint than those constructed from that material. Patients or chemists do not prefer larger packs, so manufacturers should consider using high-barrier medical packaging films instead for products requiring a high barrier to moisture. These materials produce smaller footprint blisters while still providing high moisture barrier properties. Calendared blister medical packaging films are becoming increasingly popular in markets like North America and Europe and will soon enter APAC and MEA.
How are Manufacturers Teaming Up with Stakeholders in Medical Packaging Films Market?
Recently, some manufacturers developed sophisticated medical packaging films using several technological advancements. These developments include holographic printing and multi-colored anti-counterfeiting features, cold-formed foils (alu-alu packs), child-resistant films, senior-friendly packaging films, and ultra-high barrier films. Alu-alu packs allow for the virtually complete elimination of water vapor permeability and oxygen and light infiltration. For instance, the Indian company ACG provides a variety of alu-alu packs, child-resistant films, films for older citizens, and thermoformable films with an extremely high barrier. Amcor, Berry Global, Neelam Global in India, and Schur Flexibles in Germany also offer a variety of thermoformable films. These advancements are always in demand and are always offered by packaging companies. These advances in the future will significantly impact the market for medical packaging film.
Which are the key investments by the Medical Packaging Films market players?
The market's top players are concentrating on increasing their production capabilities for medical packaging films. In addition, players are focusing on strategic alliances, partnerships, and raising vendor awareness through a variety of organisations established to encourage smart practises to service more end users in the domestic market in order to acquire a competitive edge. For instance, according to the company's announcement, in August 2018, Bemis Company, Inc. (US) would be acquired by Amcor Limited through an all-stock combination. The transaction is anticipated to cost USD 6.8 billion and close in the first quarter of 2019. This purchase aims to boost R&D capabilities and broaden the geographic reach to meet the demand for environmentally friendly packaging solutions. Amcor shareholders would hold 71% of the combined business under this deal, while Bemis shareholders would hold 29%.
Some major medical packaging film market players are Amcor plc, Berry Global Inc., and DuPont.; RENOLIT SE; Weigao group; POLYCINE GmbH; Covestro AG; Glenroy, Inc.; 3M; Wihuri Group; TORAY INTERNATIONAL, INC.; Klöckner Pentaplast; DUNMORE.; TEKRA, LLC.; Coveris.; WINPAK LTD.; Honeywell International Inc; Celanese Corporation; AMERICAN POLYFILM, INC.; Majilite Corporation.; among other domestic and global players.
What are the Major Driving Factors for the Medical Packaging Films Market?
Increasing demand for bi-axially oriented films, rising use of medical bags for affordable packaging in the pharmaceutical and medical industries, along with those rising preferences for environmentally friendly, biodegradable, cost-effective, and flexible packaging films, rising demand for implantable devices, and rising healthcare facility costs are some examples of trends in the healthcare sector. Other trends include rising implantable device demand, bi-axially oriented film demand, medical bag adoption, and healthcare facility spending. On the other end of the spectrum, rising public awareness of the product's advantages and an increase in the demand for environmentally friendly packaging options will both help fuel the market for medical packaging films during the time predicted above. This will be done by creating a large number of new opportunities. All these major factors contribute to the growth of the medical packaging film market.
What are the Major Risks for the Medical Packaging Films Market?
The erratic nature of commodity prices may harm the market's expansion rate for medical packaging films. Rising crude oil prices and high plastic industry demand cause costs to fluctuate. Crude oil derivatives are the main cost source for flexible packaging films' inputs. 55 to 60 percent of industry sales are typically related to raw material expenses. Because of this, industry revenues are extremely susceptible and act as a roadblock to the market's expansion. The market's expansion is expected to be hampered throughout the forecast period by several other factors, such as the ongoing push for sustainability. This indicates that plastic packaging will replace biodegradable resources and demand post-consumer recycled plastics.
Which is the key type in the Medical Packaging Films market?
During the forecast period, the thermoformable film segment is expected to hold a prominent share in the global medical packaging films market. More than half of the medical packaging films market share was made up of bags. Plastic films continue to be widely used in the production of medical bags because they tend to extend shelf life, minimize bacterial contamination, and make the bags resistant to breaking and shipment of plastic bags. Global technology company Nelipak Healthcare Packaging, based in the US, offers a variety of rigid bag and flexible bag films, including LLDPE bag films and creative packaging solutions.
How is the Medical Packaging Films market performing in regions?
North America is anticipated to witness the fastest growth in the global medical packaging films market during the forecast period. The rise in the number of older adults has greatly increased the market for medical packaging films in North America, and this trend is anticipated to continue throughout the projected period.
What is the regulatory landscape for the Medical Packaging Films market?
The biggest and most important obstacle to the market's expansion will be the numerous environmental restrictions that apply to the packaging of medical products. The Food and Drug Administration must approve medical packaging films before they can be used with a particular medical device. Although the FDA typically oversees medical equipment, choosing appropriate medical packaging films is mostly left up to the device manufacturers. The FDA does not recognize medical packaging films as separate items. The manufacturer of the equipment certifies the medical use of medical packaging films.
What are the major players planning for the future of the Medical Packaging Films market?
It is envisaged that investing in downstream applications and expanding regional presence will give businesses a competitive edge. For instance, in September 2018, Amcor Limited made a USD 25 million investment to upgrade the Madison production facility. The Madison factory creates packaging solutions to increase throughput, enhance quality, decrease waste, and keep up with technology for various items, from food to medical devices.
Segmentation of Global Medical Packaging Films Market-
Global Medical Packaging Films Market – By Material
- Polyethylenes (PE
- Polypropylene (PP)
- Polyamide (PA)
- Polyvinyl Chloride (PVC)
- Others
Global Medical Packaging Films Market – By Type
- Thermoformable Film
- High Barrier Film
- Metallized Film
- Others
Global Medical Packaging Films Market – By Application
- Bags
- Tubes
- Others
Global Medical Packaging Films Market – By Film Structure
- Laminations
- Coextrusions
- Single Films
Global Medical Packaging Films Market – By End-User
- Medical Device
- Pharmaceutical
Global Medical Packaging Films Market – By Region
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How does COVID-19 Impact the global medical packaging films market?
Which is the leading region of the market for medical packaging films?
What are the key drivers for the growth of the medical packaging film market?
Which is the major segment in the medical packaging films market by material?
Which is the major segment in the medical packaging films market by type?
Which is the major segment in the medical packaging films market by application?
Which is the major segment in the medical packaging films market by film structure?
Which is the major segment in the medical packaging films market by the end user?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Medical Packaging Films Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Medical Packaging Films Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: NULL → forecast year: NULL)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Medical Packaging Films Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Medical Packaging Films Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Medical Packaging Films Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Medical Packaging Films Market Drivers
- 3.3 Medical Packaging Films Market Restraints & Challenges
- 3.4 Medical Packaging Films Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Medical Packaging Films Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Medical Packaging Films Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Medical Packaging Films category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Medical Packaging Films Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Medical Packaging Films Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Medical Packaging Films market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Medical Packaging Films Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Medical Packaging Films Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Medical Packaging Films Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Medical Packaging Films (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Medical Packaging Films Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Medical Packaging Films Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Medical Packaging Films Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Medical Packaging Films Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Medical Packaging Films Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Medical Packaging Films Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Medical Packaging Films Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Medical Packaging Films Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Medical Packaging Films Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
