
Paper Filler Market Overview:
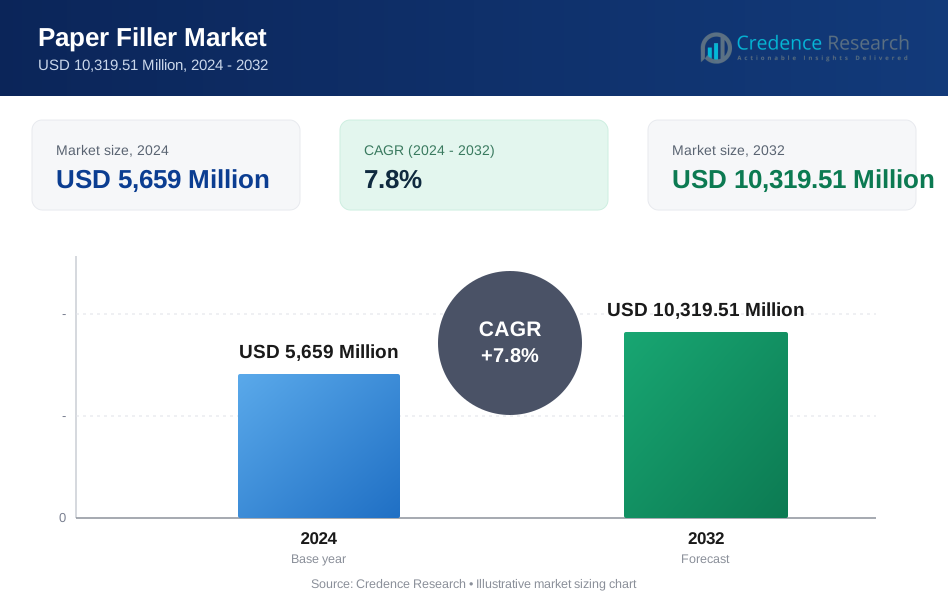
Paper Filler Market size was valued USD 5,659 Million in 2024 and is anticipated to reach USD 10,319.51 Million by 2032, at a CAGR of 7.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Paper Filler Market Size 2024 | USD 5,659 million |
| Paper Filler Market, CAGR | 7.8% |
| Paper Filler Market Size 2032 | USD 10,319.51 million |
Paper Filler Market Insights
- Market overview highlights strong demand from printing, packaging, and specialty paper applications, with Calcium Carbonate (GCC & PCC) leading the type segment with a 58.6% share in 2024 due to its cost-efficiency and performance advantages in brightness and opacity enhancement.
- Markets driver is supported by rising e-commerce packaging, fiber-optimization initiatives, and increasing use of fillers to improve sheet bulk, surface smoothness, and production efficiency across integrated pulp and paper mills.
- Markets trends and analysis show leading players focusing on PCC on-site production, technology partnerships, and product innovations, while companies strengthen portfolios to support lightweight board grades and premium coated paper segments.
- Regional analysis indicates Asia-Pacific held a 36.8% share in 2024 as the leading region, followed by North America with 28.6% and Europe with 24.9%, while Latin America and Middle East & Africa together accounted for the remaining market presence driven by gradual expansion in packaging and tissue production.
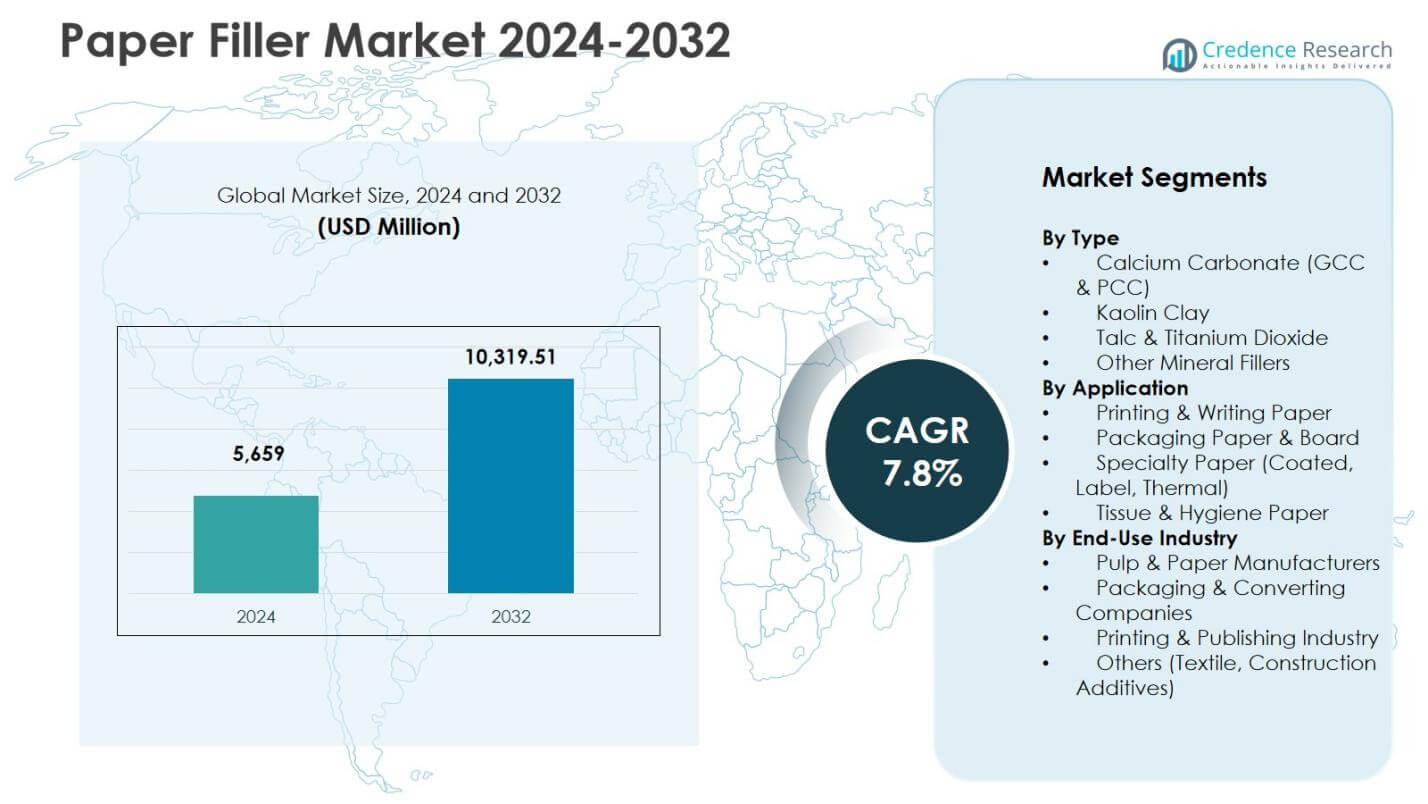
Paper Filler Market Segmentation Analysis:
By Type
The Paper Filler Market by type is led by Calcium Carbonate (GCC & PCC), which accounted for 58.6% share in 2024, making it the dominant sub-segment due to its superior brightness enhancement, cost-reduction capability, and ability to improve opacity and print quality in coated and uncoated papers. Kaolin Clay, Talc & Titanium Dioxide, and Other Mineral Fillers collectively support niche applications, particularly in specialty and premium-grade papers. Growth across this segment is driven by rising demand for high-performance filler formulations, expansion of packaging grades, and increasing adoption of PCC technology in paper manufacturing.
- For instance, Omya's Hydrocarb GCC products provide high-brightness ground calcium carbonates for filling and coating in nearly all paper and board grades, optimizing optical properties and drainage.
By Application
Within the market by application, Printing & Writing Paper emerged as the dominant sub-segment with a 34.2% share in 2024, supported by strong usage of fillers to enhance smoothness, printability, and bulk for office papers, textbooks, and publishing materials. Packaging Paper & Board, Specialty Paper, and Tissue & Hygiene Paper are witnessing rising demand as sustainability initiatives accelerate fiber optimization and lightweight packaging production. Market growth across applications is driven by the shift toward high-brightness coated grades, e-commerce packaging expansion, and performance-enhanced labeling and thermal paper applications across industrial and consumer sectors.
- For instance, Stora Enso launched Optima RF paper in 2024, blending fresh and recycled fibers with optimized fillers for sustainable shopping bags and e-commerce mailers compliant with food contact standards.
By End-Use Industry By end-use industry, Pulp & Paper Manufacturers dominated the market with a 49.7% share in 2024, as integrated mills increasingly adopt fillers to reduce fiber consumption, improve production efficiency, and enhance sheet properties across printing, packaging, and specialty grades. Packaging & Converting Companies, Printing & Publishing Industry, and Others (Textile, Construction Additives) represent growing user segments as fillers gain traction in diversified material applications. Growth in this segment is driven by capacity expansions in paper mills, modernization of coating and filler optimization processes, and the global transition toward sustainable, high-performance paper-based materials.
Key Growth Drivers
Rising Demand for High-Performance Paper and Packaging Grades
Growth in the Paper Filler Market is strongly driven by the increasing need for high-performance paper and packaging materials that offer enhanced brightness, opacity, and print quality while maintaining cost efficiency. Calcium carbonate and kaolin fillers enable paper manufacturers to reduce fiber consumption and improve sheet bulk, strength, and coating smoothness, supporting high-end printing, publishing, and premium packaging applications. The rapid expansion of e-commerce packaging, labeling materials, and coated board grades further accelerates filler consumption, as converters and paper mills prioritize lightweight structures, sustainability compliance, and production efficiency across industrial and consumer packaging ecosystems.
- For instance, Gulshan Polyols Ltd supplies Precipitated Calcium Carbonate (PCC) through onsite plants to ITC Ltd's Hoogly mill in Kolkata, enabling alkaline papermaking with improved brightness and reduced fiber use.
Cost Optimization and Production Efficiency in Paper Manufacturing
Paper fillers play a critical role in reducing production costs and improving operational efficiency across integrated paper mills and coating lines. By replacing a portion of expensive fiber content, fillers such as GCC and PCC help manufacturers optimize raw material costs, enhance machine runnability, and improve sheet formation consistency. This benefit is especially significant in regions facing rising pulp prices and energy costs. The adoption of advanced filler retention systems, PCC on-site production facilities, and filler-fiber optimization technologies is further strengthening market growth as producers aim to achieve higher yield, better surface quality, and competitive margins in paper production.
- For instance, Specialty Minerals Inc. (SMI) operates six onsite PCC plants in India with capacity nearing 300,000 MTPA, producing PCC for over 1.5 million MTPA of paper. These facilities use mill CO2 and local lime to cut transportation costs by up to 50% compared to powder PCC, while enabling tailored fillers for diverse furnishes like hardwood and deinked pulp.
Shift Toward Sustainable and Lightweight Paper Solutions
Sustainability initiatives across packaging, printing, and industrial paper applications are driving the increased use of fillers to support lightweighting and resource-efficient production. Fillers reduce overall paper mass while maintaining or enhancing performance parameters such as opacity, brightness, and print absorption, thereby supporting lower carbon footprints and reduced material consumption. Government regulations promoting recyclable and fiber-efficient paper grades, along with brand owner commitments to eco-friendly packaging, reinforce this trend. The integration of mineral fillers into next-generation coated papers, tissue grades, and specialty papers aligns with evolving sustainability standards and strengthens the long-term demand outlook for the Paper Filler Market.
Key Trends & Opportunities
Technological Advancements in PCC, Coating Formulations, and Filler Functionalization
A major trend shaping the Paper Filler Market is the advancement of precipitated calcium carbonate (PCC) production technologies and functionalized filler formulations designed to enhance paper surface characteristics and machine performance. On-site PCC plants, nano-structured fillers, and composite mineral blends are enabling mills to achieve higher brightness, improved ink absorption, and better coating adhesion across premium printing and packaging grades. This trend creates strong opportunities for technology partnerships between filler producers and paper manufacturers, particularly in high-growth regions with capacity expansion projects. The increasing focus on tailored filler chemistry to support specialty papers, barrier coatings, and labelstock materials further expands innovation-driven market potential.
- For instance, Omya partnered with Domtar's Nekoosa Mill to launch an on-site PCC plant in September 2024, operational since construction completion in July 2024. The facility uses mill CO2 for production, reducing emissions and enhancing production flexibility for paper grades.
Expansion of Packaging, Tissue, and Specialty Paper Applications
The accelerating shift from plastic-based materials to paper-based alternatives across consumer goods, food packaging, e-commerce shipping, and hygiene products is creating significant opportunities for filler adoption. Packaging board, tissue papers, thermal papers, and coated specialty grades are witnessing strong demand growth, and fillers are being increasingly integrated to enhance softness, bulk, strength optimization, and visual aesthetics. Emerging markets in Asia-Pacific, Latin America, and the Middle East are also expanding paper production capacities, generating additional opportunities for filler suppliers. The evolution of sustainable premium packaging, value-added labeling, and advanced printing substrates continues to open new application avenues across industrial and consumer sectors.
- For instance, Nestlé launched high-barrier paper refill packs for Nescafé in the United Kingdom, cutting packaging weight by 97% and enabling full recyclability in paper streams. Fillers such as PCC enhance opacity and smoothness, preserving coffee freshness against oxygen and moisture.
Key Challenges
Volatility in Raw Material Availability and Environmental Compliance Pressures
The Paper Filler Market faces challenges arising from fluctuations in the availability and pricing of key raw materials such as calcium carbonate, kaolin, and talc, particularly in regions dependent on imported mineral resources. Environmental regulations surrounding mining activities, carbon emissions, and waste disposal add compliance costs and operational constraints for filler producers. Additionally, increasing scrutiny on industrial mineral extraction and transportation intensifies sustainability obligations across the value chain. Companies operating in this market must continually invest in environmentally responsible sourcing, energy-efficient processing technologies, and circular economy initiatives to maintain cost competitiveness while meeting evolving regulatory expectations.
Shifting Demand Patterns Due to Digitalization and Declining Printing Paper Consumption
A significant challenge for the Paper Filler Market is the ongoing decline in traditional printing and writing paper demand due to rapid digitalization, electronic documentation, and online media consumption. This structural shift directly affects filler consumption in office papers, publishing materials, and commercial print segments. Although growth in packaging and specialty papers offsets part of this decline, mills operating in mature markets face capacity rationalization and process optimization pressures. The industry must adapt by diversifying toward packaging, labeling, tissue, and industrial paper applications while developing filler technologies aligned with next-generation coated boards and performance-driven specialty substrates.
Regional Analysis
North America
North America held a strong position in the Paper Filler Market with a 28.6% share in 2024, driven by the presence of large-scale paper and packaging manufacturers in the United States and Canada, along with continued demand for coated printing grades, specialty papers, and premium packaging substrates. The region benefits from advanced PCC production facilities, strong integration between paper mills and filler suppliers, and sustained investments in performance-enhancing coating technologies. Growth is further supported by the expansion of e-commerce packaging, sustainability-led fiber optimization initiatives, and increasing adoption of lightweight board grades across consumer goods, labeling, and industrial packaging applications.
Europe
Europe accounted for a 24.9% share in 2024, supported by its well-established pulp and paper industry, strong environmental compliance standards, and high penetration of calcium carbonate-based fillers in printing, packaging, and specialty paper grades. Countries such as Germany, Finland, Sweden, and Italy remain key production hubs, where papermakers emphasize cost efficiency, fiber conservation, and high-brightness coating performance. The region benefits from advanced filler retention systems, R&D collaboration between mineral suppliers and paper mills, and rising demand for recyclable packaging materials, which continues to strengthen filler usage across cartonboard, labelstock, graphical papers, and sustainably engineered coated substrates.
Asia-Pacific
Asia-Pacific dominated the Paper Filler Market with the 36.8% share in 2024, making it the leading regional segment due to rapid expansion of paper and packaging manufacturing in China, India, Indonesia, and Southeast Asia. Strong growth in tissue papers, coated board, printing substrates, and corrugated packaging drives large-scale filler consumption, supported by capacity additions in integrated paper mills and on-site PCC production facilities. Industrial expansion, urbanization, and e-commerce logistics demand accelerate lightweight packaging adoption, while regional producers increasingly focus on production efficiency, brightness optimization, and cost-effective filler utilization across diversified paper and converting applications.
Latin America
Latin America captured a 6.7% share in 2024, driven by gradual expansion of packaging paper, tissue grades, and industrial board manufacturing in Brazil, Mexico, Chile, and Colombia. Paper fillers are increasingly adopted to improve sheet smoothness, opacity, and production economics in mills focused on export-oriented packaging and domestic consumer goods applications. Investment in modern paper machines, coating lines, and filler incorporation technologies is strengthening the region’s market growth. Rising retail packaging demand, infrastructure development, and agricultural export packaging further support the adoption of GCC and PCC fillers across containerboard, printing substrates, and specialty paper segments.
Middle East & Africa
The Middle East & Africa region accounted for a 3.0% share in 2024, representing an emerging growth market supported by ongoing industrial development, packaging consumption expansion, and increasing adoption of paper-based materials in logistics, food packaging, and retail sectors. The region relies significantly on imported paper and filler materials, while new investments in converting operations and packaging board production are gradually increasing local demand. Sustainability-driven material transitions, growth in tissue and hygiene paper consumption, and rising capacity additions in select African economies are expected to enhance filler utilization across packaging, printing, and specialty paper applications over the forecast period.
Paper Filler Market Segmentations:
By Type
- Calcium Carbonate (GCC & PCC)
- Kaolin Clay
- Talc & Titanium Dioxide
- Other Mineral Fillers
By Application
- Printing & Writing Paper
- Packaging Paper & Board
- Specialty Paper (Coated, Label, Thermal)
- Tissue & Hygiene Paper
By End-Use Industry
- Pulp & Paper Manufacturers
- Packaging & Converting Companies
- Printing & Publishing Industry
- Others (Textile, Construction Additives)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Paper Filler Market is characterized by the presence of leading players such as Imerys S.A., Omya International AG, Minerals Technologies Inc., BASF SE, Huber Engineered Materials, J.M. Huber Corporation, Ashapura Group, and Nippon Paper Industries. These companies focus on capacity expansion, technology integration, and value-added filler formulations to strengthen their market positions across printing, packaging, tissue, and specialty paper applications. Market participants actively invest in on-site PCC production facilities, sustainability-aligned mineral sourcing, and performance-enhancement solutions that improve brightness, opacity, and production efficiency for paper manufacturers. Strategic partnerships with integrated mills, R&D collaboration for functionalized filler development, and product innovation targeting lightweight and eco-efficient paper grades remain key differentiation factors. The market also witnesses increasing emphasis on regional supply chain optimization, tailored filler chemistries for specialty substrates, and portfolio diversification to address evolving demand patterns across both mature and high-growth paper-producing regions.
Key Player Analysis
- Imerys S.A.
- Omya International AG
- Minerals Technologies Inc. (MTI)
- Precipitated Calcium Carbonate Industries Co. (PCCIC)
- Huber Engineered Materials
- BASF SE
- Ashapura Group
- I-Minerals Inc.
- J.M. Huber Corporation
- Nippon Paper Industries Co., Ltd.
Recent Developments
- In November 2025, Omya launched a global Specialty Materials Business Unit to enhance sales and distribution of specialty mineral products, including solutions relevant to paper fillers.
- In July 2025, SIG entered a strategic partnership with PulPac to develop paper-based closures using Dry Molded Fiber technology, advancing sustainable packaging alternatives in the broader paper sector.
- In 2024, EcoEnclose LLC introduced ReShred Pack, a customizable shredded filler from 100% recycled paper targeted at premium e-commerce brands prioritizing sustainability.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as demand increases for high-performance paper and packaging materials across industrial and consumer sectors.
- Manufacturers will continue to adopt mineral fillers to enhance brightness, opacity, and print quality while improving production efficiency.
- The expansion of e-commerce, labeling, and coated board applications will strengthen filler consumption in packaging and converting industries.
- Sustainability initiatives will drive wider integration of fillers to support lightweighting, fiber optimization, and resource-efficient paper manufacturing.
- Technological advancements in PCC production and functionalized filler formulations will enable improved surface properties and machine runnability.
- Emerging economies in Asia-Pacific, Latin America, and Africa will create new growth opportunities through capacity expansion in paper and tissue manufacturing.
- Strategic partnerships between filler suppliers and paper mills will increase to support customized filler solutions and process optimization.
- Specialty paper, tissue, and premium coated grades will gain traction as value-added application areas for filler-based performance enhancement.
- Market players will focus on sustainability-aligned sourcing, energy-efficient processing, and circular economy initiatives across the value chain.
- Ongoing industry consolidation and portfolio expansion will reshape competitive positioning and strengthen global supply capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Paper Filler Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Paper Filler Market projected to grow between 2024 and 2032?
Which Paper Filler Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Paper Filler Market?
Who are the leading companies in the Paper Filler Market?
Which region commanded the largest share of the Paper Filler Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Paper Filler Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Paper Filler Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,659 Million → 2032: USD 10,319.51 Million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Paper Filler Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Paper Filler Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Paper Filler Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Paper Filler Market Drivers
- 3.3 Paper Filler Market Restraints & Challenges
- 3.4 Paper Filler Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Paper Filler Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Paper Filler Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Paper Filler category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Paper Filler Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Paper Filler Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Paper Filler. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Paper Filler Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Paper Filler Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Paper Filler Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Paper Filler (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Paper Filler
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Paper Filler Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Paper Filler Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Paper Filler Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Paper Filler Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Paper Filler Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Paper Filler Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Paper Filler Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Paper Filler Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
