
Wine Bags Market Overview:
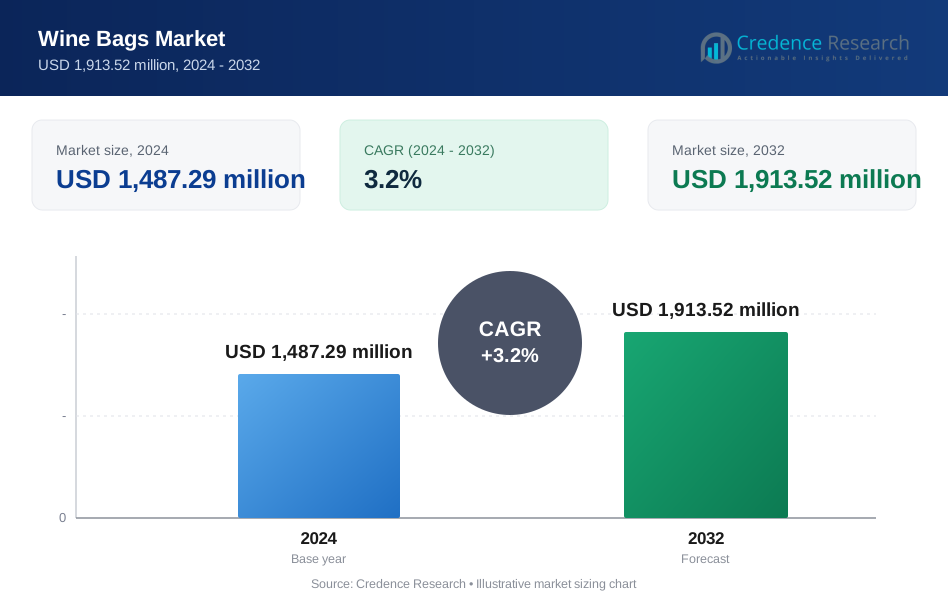
The wine bags market was valued at USD 1,487.29 million in 2024 and is anticipated to reach USD 1,913.52 million by 2032, expanding at a compound annual growth rate (CAGR) of 3.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Wine Bags Market Size 2024 | USD 1,487.29 million |
| Wine Bags Market, CAGR | 3.2% |
| Wine Bags Market Size 2032 | USD 1,913.52 million |
Wine Bags Market Insights
- Market growth is driven by rising wine gifting culture, premiumization of wine packaging, and expanding organized retail and e-commerce channels, with reusable wine bags emerging as the dominant product segment due to durability, branding value, and sustainability appeal, accounting for the largest segment share.
- Key market trends include increasing adoption of eco-friendly paper and fabric wine bags, growing customization for corporate gifting and winery branding, and rising demand for single-bottle wine bags, which hold a higher share than multi-bottle formats due to convenience and lower cost.
- The competitive landscape remains fragmented, with manufacturers competing on material innovation, design capabilities, pricing, and sustainable sourcing, while strong retailer and winery partnerships provide volume stability and brand visibility.
- Regionally, North America leads with ~35% market share, followed by Europe at ~29% and Asia Pacific at ~23%, with Asia Pacific showing the fastest growth driven by rising wine consumption and gifting demand.

Wine Bags Market Segmentation Analysis:
By Material:
The wine bags market by material is led by paper bags, which account for an estimated 42-45% market share, driven by growing preference for recyclable, biodegradable, and premium-looking packaging in retail and gifting applications. Paper wine bags benefit from strong branding surfaces, cost efficiency, and alignment with sustainability mandates adopted by wineries and liquor retailers. Plastic bags follow, supported by durability, moisture resistance, and lower unit costs in mass retail, while fabric bags occupy a smaller but premium niche, favored for luxury gifting, wineries, and reusable merchandising due to their durability and aesthetic appeal.
- "For instance, Uline Distributor reusable non-woven polypropylene wine bags made from 100 g/m² fabric, making them suitable for winery tasting rooms and premium gift programs where long service life and visual appeal are prioritized."
By Product Type:
By product type, reusable wine bags dominate the market with approximately 60-65% share, supported by sustainability initiatives, repeat-use value, and increasing consumer preference for eco-conscious packaging solutions. Retailers and wineries increasingly promote reusable formats to enhance brand perception and reduce single-use waste. Reusable bags also benefit from higher margins and premium positioning. Disposable wine bags, while still relevant in high-volume promotional and event-driven sales, face slower growth as regulatory pressure on single-use packaging and shifting consumer attitudes favor long-lasting, environmentally responsible alternatives.
- For instance, Packhelp provides reusable cotton bags suitable for bottled products, including those made from GOTS-certified organic cottonor recycled textiles. While standard options often feature a 150 g/m² grammage for a balance of lightness and strength, premium versions can reach 360 g/m² for carrying heavier items.
By Capacity:
By capacity, single bottle wine bags represent the dominant sub-segment, holding around 68-72% of market share, driven by widespread use in retail purchases, gifting occasions, and point-of-sale packaging. Their compact design, lower material consumption, and compatibility with standard wine bottle sizes make them the preferred choice for wineries and retailers. Multi bottle wine bags serve a growing but secondary segment, supported by corporate gifting, festive bundles, and bulk purchases, particularly in premium and seasonal sales channels where higher-value packaging enhances presentation and convenience.
Key Growth Driver
Rising Demand for Premium and Gift-Oriented Packaging
The wine bags market is strongly driven by the growing emphasis on premium packaging and gifting aesthetics within the global wine industry. Wine is increasingly purchased as a lifestyle and celebratory product, prompting consumers and retailers to prioritize visually appealing, well-structured, and protective packaging solutions. Wine bags enhance shelf appeal and gifting value, particularly during festive seasons, corporate gifting events, and special occasions. Retailers and wineries leverage wine bags to reinforce brand identity through customized prints, textures, and finishes, positioning them as extensions of the product itself rather than simple carriers. This shift is especially evident in specialty wine stores, duty-free outlets, and e-commerce platforms, where presentation influences purchasing decisions. The growth of premium and artisanal wines further amplifies demand for high-quality paper, fabric, and reusable wine bags that convey sophistication while offering functional protection during transport.
- For instance, DS Smith(now integrated with International Paper in the U.S. as of 2025) provides premium wine packaging utilizing White Liner and specialty paperboard in the 170-250 g/m² Their luxury gifting solutions incorporate reinforced handles designed to safely support standard 750ml wine bottles (approx. 1.3 kg) while exceeding typical durability requirements for the duty-free and retail sectors.
Expansion of Wine Retail and E-Commerce Channels
The rapid expansion of organized wine retail and online sales channels significantly fuels demand for wine bags. Supermarkets, hypermarkets, specialty wine shops, and digital marketplaces increasingly require standardized, durable, and branded wine packaging to support in-store merchandising and last-mile delivery. Wine bags provide convenience, safety, and portability, making them suitable for both impulse purchases and bulk orders. E-commerce growth, in particular, has increased the need for packaging that balances protection with lightweight design to optimize logistics costs. Single-bottle and multi-bottle wine bags are widely adopted to minimize breakage risks and enhance customer experience during delivery. Additionally, the rise of direct-to-consumer winery sales encourages the use of customized wine bags as a branding and customer retention tool, further accelerating market growth across developed and emerging regions.
- For instance, Mondi supplies paper-based bottle carriers for retail and e-commerce channels manufactured from corrugated or solid board, incorporating reinforced bottoms and integrated or twisted paper handles validated to carry loads suitable for safe transport of up to six standard 750 ml glass wine bottles, while maintaining flat-pack designs optimized for high-volume supermarket distribution and online order fulfillment.
Increasing Focus on Sustainable and Eco-Friendly Packaging
Sustainability considerations are a major growth driver shaping the wine bags market. Consumers, retailers, and regulatory bodies increasingly favor environmentally responsible packaging solutions, pushing demand for recyclable, biodegradable, and reusable wine bags. Paper-based and fabric wine bags are gaining traction as alternatives to conventional plastic packaging due to their lower environmental footprint and positive brand perception. Wine producers and retailers are actively aligning packaging strategies with sustainability goals to meet consumer expectations and corporate responsibility commitments. Reusable wine bags, in particular, appeal to environmentally conscious buyers seeking durable solutions that reduce single-use waste. This shift not only supports regulatory compliance in several regions but also enhances brand loyalty, making sustainability a central factor driving long-term adoption of wine bags.
Key Trend & Opportunity
Customization and Brand-Centric Design Innovation
Customization has emerged as a key trend and growth opportunity in the wine bags market. Brands increasingly invest in bespoke designs, premium finishes, and tailored formats to differentiate their products in competitive retail environments. Wine bags now serve as marketing tools, featuring logos, storytelling elements, and region-specific artwork that enhance brand recall. Advances in printing and material technology enable short-run customization, allowing wineries and retailers to respond quickly to seasonal campaigns and limited-edition releases. This trend creates opportunities for manufacturers to offer value-added services such as design collaboration, sustainable inks, and premium textures, thereby strengthening margins and customer relationships.
- "For instance, Smurfit Westrock provides high-graphic beverage packaging, including premium paper sacks and carriers, through an integrated network of digital preprint and offset printing Their short-run printing services use a 'test-learn-scale' approach designed to support test markets and boutique brands with small-volume production without the need for traditional print plates.
Growth of Reusable and Multi-Functional Wine Bags
Reusable and multi-functional wine bags represent a growing opportunity driven by changing consumer behavior. Buyers increasingly favor products that offer extended utility beyond a single purchase, such as wine bags that double as grocery totes or gift carriers. Fabric and reinforced paper wine bags meet this demand by combining durability with aesthetic appeal. This trend aligns closely with sustainability goals while encouraging repeat brand exposure through prolonged use. Manufacturers that innovate in durability, ergonomic design, and material blends are well positioned to capture this opportunity, particularly in urban and environmentally aware consumer segments.
- For instance, Bagmasters supplies a variety of reusable canvas totes and wine bags, including products made from 12 oz cotton canvas that are designed for high durability.
Key Challenge
Price Sensitivity and Cost Pressures
Price sensitivity remains a key challenge for the wine bags market, particularly in mass retail and price-competitive regions. While premium and sustainable wine bags offer clear value, their higher production costs can limit adoption among cost-conscious retailers and consumers. Fluctuations in raw material prices, including paper pulp, textiles, and specialty coatings, further strain profit margins for manufacturers. Balancing quality, sustainability, and affordability is a persistent challenge, especially for disposable wine bags that compete with low-cost alternatives.
Competition from Alternative Packaging Solutions
The wine bags market faces competition from alternative packaging formats such as cardboard carriers, molded pulp holders, and protective shipping boxes. These alternatives often integrate directly into logistics and shelf-ready packaging systems, reducing the perceived need for separate wine bags. In e-commerce, protective corrugated packaging may replace traditional wine bags altogether. To remain competitive, wine bag manufacturers must emphasize differentiation through design, reusability, sustainability, and branding value, ensuring their products complement rather than compete with evolving wine packaging ecosystems.
Regional Analysis
North America
North America represents the leading regional market for wine bags, accounting for approximately 34-36% of global market share. The region benefits from high wine consumption, a strong gifting culture, and well-established retail and e-commerce channels. The U.S. dominates regional demand, driven by premium wine purchases, seasonal gifting, and corporate events where branded wine bags are widely used. Sustainability trends further support demand for paper and reusable fabric wine bags, particularly in urban markets. Canada contributes steadily through specialty wine stores and duty-free retail. Strong presence of organized retail and direct-to-consumer winery sales sustains consistent adoption across the region.
Europe
Europe holds around 28-30% of the global wine bags market, supported by its position as the world’s largest wine-producing and wine-consuming region. Countries such as France, Italy, Spain, and Germany drive demand through mature wine retail ecosystems and strong emphasis on presentation and heritage branding. Wine bags are widely used in specialty stores, vineyards, and tourism-driven purchases. Sustainability regulations across the EU accelerate adoption of recyclable paper and reusable fabric wine bags. Premium gifting traditions and winery-led branding initiatives further strengthen demand, making Europe a stable and design-driven regional market.
Asia Pacific
Asia Pacific accounts for approximately 22-24% of global market share and represents the fastest-growing regional market. Rising wine consumption in China, Japan, South Korea, and Australia, combined with increasing disposable incomes, supports expanding demand for wine bags. Gifting culture plays a critical role, particularly in East Asia, where presentation strongly influences purchase decisions. Growth in organized retail, e-commerce wine platforms, and imported wine sales accelerates adoption of both single and multi-bottle wine bags. Manufacturers increasingly focus on customized and premium designs to align with regional gifting preferences and urban lifestyle trends.
Latin America
Latin America contributes around 7-9% of the global wine bags market, with growth driven by expanding wine consumption and improving retail infrastructure. Argentina and Chile, as major wine producers, support steady demand from wineries, tourism channels, and domestic retail. Brazil shows rising adoption due to growing middle-class consumption and increased availability of imported wines. Wine bags are primarily used for gifting and specialty retail rather than mass distribution. While price sensitivity remains high, gradual premiumization of wine consumption and sustainability awareness are expected to support moderate long-term growth.
Middle East & Africa
The Middle East & Africa region holds approximately 4-6% of global market share, reflecting selective but steadily expanding demand. Growth is concentrated in urban centers, travel retail, and hospitality-driven markets such as the UAE and South Africa. Duty-free outlets, luxury gifting, and expatriate populations support demand for premium wine bags, particularly reusable and fabric variants. Regulatory constraints limit widespread wine sales in parts of the Middle East, but tourism and high-end retail sustain niche demand. In Africa, South Africa leads adoption through established wine production and export-oriented branding initiatives.
Wine Bags Market Segmentations:
By Material:
- Paper Bags
- Plastic Bags
- Fabric Bags
By Product Type:
- Reusable Wine Bags
- Disposable Wine Bags
By Capacity:
- Single Bottle Wine Bags
- Multi Bottle Wine Bags
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The wine bags market features a fragmented yet competitive landscape characterized by the presence of regional packaging manufacturers, specialty paper and fabric bag producers, and a limited number of global players with diversified packaging portfolios. Competition primarily centers on material innovation, customization capabilities, pricing efficiency, and sustainability credentials.
Manufacturers increasingly differentiate through recyclable paper bags, reusable fabric formats, and premium finishes that cater to gifting and branding requirements. Strong relationships with wineries, specialty wine retailers, and large retail chains provide a competitive advantage, enabling consistent order volumes and private-label contracts. Companies with in-house design and short-run customization capabilities respond more effectively to seasonal demand and promotional campaigns.
Additionally, suppliers that align with environmental regulations and corporate sustainability goals strengthen their market positioning. As e-commerce and direct-to-consumer wine sales expand, competitive intensity continues to rise, encouraging ongoing product differentiation, operational efficiency, and value-added service offerings.
Key Player Analysis
- Acorn Paper Products
- BUILT NY
- DM Pack
- Factory Direct Promos
- Green Packaging Industries Pvt. Ltd.
- Initi Bag Manufacturer
- Nangfa Manufacturing
- PaperPak
- Richie Bags
- Wine Box Company Limited
Recent Developments
- In November 2025 Factory Direct Promos importing reusable shopping/wine bag shipments (e.g., 550 kg batch of shopping/wine bag material arriving 23 Nov 2025), indicating ongoing procurement and inventory build-outs tied to its promotional wine bag lines.
- In August 2025, PaperPak launched its 2025 Christmas Range of recyclable retail packaging solutions, featuring updated wine bottle and wine gift bag formats designed for seasonal retail and gifting occasions. This collection includes recyclable wine bottle bags with varied handle styles (twisted paper, rope, die-cut) and personalised printing options catering to brand identity and festive presentation needs in Australia and New Zealand.
Report Coverage
The research report offers an in-depth analysis based on Material, Product type, Capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Premium and Gift-Oriented Packaging Demand
The growing trend of wine as a lifestyle and celebratory product is increasing the need for visually appealing, premium wine bags that enhance gifting value and shelf appeal. Retailers and wineries use customized, high-quality bags to reinforce brand identity and attract consumers during festive and corporate gifting occasions.
Expansion of Wine Retail and E-Commerce Channels
The proliferation of organized retail and online wine sales is driving demand for standardized, durable, and branded wine bags that support both in-store merchandising and secure last-mile delivery. E-commerce growth, in particular, requires packaging that balances protection with lightweight design for cost-effective logistics.
Sustainability and Eco-Friendly Packaging
Rising consumer and regulatory focus on sustainability is accelerating the adoption of recyclable, biodegradable, and reusable wine bags, especially paper and fabric variants. Brands are aligning packaging strategies with environmental goals to meet consumer expectations and enhance brand loyalty.
Customization and Brand-Centric Design Innovation
Brands are increasingly investing in bespoke wine bag designs, premium finishes, and tailored formats to differentiate their products and enhance marketing impact. Advances in printing and material technology enable short-run customization, supporting seasonal campaigns and limited-edition releases.
Growth of Reusable and Multi-Functional Wine Bags
Consumer preference is shifting toward reusable and multi-functional wine bags that offer extended utility, such as doubling as grocery totes or gift carriers. This trend supports sustainability goals and encourages repeat brand exposure, especially in urban and environmentally conscious markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for wine bags, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the wine bags market projected to grow between 2024 and 2032?
Which wine bags segment held the largest share in 2024?
What are the primary factors fueling the growth of the wine bags market?
Who are the leading companies in the wine bags market?
Which region commanded the largest share of the wine bags market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 Single Bottle Wine Bags
- 1.2.2 Multi Bottle Wine Bags
- 1.3 By Material
- 1.3.1 Paper Bags
- 1.3.2 Plastic Bags
- 1.3.3 Fabric Bags
- 1.4 By Product Type
- 1.4.1 Reusable Wine Bags
- 1.4.2 Disposable Wine Bags
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,487.29 million → 2032: USD 1,913.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wine Bags Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wine Bags Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wine Bags Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wine Bags Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wine Bags Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wine Bags Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wine Bags Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wine Bags Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,487.29 million → 2032: USD 1,913.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wine Bags Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Bottle Wine Bags
- 12.3.7.2 Multi Bottle Wine Bags
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Paper Bags
- 12.4.7.2 Plastic Bags
- 12.4.7.3 Fabric Bags
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Reusable Wine Bags
- 12.5.7.2 Disposable Wine Bags
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wine Bags Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Wine Bags Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Wine Bags Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Acorn Paper Products
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 BUILT NY
- 17.4 DM Pack
- 17.5 Factory Direct Promos
- 17.6 Green Packaging Industries Pvt. Ltd.
- 17.7 Initi Bag Manufacturer
- 17.8 Nangfa Manufacturing
- 17.9 PaperPak
- 17.10 Richie Bags
- 17.11 Wine Box Company Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

