
Ultra High Bond Tape Market Overview:
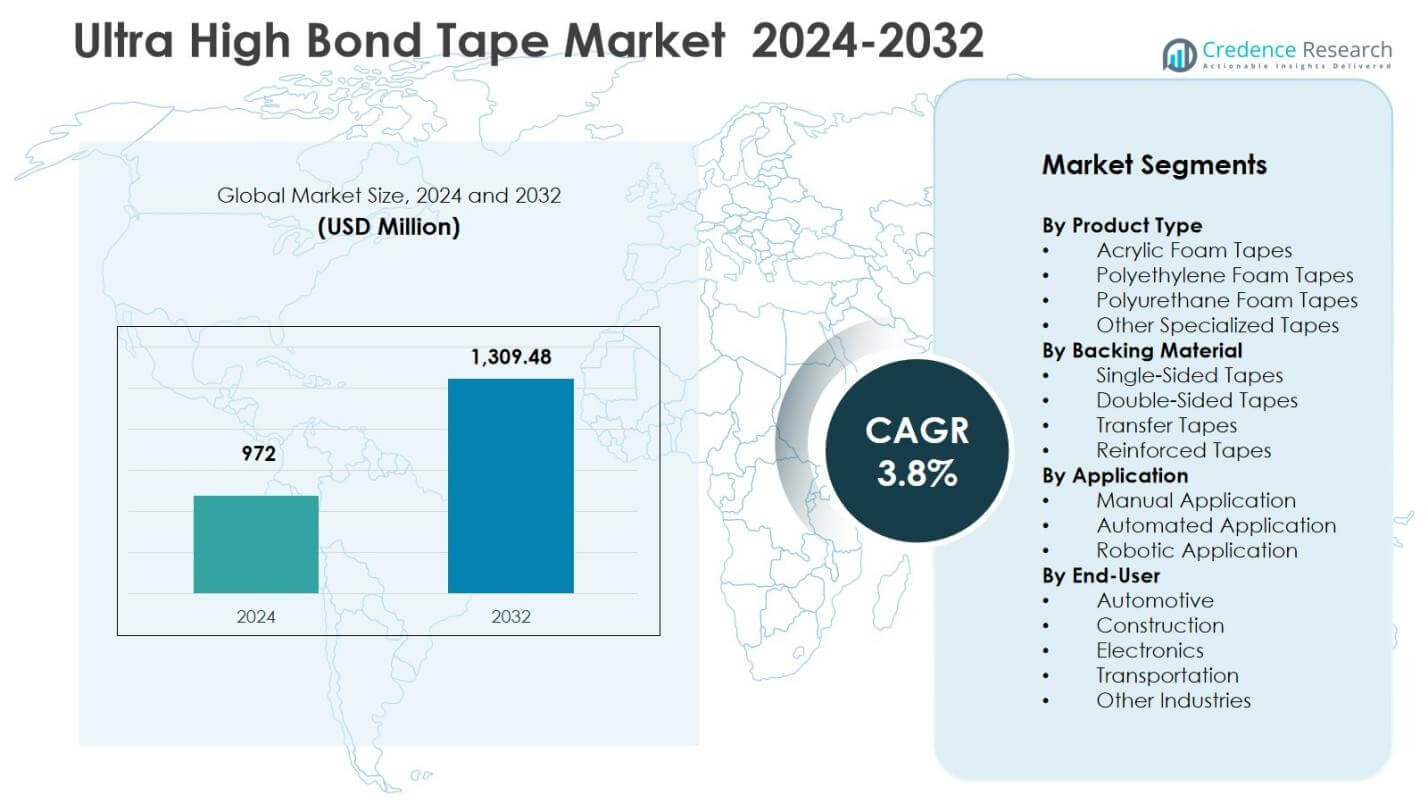
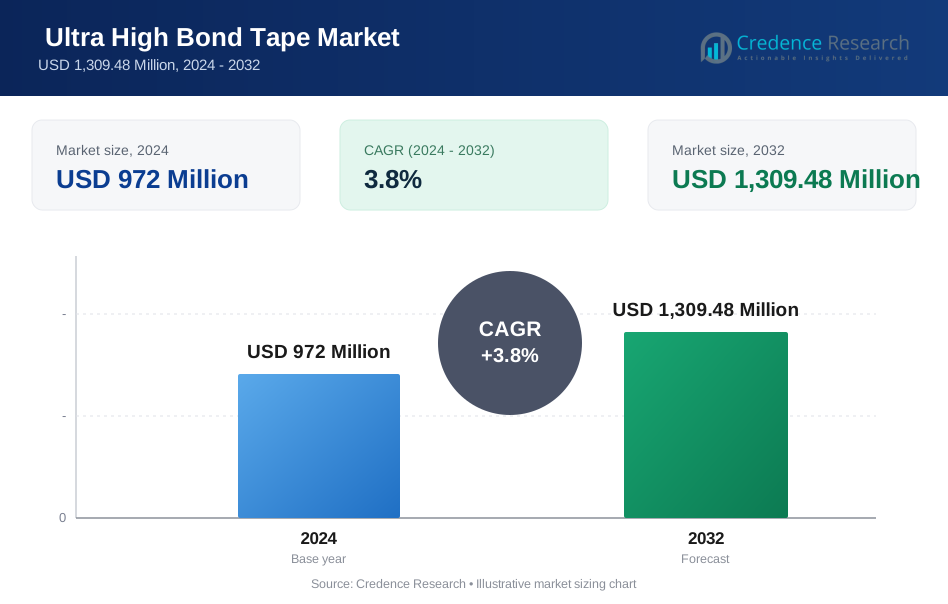
Ultra High Bond Tape Market size was valued at USD 972 Million in 2024 and is anticipated to reach USD 1,309.48 Million by 2032, at a CAGR of 3.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ultra High Bond Tape Market Size 2024 | USD 972 million |
| Ultra High Bond Tape Market, CAGR | 3.8% |
| Ultra High Bond Tape Market Size 2032 | USD 1,309.48 million |
Ultra High Bond Tape Market Insights
- Ultra High Bond Tape Market growth is driven by rising adoption in automotive lightweighting, electronics assembly, and construction applications, with Acrylic Foam Tapes leading the segment at 46.2% share in 2024 due to high bonding strength, durability, and suitability for structural bonding and precision assembly.
- Ultra High Bond Tape Market trends include increasing demand for automation-ready adhesive solutions, sustainability-focused low-VOC materials, and advanced multi-substrate adhesion technologies supporting EV components, façade engineering, and industrial equipment manufacturing.
- Ultra High Bond Tape Market analysis shows leading players expanding portfolios in acrylic foam and high-strength adhesive technologies, strengthening OEM partnerships, and focusing on product customization, while pricing efficiency, supply-chain reliability, and performance differentiation shape market positioning.
- Ultra High Bond Tape Market regional landscape is led by Asia-Pacific with 34.7% share in 2024, followed by North America at 28.6% and Europe at 24.3%, supported by electronics manufacturing growth, automotive engineering expansion, and rising industrial fabrication activities.
Ultra High Bond Tape Market Segmentation Analysis:
By Product Type:
The Ultra High Bond Tape Market by product type is led by Acrylic Foam Tapes, which accounted for 46.2% share in 2024, emerging as the dominant sub-segment due to their high bonding strength, UV resistance, and suitability for automotive trim, construction panels, and electronic device assembly. Polyethylene Foam Tapes and Polyurethane Foam Tapes collectively gained traction in lightweight sealing and shock-absorption applications, while Other Specialized Tapes supported niche industrial uses. Market growth in this segment is primarily driven by the shift toward high-performance adhesives replacing mechanical fasteners to improve durability, aesthetics, and assembly efficiency.
- For instance, 3M™ Acrylic Foam Tape 4229P features a dark gray, closed-cell 0.76 mm acrylic foam core for attaching automotive trim and components to clearcoat systems, providing stress relaxation under high load for long-lasting durability.
By Backing Material:
In terms of backing material, Double-Sided Tapes dominated the market with a 54.7% share in 2024, supported by their extensive use in structural bonding, signage, appliance assembly, and transportation interior components where strong adhesion and load-bearing capability are essential. Single-Sided Tapes, Transfer Tapes, and Reinforced Tapes served specialized bonding and reinforcement needs across electronics, industrial manufacturing, and packaging. Growth in this segment is driven by demand for lightweight bonding alternatives, reduced processing time in assembly operations, and improved bonding performance on metals, plastics, and composite substrates in high-stress environments.
- For instance, Avery Dennison FT 0031 single-coated tape provides 11.2 kV dielectric strength for electrical insulation in EV battery packs, conforming to unique geometries.
By Application:
By application, Manual Application emerged as the leading segment with a 42.9% share in 2024, driven by its widespread use in small-batch manufacturing, on-site assembly, maintenance activities, and construction finishing tasks where flexibility and operator control are required. Automated Application accounted for a rising share in high-volume production environments such as automotive and electronics assembly, while Robotic Application gained momentum in precision-bonding and repeatable industrial workflows. Growth across this segment is driven by increasing industrial automation, the need for consistent bonding quality, and the adoption of advanced adhesive technologies in smart manufacturing processes.this market.
Key Growth Drivers
Rising Adoption of Lightweight Bonding Solutions in Automotive and Transportation
The Ultra High Bond Tape Market grows significantly as automotive and transportation manufacturers replace mechanical fasteners and welding with lightweight adhesive bonding. Ultra high bond tapes reduce vehicle weight, enhance fuel efficiency, and support improved structural integrity in trims, panels, and body components. Their vibration resistance and durability make them suitable for electric vehicles, interior assemblies, and exterior cladding. OEMs increasingly prefer these tapes for faster assembly and cleaner aesthetics, driving steady demand. Regulatory pressure to lower emissions and improve energy efficiency further accelerates the adoption of high-performance bonding solutions across mobility applications.
- For instance, 3M™ Ultra High Temperature Adhesive Transfer Tape 9085 delivers high peel and shear strength at elevated temperatures, up to 540°F (280°C) short-term. It bonds automotive under-hood components requiring high processing and operating heat, as well as flexible printed circuits and electronics during solder reflow.
Expansion of Electronics and Consumer Appliances Manufacturing
Growth in electronics, smart devices, and consumer appliances strongly drives demand for ultra high bond tapes due to their precision bonding, insulation support, and heat-resistant properties. These tapes enable compact device assembly, display mounting, battery insulation, and structural reinforcement without compromising design flexibility. Manufacturers benefit from reduced assembly time and improved shock absorption in handheld electronics and wearables. The shift toward miniaturized components and high-reliability bonding in smartphones, televisions, and home appliances enhances market penetration. Increasing investments in electronics production hubs across Asia-Pacific and rising adoption of automation in assembly lines further strengthen segment growth.
- For instance, Nitto Denko tapes, such as No.380 Nomex adhesive tapes, insulate battery electrodes in wearables and secondary batteries, ensuring heat resistance during assembly. They fix modules in smart cards and bond metal to plastic chassis for compact electronics.
Construction, Facade Systems, and Industrial Assembly Advancements
The construction sector increasingly adopts ultra high bond tapes for architectural glazing, cladding panels, facade reinforcement, and structural bonding applications. These tapes deliver superior adhesion on metals, glass, and composites while supporting thermal expansion and weather resistance. Their ability to replace screws and rivets improves design aesthetics and avoids surface damage in modern building systems. Industrial assembly applications benefit from enhanced load-bearing strength and reduced maintenance downtime. Rapid infrastructure development, demand for durable fastening alternatives, and sustainability-focused construction practices accelerate uptake across commercial buildings, industrial installations, and modular fabrication environments.
Key Trends & Opportunities
Integration of Automation and Robotics in Industrial Bonding Processes
A major trend shaping the Ultra High Bond Tape Market is the increasing integration of automation and robotics in manufacturing environments. Automated tape application systems improve bonding precision, reduce material wastage, and enable high-speed production in automotive, electronics, and packaging industries. Robotics-enabled adhesive placement enhances repeatability, alignment accuracy, and structural reliability in complex assemblies. This trend creates opportunities for advanced tape products designed for automated dispensing, uniform adhesion, and compatibility with digital manufacturing workflows. As factories shift toward smart manufacturing and Industry 4.0 ecosystems, suppliers investing in automation-ready bonding solutions gain strong competitive advantage and long-term growth potential.
- For instance, Saint-Gobain's Norbond® Z3000 and Z2000 acrylic tapes are spooled with secondary release liners for robotic application in automotive exterior trim bonding, such as body side pillars. These ultra-high bond tapes facilitate flexible automation, providing durable adhesion under environmental stress without special processing equipment.
Development of High-Performance and Sustainable Adhesive Technologies
Manufacturers are increasingly focusing on high-performance, eco-friendly, and chemically advanced ultra high bond tapes to meet evolving industry standards. Opportunities arise from low-VOC formulations, recyclable backing materials, and solvent-free adhesive systems that support environmental compliance in construction, electronics, and transportation sectors. The emergence of heat-resistant, UV-stable, and multi-substrate bonding tapes enhances application versatility across harsh operating environments. Innovation in pressure-sensitive adhesives and foam-based technologies further enables stronger adhesion to composites and lightweight alloys. Growing sustainability commitments from global manufacturers create strong demand for next-generation adhesive solutions with improved durability, safety, and environmental performance.
- For instance, Avery Dennison introduced FT 77100, a double-coated nonwoven tape with pure acrylic adhesive and recycled-content glassine liner, delivering low VOC, high shear resistance, and 10-29% lower CO2 emissions for precision assembly.
Key Challenges
Fluctuating Raw Material Prices and Supply Chain Dependence
The Ultra High Bond Tape Market faces challenges due to volatility in raw material prices, particularly acrylics, foams, polymers, and specialty adhesives. Supply chain disruptions, geopolitical uncertainties, and dependency on limited chemical producers impact production costs and pricing stability. Manufacturers experience margin pressure and reduced flexibility in long-term procurement planning. Variability in transportation and logistics expenses further complicates material availability across key manufacturing regions. These fluctuations affect capacity planning and increase operational risk for market participants, especially smaller producers with limited sourcing alternatives and weaker inventory resilience.
Performance Limitations on Extreme Surface Conditions and Substrate Variability
Despite strong bonding capabilities, ultra high bond tapes encounter performance challenges on difficult substrates such as low-surface-energy plastics, textured metals, and heavily contaminated surfaces. Exposure to extreme temperatures, chemicals, and prolonged moisture can affect adhesion strength in certain applications. End-users in heavy industrial and outdoor environments require specialized tape formulations, raising development and testing costs. Incorrect surface preparation and application inconsistencies also result in bonding failures and reliability concerns. These limitations restrict broader adoption across highly demanding engineering environments and create the need for continuous material innovation and performance enhancement.
Regional Analysis
North America
North America held a strong position in the Ultra High Bond Tape Market, accounting for 28.6% market share in 2024, supported by widespread adoption in automotive lightweighting, electronics assembly, construction glazing, and industrial fabrication. The United States drives most of the regional demand due to advanced manufacturing infrastructure, high R&D investment in adhesive technologies, and early adoption of automation-based bonding solutions. Growth is further strengthened by increasing use of high-strength bonding tapes in EV production, aerospace components, and architectural facade systems. The presence of leading adhesive manufacturers and expanding industrial modernization initiatives continues to reinforce market momentum across the region.
Europe
Europe captured 24.3% market share in 2024 in the Ultra High Bond Tape Market, driven by stringent sustainability regulations, advanced automotive engineering programs, and growing applications in energy-efficient building systems. Germany, France, Italy, and the UK contribute significantly due to strong demand from transportation, electronics, and industrial equipment manufacturing. Ultra high bond tapes gain traction as replacements for welds and rivets in lightweight structures, architectural cladding, and smart assembly operations. The region also benefits from innovation in recyclable adhesive materials and high-performance foam tapes, supporting adoption in green construction projects and precision manufacturing environments across major European economies.
Asia-Pacific
Asia-Pacific emerged as the leading regional market with 34.7% market share in 2024, driven by rapid industrial expansion, large-scale electronics manufacturing, and increasing automotive production across China, Japan, South Korea, and India. The region benefits from cost-efficient manufacturing ecosystems, rising investments in consumer appliances, and strong growth in infrastructure development. Ultra high bond tapes witness high demand in display assembly, battery modules, transportation interiors, building panels, and industrial equipment fabrication. Government-led industrial automation programs and growing adoption of bonding technologies in EV manufacturing further accelerate market penetration, positioning Asia-Pacific as the fastest-growing and most influential regional hub.
Latin America
Latin America accounted for 6.5% market share in 2024 in the Ultra High Bond Tape Market, supported by expanding industrial production, automotive component manufacturing, and infrastructure modernization activities in Brazil, Mexico, and Argentina. The region increasingly adopts ultra high bond tapes in packaging equipment, construction finishing, transportation interiors, and appliance assembly to enhance durability and reduce fastening costs. Market growth is influenced by rising investments from multinational manufacturers, increasing demand for lightweight bonding materials, and gradual adoption of automated assembly processes. However, economic fluctuations and supply-chain constraints moderate the pace of large-scale technological expansion across several Latin American economies.
Middle East & Africa The Middle East & Africa region held 5.9% market share in 2024, driven by growing construction, architectural glazing, industrial maintenance, and transportation equipment manufacturing across the GCC countries, South Africa, and emerging African markets. Adoption of ultra high bond tapes increases in facade systems, metal fabrication, HVAC installations, and energy-sector infrastructure due to their strength, corrosion resistance, and design flexibility. Ongoing investments in smart infrastructure projects and industrial diversification programs further support demand. However, limited local manufacturing capacity and dependency on imported adhesive materials influence pricing dynamics, while gradual technology adoption continues to shape long-term market development in the region.
Ultra High Bond Tape Market Segmentations:
By Product Type
- Acrylic Foam Tapes
- Polyethylene Foam Tapes
- Polyurethane Foam Tapes
- Other Specialized Tapes
By Backing Material
- Single-Sided Tapes
- Double-Sided Tapes
- Transfer Tapes
- Reinforced Tapes
By Application
- Manual Application
- Automated Application
- Robotic Application
By End-User
- Automotive
- Construction
- Electronics
- Transportation
- Other Industries
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Ultra High Bond Tape Market reflects an innovation-led competitive landscape in which companies such as 3M Company, tesa SE, Nitto Denko Corporation, Avery Dennison Corporation, Henkel AG & Co. KGaA, Saint-Gobain Performance Plastics, Lohmann GmbH & Co. KG, Scapa Group plc, Intertape Polymer Group, and Adhesives Research Inc. strengthen their presence through advanced acrylic foam technologies, automation-ready bonding solutions, and sustainability-focused adhesive formulations. These players emphasize product reliability, multi-substrate adhesion, thermal resistance, and long-term durability to support automotive lightweighting, electronics assembly, architectural systems, and industrial fabrication. Strategic priorities include OEM collaborations, regional manufacturing expansion, portfolio diversification, and customized engineering support, while market positioning is influenced by pricing discipline, supply-chain resilience, distribution strength, and the ability to deliver high-performance, application-specific bonding solutions for demanding structural and precision-assembly environments.
Key Player Analysis
- Intertape Polymer Group
- Henkel AG & Co. KGaA
- Scapa Group plc
- Lohmann GmbH & Co. KG
- Adhesives Research Inc.
- Saint-Gobain Performance Plastics
- Avery Dennison Corporation
- tesa SE
- 3M Company
- Nitto Denko Corporation
Recent Developments
- In October 2025, 3M Company launched its new 3M™ VHB™ Tape Max series, an advanced high-strength acrylic foam tape line designed to deliver enhanced bonding performance and durability across automotive, construction, and industrial applications, strengthening its portfolio of ultra high bond adhesive solutions.
- In August 2024, H.B. Fuller Company acquired HS Butyl Limited, enhancing its specialty construction tapes portfolio for durable bonding in industrial applications.
- In October 2025, tesa SE introduced new professional adhesive tape products including tesa® 2in1 Professional 4460 and tesa® Silicone Precision Masking Tape 4455, expanding its product range for high-quality industrial and crafts applications.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Backing Matterial, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness rising adoption of ultra high bond tapes in automotive lightweighting and electric vehicle component assembly.
- Manufacturers will increasingly develop automation-ready adhesive tapes to support high-speed, precision-based industrial production lines.
- Demand will grow in electronics and consumer appliances as miniaturized devices require reliable structural and thermal-stable bonding solutions.
- Construction and façade engineering applications will expand as tapes replace mechanical fasteners in glazing, cladding, and modular structures.
- Sustainability initiatives will drive the development of low-VOC, recyclable, and eco-engineered adhesive materials.
- Advancements in pressure-sensitive adhesive chemistry will improve bonding performance on composites, plastics, and low-surface-energy substrates.
- Regional manufacturing integration and capacity expansion will strengthen supply stability and shorten delivery cycles.
- OEM collaborations will increase to enable application-specific product customization and engineering support.
- Growth opportunities will accelerate in robotics and automated bonding systems across smart manufacturing environments.
- Market competition will intensify as companies focus on innovation, pricing efficiency, and enhanced distribution networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ultra High Bond Tape Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ultra High Bond Tape Market projected to grow between 2024 and 2032?
Which Ultra High Bond Tape Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ultra High Bond Tape Market?
Who are the leading companies in the Ultra High Bond Tape Market?
Which region commanded the largest share of the Ultra High Bond Tape Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 972 Million → 2032: USD 1,309.48 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ultra High Bond Tape Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ultra High Bond Tape Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ultra High Bond Tape Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ultra High Bond Tape Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ultra High Bond Tape Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ultra High Bond Tape Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ultra High Bond Tape Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ultra High Bond Tape Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 972 Million → 2032: USD 1,309.48 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ultra High Bond Tape Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ultra High Bond Tape Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Ultra High Bond Tape Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Ultra High Bond Tape Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

