
Market Overview:
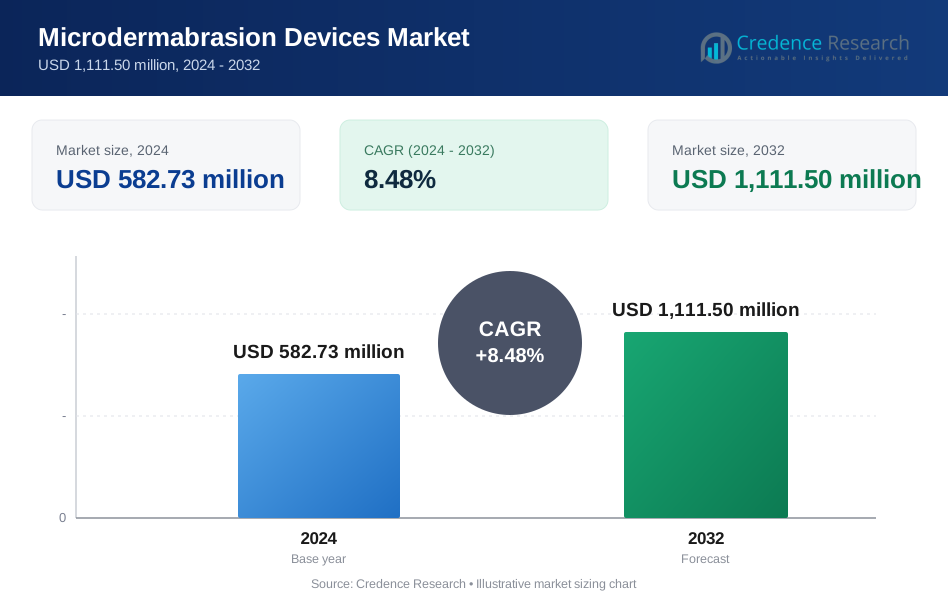
The Global Microdermabrasion Devices Market size was valued at USD 430.00 million in 2018 to USD 582.73 million in 2024 and is anticipated to reach USD 1,111.50 million by 2032, at a CAGR of 8.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2025 |
| Forecast Period | 2025-2032 |
| Microdermabrasion Devices Market Size 2024 | USD 582.73 million |
| Microdermabrasion Devices Market, CAGR | 8.48% |
| Microdermabrasion Devices Market Size 2032 | USD 1,111.50 million |
Demand rises due to growing skin care awareness worldwide. Consumers seek non-invasive cosmetic procedures. Clinics promote quick recovery and visible results. Home-use devices gain trust through improved safety features. Dermatology clinics expand aesthetic service offerings. Aging populations increase demand for skin renewal treatments. Social media boosts interest in appearance care. Technology upgrades improve suction control and precision tips. Professional endorsements raise adoption confidence. This environment supports steady market expansion.
North America leads due to strong cosmetic procedure adoption. The United States shows high clinic density and consumer spending. Europe follows with demand across Germany, France, and the UK. These countries support advanced dermatology practices. Asia-Pacific emerges as the fastest-developing region. China, South Korea, and India drive uptake through urban clinics. Rising income supports device adoption. Latin America and the Middle East show gradual growth through private clinics.

Market Insights:
- The Global Microdermabrasion Devices Market size was valued at USD 430.00 million in 2018, reached USD 582.73 million in 2024, and is projected to hit USD 1,111.50 million by 2032, growing at a CAGR of 8.48% during the forecast period.
- North America leads with about 36% share due to strong clinic density, high consumer spending, and early adoption of aesthetic devices, followed by Europe at nearly 26% driven by mature dermatology practices, and Asia Pacific at around 26% supported by rapid urban clinic expansion.
- Asia Pacific is the fastest-growing region, holding roughly 26% share, supported by rising disposable incomes, expanding beauty clinics, strong skincare awareness, and influence of K-beauty and J-beauty trends.
- Clinics & beauty centers account for approximately 55% of the market share, reflecting high procedure volumes, professional supervision, and consistent device upgrades in clinical settings.
- Home use represents about 45% share, driven by compact device availability, rising self-care trends, and growing preference for convenient at-home skin treatments.
Market Drivers:
Surging Demand for Non-Invasive Cosmetic Procedures Across Demographics
The Global Microdermabrasion Devices Market is witnessing strong traction due to rising demand for non-invasive skin treatments. Consumers increasingly seek procedures that avoid surgery and downtime. Microdermabrasion delivers visible improvements in skin tone, texture, and clarity. It fits well into routine skin maintenance schedules. Professionals promote it as an effective first-line cosmetic solution. Awareness grows across both younger and aging populations. Beauty clinics market it as a cost-effective treatment. The appeal lies in its safety and short recovery time. These factors collectively reinforce long-term demand.
- For instance, Philips reported that in clinical use of its VisaCare microdermabrasion system, 93% of women tested saw instantly smoother skin and 84% noted more radiant texture after regular use of dual‑action exfoliation technology, driving broader consumer confidence in non‑surgical options.
Expansion of Dermatology Clinics and Beauty Centers in Urban and Semi-Urban Areas
Clinic infrastructure plays a central role in supporting the Global Microdermabrasion Devices Market. Urbanization drives demand for accessible skin care facilities. Professional centers expand rapidly across Tier 1 and Tier 2 cities. These centers require certified, high-performance devices. Brand partnerships ensure consistent equipment supply. Dermatologists rely on these tools for acne scars, pigmentation, and anti-aging treatments. Clinics differentiate offerings using upgraded devices. The increased setup of chain clinics amplifies volume sales. This expansion remains a key industry growth lever.
- For instance, recent FDA clearances of multifunctional skin therapy devices such as the KALA Therapy Wand and Jmoon NouvelleSkin in 2025 which combine modalities like light therapy and microcurrent for anti-aging, have fueled the industry trend toward combination treatments.
Proliferation of Compact, Home-Use Microdermabrasion Devices Globally
The Global Microdermabrasion Devices Market benefits from consumer-friendly home-use product innovations. These devices attract users seeking clinic-like results at home. Brands now offer adjustable intensity levels for safety. Compact formats are easy to operate and maintain. Digital retail enables wide reach and brand visibility. Consumers buy based on influencer reviews and demonstration videos. Return policies and online support boost user confidence. The market sees growing repeat purchase behavior. Accessibility and convenience improve household-level adoption.
Rising Skincare Awareness and Preventive Care Culture Among Millennials and Gen Z
Preventive skincare is gaining ground among younger generations. The Global Microdermabrasion Devices Market gains support from this cultural shift. Consumers invest early in products to avoid long-term damage. Regular exfoliation is promoted as an anti-aging step. Social media amplifies trends around clear, glowing skin. Dermatologists recommend microdermabrasion for early skin renewal. Education from influencers shapes buyer behavior. Clinics create membership plans to retain loyal customers. Preventive care is becoming a core driver of device demand.
Market Trends:
Smart Device Integration and Feature Advancements for Precision Control
The Global Microdermabrasion Devices Market is evolving through smart device integration. Manufacturers embed digital screens and programmable settings. These tools offer treatment customization by skin type and concern. Clinics benefit from automation and safety enhancements. Some systems track treatment history for patient profiling. Digital precision improves session repeatability. Users gain more control, improving satisfaction. Technology upgrades continue to influence premium product offerings.
- For instance, Philips’ VisaCare dual‑action microdermabrasion device includes an Air Lift system and two interchangeable tips that have shown improved skin radiance and texture in clinical testing, with 84% of subjects reporting healthier skin look, endorsing precise control benefits.
Shift Toward Hybrid Devices That Combine Multiple Skin Therapies
Combination treatment platforms are reshaping clinic-level equipment choices. The Global Microdermabrasion Devices Market reflects growing interest in hybrid systems. Devices now merge exfoliation with serum infusion or LED therapy. This approach maximizes clinic utility and patient outcomes. Fewer sessions are needed for visible results. Clinics save on equipment costs and space. Patients value bundled treatments that address multiple concerns. This bundling trend improves return on investment for service providers.
- For instance, recent FDA approvals of multifunctional microdermabrasion devices for anti‑aging incorporate exfoliation with light‑based therapies, reflecting broader industry support for integrated approaches.
Social Media Influencers and Dermatology Professionals Driving Demand Visibility
Digital influence plays a critical role in market growth. The Global Microdermabrasion Devices Market sees growing visibility through influencers and professionals. Tutorials and testimonials build trust in non-invasive methods. Platforms like Instagram and TikTok shape user behavior. Beauty vloggers explain benefits and aftercare steps. Dermatologists share before-and-after results online. Real-time engagement reinforces product credibility. Market participants invest in social collaborations. Content-driven visibility now shapes purchase decisions.
Design Focus on Portability, Lightweight Materials, and Ergonomic Use
Ergonomics is now a core trend in device development. The Global Microdermabrasion Devices Market reflects focus on compact and portable designs. Lightweight tools help professionals reduce fatigue. Improved grips ensure better treatment control. Clinics prefer devices with flexible attachments and easy storage. Minimalist designs suit mobile beauty services. Home-use buyers value ease of handling. Visual appeal influences consumer perception. Functionality now balances with aesthetics in product development.
Market Challenges Analysis:
Concerns Around Skin Sensitivity, Safety Risks, and Operator Training Gaps
The Global Microdermabrasion Devices Market faces challenges related to safety perceptions. Users with sensitive skin fear irritation or breakouts. Incorrect pressure or technique may damage the epidermis. Inadequate staff training in clinics increases procedural inconsistencies. Home-use buyers lack guidance, leading to improper application. These concerns limit frequency of use and trust. Brands must invest in education and usage support. Clear instructions and safety certifications can help mitigate concerns. Device misuse remains a barrier to wider adoption.
Regulatory Fragmentation and Product Approval Barriers in Emerging Markets
The Global Microdermabrasion Devices Market contends with varying regulatory frameworks. Market entry requires different certifications across regions. CE marking, FDA clearance, and local standards add complexity. Approval delays hinder product rollout timelines. Smaller companies struggle with resource constraints. Exporters face duties and logistics hurdles in fragmented markets. Regional differences in compliance affect scalability. Brands must adapt strategies to meet multi-jurisdictional demands. This fragmentation slows the global pace of expansion.
Market Opportunities:
High Growth Potential in Emerging Urban Markets and Expanding Middle-Class Population
The Global Microdermabrasion Devices Market holds untapped potential in emerging cities. Rising disposable incomes fuel elective cosmetic spending. Semi-urban clinics invest in entry-level devices. Expanding middle-class populations seek professional treatments. Awareness campaigns boost trial and repeat procedures. First movers can establish strong local presence. Demand grows beyond Tier 1 cities into new growth zones.
Opportunity to Capitalize on Custom-Tailored Solutions and Skin-Specific Devices
The Global Microdermabrasion Devices Market can expand through tailored offerings. Devices optimized for specific conditions drive user satisfaction. Custom tips, adjustable suction, and precision dosing improve outcomes. Brands offering targeted solutions gain competitive edge. Clinics seek devices that cater to different skin tones and textures. Personalization supports brand loyalty and pricing premium. This approach opens niche and high-margin segments.

Market Segmentation Analysis:
By Type
The Global Microdermabrasion Devices Market is segmented into crystal and diamond devices. Crystal-based systems use fine crystals for exfoliation, often preferred in clinical settings for deeper abrasion. Diamond-tip devices offer more control, reduced mess, and lower maintenance, driving their popularity in both clinics and home use. Diamond devices are gaining traction due to precision and growing demand for portable units. Manufacturers are launching hybrid models to enhance performance. Crystal systems still hold relevance in traditional dermatology practices. Both types cater to varying user needs, price points, and operational ease.
- For instance, industry reports confirm crystal microdermabrasion remains widely used in clinical exfoliation due to reliable performance on sun damage and acne scars across dermatology settings.
By Application
Key application areas include acne & scars, photo damage, anti-aging, hyperpigmentation, stretch marks, and others. Anti-aging dominates due to strong demand for rejuvenation and wrinkle treatment. Acne and scar reduction remain core treatment areas, particularly among younger populations. Clinics frequently offer multi-session packages targeting pigmentation and sun damage. Demand for treatments addressing stretch marks is growing among postpartum and weight-loss patients. Device designs increasingly support multi-application versatility. Customizable treatment settings help target diverse skin concerns across age groups.
- For instance, industry data shows the anti‑aging segment accounted for around 33% market share in 2024 with integrated therapies combining exfoliation and targeted light treatment being adopted widely, demonstrating strong demand for wrinkle and fine line reduction.
By End-Use
Clinics & beauty centers form the leading end-user segment. Professional settings value device durability, treatment consistency, and faster results. Chain clinics and dermatology centers drive volume sales across urban zones. The home-use segment is expanding due to product miniaturization and rising skin-care awareness. Consumers seek affordable alternatives for routine exfoliation. Device brands target this segment with user-friendly, safety-certified tools. Market growth in this category supports higher device penetration in emerging regions.
Segmentation:
By Type
- Crystal
- Diamond
By Application
- Acne & Scars
- Photo Damage
- Anti-Aging
- Hyperpigmentation
- Stretch Marks
- Others
By End-Use
- Clinics & Beauty Centers
- Home Use
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Regional Analysis:
North America
The North America Microdermabrasion Devices Market size was valued at USD 158.24 million in 2018 to USD 211.88 million in 2024 and is anticipated to reach USD 403.59 million by 2032, at a CAGR of 8.5% during the forecast period. North America holds the largest share in the Global Microdermabrasion Devices Market, accounting for nearly 36.3% of the global revenue in 2024. It benefits from a mature cosmetic dermatology industry and strong consumer awareness. High disposable incomes support elective skincare procedures. Clinics invest consistently in advanced aesthetic systems. The U.S. leads due to its dense clinic network and early device adoption. Canada follows with stable market penetration. Home-use devices see steady uptake driven by e-commerce and beauty trends. Regulatory clarity and reimbursement ease help support equipment sales.
Europe
The Europe Microdermabrasion Devices Market size was valued at USD 117.39 million in 2018 to USD 153.13 million in 2024 and is anticipated to reach USD 276.49 million by 2032, at a CAGR of 7.7% during the forecast period. Europe contributes around 26.3% of global revenue in 2024. Demand stems from widespread skincare routines and emphasis on appearance-based wellness. Countries like Germany, France, and the UK lead the region’s adoption. Clinics focus on patient experience and offer microdermabrasion as part of bundled packages. Device suppliers meet high product safety and certification standards. Home-use units are gaining traction, especially in urban areas. Regulatory consistency across the EU supports cross-border trade. The region benefits from strong distribution networks and local manufacturing hubs.
Asia Pacific
The Asia Pacific Microdermabrasion Devices Market size was valued at USD 105.78 million in 2018 to USD 149.67 million in 2024 and is anticipated to reach USD 314.89 million by 2032, at a CAGR of 9.8% during the forecast period. Asia Pacific holds approximately 25.7% of the 2024 market share and is the fastest-growing region. Growth is led by rising disposable incomes and increasing interest in cosmetic dermatology. China, Japan, South Korea, and India anchor demand due to growing urban clinics. Skin-conscious younger populations drive high-volume procedures. Korean beauty trends boost non-invasive treatment adoption. Local brands emerge with affordable device offerings. Clinics in metros offer membership models, expanding regular treatments. Regulatory environments are evolving but improving gradually.
Latin America
The Latin America Microdermabrasion Devices Market size was valued at USD 26.23 million in 2018 to USD 35.19 million in 2024 and is anticipated to reach USD 62.10 million by 2032, at a CAGR of 7.4% during the forecast period. Latin America represents roughly 6% of the global market share in 2024. Brazil dominates due to its established cosmetic procedure culture. Argentina and Mexico show rising demand supported by expanding aesthetic centers. Consumers seek affordable treatments with visible results. Import dependency influences device availability and pricing. Clinics opt for versatile devices to manage cost. Home-use market remains niche but growing. Regulatory hurdles and macroeconomic instability impact consistent growth in some areas.
Middle East
The Middle East Microdermabrasion Devices Market size was valued at USD 12.43 million in 2018 to USD 15.44 million in 2024 and is anticipated to reach USD 25.57 million by 2032, at a CAGR of 6.6% during the forecast period. Middle East accounts for around 2.7% of global revenue. GCC countries, especially the UAE and Saudi Arabia, lead demand. High-income groups support clinic-level procedures. Medical tourism bolsters device investments in premium clinics. Clinics adopt U.S. and European-certified equipment. Beauty-conscious younger populations fuel demand. Cultural acceptance of cosmetic procedures is rising. Regulatory standards align with international norms, aiding global vendor entry. Retail-led growth in home-use devices remains slow.
Africa
The Africa Microdermabrasion Devices Market size was valued at USD 9.93 million in 2018 to USD 17.43 million in 2024 and is anticipated to reach USD 28.86 million by 2032, at a CAGR of 6.2% during the forecast period. Africa holds about 3% of the global share in 2024. Growth is led by South Africa, Nigeria, and Egypt. Urbanization and clinic development drive adoption. Limited awareness and affordability constrain broader reach. Import restrictions and duties affect device availability. Clinics focus on multifunctional devices for higher ROI. Emerging middle-class demand supports slow but steady market build-up. Vendors explore public-private partnerships for dermatology capacity building. Awareness campaigns and training programs can unlock future growth.
Key Player Analysis:
- Johnson & Johnson
- Skin for Life
- Altair Instruments
- Dermaglow
- Silhouet-Tone
- Lumenis Ltd.
- Koninklijke Philips N.V.
- Envy Medical, Inc.
- The HydraFacial Company
Competitive Analysis:
The Global Microdermabrasion Devices Market shows moderate competition with global and regional players. Leading companies focus on brand trust and clinical reliability. It favors firms with wide distribution and certified devices. Product quality and safety shape competitive positioning. Innovation centers on precision control and ease of use. Established brands leverage dermatologist relationships. Mid-sized players compete through pricing and compact designs. Home-use brands rely on digital sales channels. Strategic partnerships strengthen market reach. Competitive intensity remains steady across regions.
Recent Developments:
- In September 2024, Lumenis Ltd. expanded its strategic presence by partnering with a major European dermatology distributor to widen its aesthetic device portfolio reach in the region. The agreement strengthened clinic‑level availability of its microdermabrasion and energy‑based devices. It accelerates adoption across Central and Western European markets. This partnership supports brand visibility and clinician training. Clinics benefit from enhanced service support.
Report Coverage:
The research report offers an in-depth analysis based on type, application, and end-use segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for home-use devices will rise due to growing self-care and DIY skincare trends.
- Clinics will continue to invest in multifunctional and smart-enabled platforms for treatment flexibility.
- Manufacturers will introduce compact and ergonomic designs for both clinical and consumer use.
- Hybrid systems combining exfoliation with serum infusion or light therapy will gain broader adoption.
- Personalization features like adjustable suction levels and tip variations will drive device upgrades.
- E-commerce will play a major role in expanding reach and consumer accessibility in emerging markets.
- Regulatory clarity across regions will improve import-export flow and ease of device approvals.
- Skincare awareness campaigns will influence younger demographics to adopt preventive treatment routines.
- Partnerships between device makers and beauty clinics will strengthen service offerings.
- Technological innovation will drive premiumization and brand differentiation in mature markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Microdermabrasion Devices Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Microdermabrasion Devices Market projected to grow between 2025 and 2032?
Which Global Microdermabrasion Devices Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Microdermabrasion Devices Market?
Who are the leading companies in the Global Microdermabrasion Devices Market?
Which region commanded the largest share of the Global Microdermabrasion Devices Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microdermabrasion Devices Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microdermabrasion Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 582.73 million → 2032: USD 1,111.50 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microdermabrasion Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microdermabrasion Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microdermabrasion Devices Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microdermabrasion Devices Market Drivers
- 3.3 Microdermabrasion Devices Market Restraints & Challenges
- 3.4 Microdermabrasion Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microdermabrasion Devices Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microdermabrasion Devices Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microdermabrasion Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microdermabrasion Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Microdermabrasion Devices Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Microdermabrasion Devices. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microdermabrasion Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microdermabrasion Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Microdermabrasion Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microdermabrasion Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Microdermabrasion Devices
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microdermabrasion Devices Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Microdermabrasion Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microdermabrasion Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microdermabrasion Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microdermabrasion Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microdermabrasion Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microdermabrasion Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microdermabrasion Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
