
Market Overview:
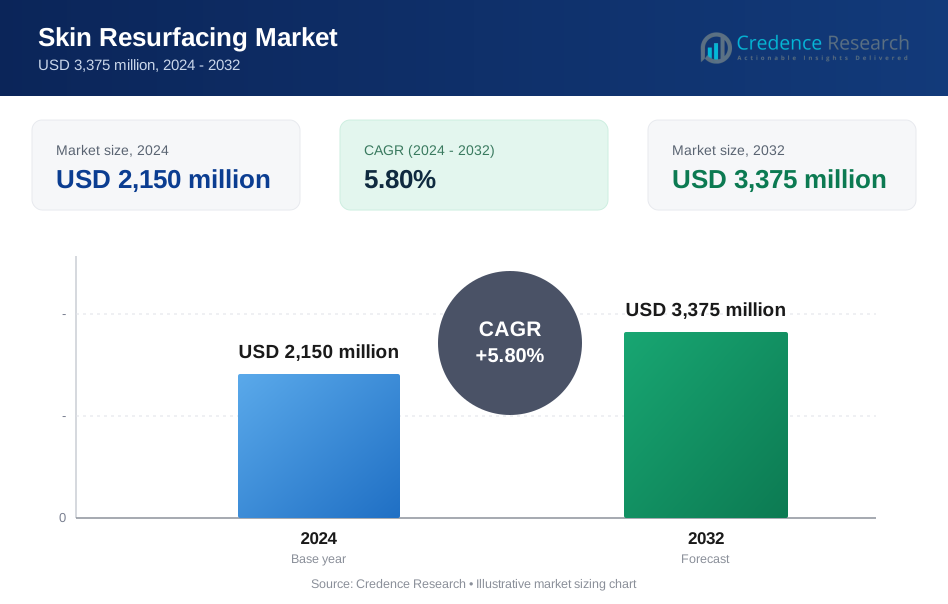
The Skin Resurfacing Market size was valued at USD 2,150 million in 2024 and is anticipated to reach USD 3,375 million by 2032, at a CAGR of 5.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Skin Resurfacing Market Size 2024 | USD 2,150 Million |
| Skin Resurfacing Market, CAGR | 5.8 % |
| Skin Resurfacing Market Size 2032 | USD 3,375 Million |
Key drivers propelling the Skin Resurfacing Market include the proliferation of advanced laser technologies, increased awareness of non-surgical aesthetic procedures, and a surge in disposable income, particularly in emerging economies. Technological innovations have improved treatment precision, safety, and recovery times, making skin resurfacing procedures more appealing to a broader demographic. The rising prevalence of skin conditions, such as hyperpigmentation and photoaging, also fuels market growth, as does the expanding pool of dermatology clinics, medspas, and specialty aesthetic centers. Social media influence and celebrity endorsements further amplify consumer interest and awareness, accelerating procedure adoption rates globally.
Regionally, North America dominates the Skin Resurfacing Market, supported by a high concentration of skilled dermatologists, strong consumer spending on cosmetic treatments, and early adoption of cutting-edge medical technologies. The United States, in particular, accounts for a major share of total procedures performed. Europe follows closely, driven by increasing demand in countries such as Germany, France, and the United Kingdom, where regulatory standards and patient safety remain high priorities. The Asia-Pacific region is expected to record the fastest growth, fueled by a rising middle class, greater acceptance of aesthetic medicine, and an expanding network of private clinics in markets such as China, Japan, South Korea, and India.
Market Insights:
- The Skin Resurfacing Market reached USD 2,150 million in 2024 and is projected to hit USD 3,375 million by 2032.
- Demand rises due to advanced laser technologies, wider awareness of non-surgical options, and higher disposable incomes.
- Technological innovations improve precision, safety, and recovery, making procedures more appealing to broader patient groups.
- Growth in skin disorders such as hyperpigmentation and photoaging increases demand for both preventive and corrective treatments.
- North America leads with a 39% share, Europe follows at 28%, and Asia-Pacific represents 21% with the fastest growth rate.
- High costs of advanced devices and procedures limit accessibility, while regulatory complexity and risk of side effects challenge market expansion.
- Social media, celebrity endorsements, and digital engagement continue to drive interest and accelerate adoption of skin resurfacing solutions worldwide.
Market Drivers:
Growing Demand for Non-Invasive Aesthetic Solutions:
The shift toward non-invasive and minimally invasive cosmetic procedures fuels the Skin Resurfacing Market. Patients increasingly favor treatments that deliver visible results with less downtime and reduced risk compared to traditional surgical methods. Modern consumers value procedures that allow them to resume daily activities quickly, which makes skin resurfacing options highly attractive. Rising concerns about aging, sun damage, and acne scars push individuals to seek solutions that offer both safety and efficacy. The availability of multiple resurfacing modalities-such as lasers, microdermabrasion, and chemical peels-broadens appeal across age groups and skin types. This trend supports continuous market growth as clinics expand offerings and promote more accessible aesthetic care.
- For instance, Stellar M22 IPL laser system offering more than 30 different skin treatments and hair removal procedures, demonstrating widespread clinical acceptance and versatility in non-invasive skin resurfacing applications.
Technological Advancements in Dermatological Devices:
Ongoing innovation in energy-based devices significantly shapes the Skin Resurfacing Market. Manufacturers introduce advanced platforms that enhance precision, improve patient comfort, and shorten recovery periods. Fractional laser systems, intense pulsed light (IPL) devices, and radiofrequency technologies set new standards for efficacy and safety. Clinics leverage these advancements to address a wide range of skin conditions with customizable treatment options. The integration of smart features, such as real-time feedback and automation, empowers practitioners and boosts patient confidence. This wave of technological progress raises industry standards and increases adoption across both established and emerging markets.
Rising Prevalence of Skin Disorders and Aging Population:
Demographic changes and lifestyle factors contribute to the increased incidence of skin disorders, directly impacting demand in the Skin Resurfacing Market. Urbanization, pollution, and heightened UV exposure accelerate the onset of conditions like hyperpigmentation, photoaging, and chronic acne. The global aging population drives further interest, with older adults seeking solutions for wrinkles, uneven tone, and texture irregularities. This dynamic strengthens the role of dermatological clinics and aesthetic centers as trusted providers of resurfacing procedures. Widespread awareness campaigns by healthcare professionals help destigmatize cosmetic treatments and educate consumers on available options.
- For Instance, burn scar management, 387 CO2 laser procedures were performed on 131 patients, with an average of 2.95 procedures per patient, underscoring the repeat utilization of laser resurfacing for complex skin conditions.
Influence of Social Media and Celebrity Endorsements:
Digital culture exerts strong influence over consumer decisions related to skin care and cosmetic procedures. The rise of beauty influencers and celebrities openly discussing treatments propels the Skin Resurfacing Market into mainstream awareness. Social media platforms amplify before-and-after results, encouraging more individuals to pursue professional resurfacing. Clinics capitalize on this exposure by sharing patient testimonials and offering virtual consultations. It becomes easier for consumers to research, compare, and select providers, which leads to a surge in procedure volumes. This environment fosters an ongoing cycle of demand and innovation within the market.
Market Trends:
Integration of Advanced Laser and Energy-Based Technologies:
The adoption of next-generation laser and energy-based devices stands out as a defining trend in the Skin Resurfacing Market. Manufacturers now deliver platforms equipped with dual and multi-wavelength capabilities, enabling practitioners to customize treatments based on individual patient profiles. Clinics increasingly incorporate fractional CO2 lasers, picosecond lasers, and non-ablative radiofrequency systems, which offer effective results with minimal downtime. Patients benefit from improved safety, reduced discomfort, and faster recovery, driving repeat visits and higher satisfaction rates. The introduction of smart software and AI-driven protocols optimizes energy delivery and enhances precision. This trend sets new standards for clinical outcomes and positions energy-based technologies as core offerings for both established and emerging providers.
- For instance, LASEROPTEK Pico® picosecond Nd:YAG laser received FDA 510(k) clearance for dermatology and plastic surgery use, delivering ultra-stable picosecond pulses for effective pigment and tattoo removal with minimal discomfort.
Expansion of Personalized and Combination Therapy Approaches:
Personalized treatment planning and the use of combination therapies are gaining traction in the Skin Resurfacing Market. Providers recognize the value of tailoring procedures to address complex skin conditions such as acne scars, photoaging, and pigmentation disorders. It is common for practitioners to combine modalities, such as pairing laser resurfacing with microneedling or topical serums, to maximize results. Patients now expect individualized care that considers skin type, sensitivity, and desired outcomes, prompting clinics to invest in diagnostic tools and training. The rise of combination protocols not only improves clinical efficacy but also helps clinics differentiate services in a crowded aesthetic landscape. This trend highlights the market’s evolution toward holistic, results-driven skin rejuvenation strategies.
- For instance, the cynosure icon 1540 fractional handpiece is fda-approved for treating stretch marks and enables patients to see noticeable improvement in the appearance of stretch marks after three sessions, with results often visible within two weeks post-procedure.
Market Challenges Analysis:
High Cost of Advanced Procedures and Equipment:
The high upfront cost of advanced skin resurfacing equipment and procedures presents a significant barrier for both providers and patients. State-of-the-art laser systems and energy-based devices require substantial capital investment, which can limit accessibility for smaller clinics and practitioners. The expense of consumables, maintenance, and operator training further increases operational costs. Many patients view skin resurfacing as an elective or cosmetic service, which leads to limited insurance coverage and out-of-pocket payment requirements. This cost sensitivity restricts procedure volumes in price-conscious markets. The Skin Resurfacing Market must address affordability concerns to sustain broad-based growth.
Risk of Adverse Effects and Regulatory Complexity:
Potential risks and complications associated with skin resurfacing procedures pose another challenge for the market. Patients with certain skin types or underlying conditions may face increased risk of side effects, such as hyperpigmentation, scarring, or infection. Providers must adhere to strict regulatory guidelines, which vary by region and technology. The need for comprehensive practitioner training and patient education adds complexity to clinical workflows. Failure to manage expectations or ensure proper technique can result in negative outcomes and damage provider reputation. The Skin Resurfacing Market faces pressure to balance innovation with stringent safety standards.
Market Opportunities:
Rising Demand in Emerging Economies and Untapped Demographics:
The Skin Resurfacing Market presents strong opportunities for growth in emerging economies where increasing urbanization and rising disposable incomes drive greater demand for aesthetic treatments. Countries in Asia-Pacific, Latin America, and the Middle East show expanding middle-class populations with a growing interest in personal appearance and skin health. Providers who invest in accessible, affordable solutions will capture new patient segments and expand procedural volumes. The youth demographic and male consumers represent untapped markets with rising interest in non-surgical cosmetic procedures. Strategic partnerships with local clinics and distributors can accelerate market entry and brand recognition in these regions.
Advancement in At-Home and Portable Skin Resurfacing Solutions:
Advancements in at-home and portable skin resurfacing technologies create new avenues for revenue generation and market penetration. Manufacturers are developing user-friendly, FDA-cleared devices that offer safe and effective results outside of clinical settings. It enables brands to target consumers who seek convenient, private, and lower-cost alternatives to in-office procedures. Telemedicine integration and digital consultation platforms further enhance access, allowing providers to guide patients remotely. The Skin Resurfacing Market stands to benefit from rising consumer trust in home-use devices and ongoing investments in product innovation and digital engagement strategies.
Market Segmentation Analysis:
By Product:
The Skin Resurfacing Market includes laser resurfacing devices, microdermabrasion systems, chemical peels, and plasma devices. Laser devices command the largest share due to their advanced technology and ability to perform both ablative and non-ablative procedures. Microdermabrasion and chemical peels remain popular for patients seeking gentle rejuvenation and lower recovery times, while plasma devices continue to gain attention for precise, targeted applications in specialized clinics.
- For instance, the Fraxel Dual 1550 and 1927 laser by Solta Medical utilizes fractional technology, delivering microscopic laser columns per square centimeter to target skin imperfections, which enables precise treatment with minimal downtime.
By Application:
Key applications focus on wrinkle reduction, scar revision, pigmentation correction, and comprehensive skin rejuvenation. The market sees sustained demand for acne scar treatment and photoaging correction, particularly from younger and middle-aged patients. Clinics frequently report rising interest in protocols that combine multiple modalities, increasing the overall value and effectiveness of each session.
- For instance, Corum Inc. demonstrated that its Palmitoyl Pentapeptide-4 cream led to a significant decrease in wrinkle depth within just 28 days, as measured by 3D imaging in clinical studies.
By Type:
Segmentation by type includes ablative, non-ablative, and fractional procedures. Ablative techniques address deep skin irregularities but require longer healing, appealing to patients seeking transformative results. Non-ablative options cater to those who prioritize minimal risk and rapid recovery, driving widespread adoption. Fractional resurfacing offers a balanced approach with effective outcomes and shorter downtime, enabling providers to tailor treatments to varied patient needs and preferences.
Segmentations:
By Product:
- Laser resurfacing devices
- Microdermabrasion systems
- Chemical peels
- Plasma-based devices
By Application:
- Wrinkle reduction
- Acne scar treatment
- Pigmentation correction
- Overall skin rejuvenation
By Type:
- Ablative resurfacing
- Non-ablative resurfacing
- Fractional resurfacing
By End-use:
- Dermatology clinics
- Medical spas
- Hospitals
- Specialty aesthetic centers
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America accounts for 39% of the Skin Resurfacing Market, making it the leading regional segment. The United States drives most of this volume, supported by a dense network of dermatology clinics, medical spas, and experienced practitioners who deliver advanced skin resurfacing procedures. High disposable incomes and a strong emphasis on personal aesthetics fuel demand for cosmetic treatments across diverse age groups. The region operates under strict regulatory oversight that ensures patient safety and consistent treatment quality. Insurance coverage for elective cosmetic services remains limited, prompting most patients to pay out-of-pocket. Canadian clinics maintain high standards of care and attract both domestic and cross-border clientele. Continuous education and certification programs for practitioners help sustain the region’s leadership and encourage ongoing innovation.
Europe:
Europe holds a 28% share of the Skin Resurfacing Market, ranking as the second-largest regional segment. Countries such as Germany, France, and the United Kingdom dominate the European landscape, benefiting from established healthcare systems and widespread access to skilled professionals. The region mandates rigorous clinical validation and licensing for providers, prioritizing patient safety and treatment efficacy. European consumers commonly seek combination therapies to address multiple skin concerns in a single visit. An aging population, especially in Western Europe, maintains steady demand for anti-aging and rejuvenation procedures. Clinics respond by offering tailored protocols and leveraging the latest technology. Cross-border medical travel within the European Union further boosts procedural volumes and market expansion.
Asia-Pacific:
Asia-Pacific represents 21% of the Skin Resurfacing Market and records the fastest growth rate among all regions. China, Japan, South Korea, and India drive this momentum, supported by rapid urbanization and rising interest in aesthetic medicine. A surge in younger patients and a growing middle class fuel demand for both preventive and corrective treatments. Regional manufacturers introduce affordable and advanced devices, improving accessibility across varied income groups. Public awareness initiatives and celebrity endorsements have reduced stigma around cosmetic procedures and broadened the market’s reach. Strategic alliances between international brands and local providers drive technological innovation and service quality. Asia-Pacific’s dynamic demographic landscape positions it as a major engine for future market growth.
Key Player Analysis:
- Syneron Medical Ltd.
- Lutronic Corporation.
- Sciton, Inc.
- Cynosure, Inc.
- Altair Instruments
- Alma Lasers GmbH
- Quanta System
- Lumenis Ltd.
- Ellman International
- Ada Clinic
Competitive Analysis:
The Skin Resurfacing Market features a competitive landscape marked by innovation, strategic partnerships, and robust product portfolios. Major players such as Cynosure, Inc., Altair Instruments, and Alma Lasers GmbH hold significant positions, driving technological advancements and expanding global reach. The market favors companies that invest in research and development, clinical validation, and training for healthcare professionals. It remains highly dynamic, with new entrants introducing specialized devices and established firms launching next-generation solutions to address evolving patient needs. Companies compete on factors such as treatment efficacy, device safety, and service support. Brand reputation and regulatory compliance influence purchasing decisions for both clinics and consumers. The Skin Resurfacing Market continues to evolve as firms leverage digital marketing, education initiatives, and partnerships to capture a larger share and strengthen their market presence.
Recent Developments:
- June 2025: Sciton, Inc. launched OMNI™, a new laser hair removal platform designed for all skin types, at the Skin CEO: Boosted event in Washington, D.C.
- In February 2025, Cynosure Lutronic signed a strategic distribution agreement with Amico Aesthetics to expand their reach in the Middle East.
- In Jan 2024, Lutronic was acquired by Hahn & Company, and in the same month, Cynosure and Lutronic entered a definitive merger agreement to form a leading global medical aesthetics technology company.
Market Concentration & Characteristics:
The Skin Resurfacing Market demonstrates moderate to high market concentration, with a few leading global companies dominating device manufacturing and technology innovation. It features a mix of established multinational corporations and specialized medical device firms that invest heavily in research and development. The market is characterized by rapid technological advancement, frequent product launches, and growing adoption of minimally invasive procedures. Strong regulatory oversight ensures product safety and efficacy, while brand reputation and clinical evidence play critical roles in purchasing decisions. It remains competitive, with players differentiating through innovation, expanded service offerings, and strategic partnerships across both developed and emerging regions.
Report Coverage:
The research report offers an in-depth analysis based on Segment 1, Segment 2, Segment 3, and Segment 3. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Market participants will adopt AI-driven diagnostic tools to optimize treatment plans and enhance precision in skin resurfacing procedures.
- Clinics will expand hybrid service models that combine in-office treatments with at-home maintenance kits for ongoing patient care.
- Manufacturers will develop modular energy-based platforms capable of multi-modality use, enhancing flexibility and value for providers.
- Regulatory bodies will tighten standards, prompting device makers to build robust clinical evidence and publish peer-reviewed data.
- Cross-border medical tourism will gain traction, driven by cost-conscious patients seeking high-quality aesthetic treatments in emerging markets.
- Brands will leverage digital marketing and teleconsultation to educate consumers and build trust in resurfacing technologies.
- Portable and handheld resurfacing devices will enter the market, targeting convenience-driven users and expanding consumer accessibility.
- Dermatology clinics will integrate patient loyalty programs and customized resurfacing packages to reinforce long-term engagement.
- Collaboration between tech-focused startups and traditional manufacturers will accelerate innovation in treatment delivery systems.
- Providers will emphasize personalized treatment outcomes by including genetic and lifestyle factors, improving efficacy and patient satisfaction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Advanced Laser Technologies
Continuous innovation in laser and energy-based devices has improved treatment precision, safety, and recovery times, making skin resurfacing procedures more effective and appealing to a wider patient base.
Growing Demand for Non-Invasive Aesthetic Solutions
Consumers increasingly prefer non-surgical and minimally invasive procedures that offer visible results with less downtime, driving clinics to expand their skin resurfacing offerings.
Rising Prevalence of Skin Disorders and Aging Population
Urbanization, pollution, and increased UV exposure have led to a higher incidence of skin conditions such as hyperpigmentation and photoaging, while an aging global population seeks corrective and preventive skin treatments.
Influence of Social Media and Celebrity Endorsements
Social media platforms and celebrity endorsements have amplified awareness and acceptance of skin resurfacing procedures, encouraging more individuals to seek professional treatments and boosting overall market demand.
Expansion of Dermatology Clinics and Medspas
The growing number of specialized clinics and medspas, particularly in emerging economies, has increased accessibility to advanced skin resurfacing technologies, supporting higher procedure volumes and market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Skin Resurfacing Market?
What factors are driving the growth of the Skin Resurfacing Market?
What are the key segments within the Skin Resurfacing Market?
What are some challenges faced by the Skin Resurfacing Market?
Who are the major players in the Skin Resurfacing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Ablative resurfacing
- 1.2.2 Non-ablative resurfacing
- 1.2.3 Fractional resurfacing
- 1.3 By End-use
- 1.3.1 Dermatology clinics
- 1.3.2 Medical spas
- 1.3.3 Hospitals
- 1.3.4 Specialty aesthetic centers
- 1.4 By Product
- 1.4.1 Laser resurfacing devices
- 1.4.2 Microdermabrasion systems
- 1.4.3 Chemical peels
- 1.4.4 Plasma-based devices
- 1.5 By Application
- 1.5.1 Wrinkle reduction
- 1.5.2 Acne scar treatment
- 1.5.3 Pigmentation correction
- 1.5.4 Overall skin rejuvenation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,150 million → 2032: USD 3,375 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Skin Resurfacing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Skin Resurfacing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Skin Resurfacing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Skin Resurfacing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Skin Resurfacing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Skin Resurfacing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Skin Resurfacing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Skin Resurfacing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,150 million → 2032: USD 3,375 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Skin Resurfacing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Ablative resurfacing
- 12.3.7.2 Non-ablative resurfacing
- 12.3.7.3 Fractional resurfacing
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dermatology clinics
- 12.4.7.2 Medical spas
- 12.4.7.3 Hospitals
- 12.4.7.4 Specialty aesthetic centers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Laser resurfacing devices
- 12.5.7.2 Microdermabrasion systems
- 12.5.7.3 Chemical peels
- 12.5.7.4 Plasma-based devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Wrinkle reduction
- 12.6.7.2 Acne scar treatment
- 12.6.7.3 Pigmentation correction
- 12.6.7.4 Overall skin rejuvenation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Skin Resurfacing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Skin Resurfacing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Skin Resurfacing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Skin Resurfacing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Syneron Medical Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lutronic Corporation
- 18.4 Sciton, Inc.
- 18.5 Cynosure, Inc.
- 18.6 Altair Instruments
- 18.7 Alma Lasers GmbH
- 18.8 Quanta System
- 18.9 Lumenis Ltd.
- 18.10 Ellman International
- 18.11 Ada Clinic
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

