
Market Overview
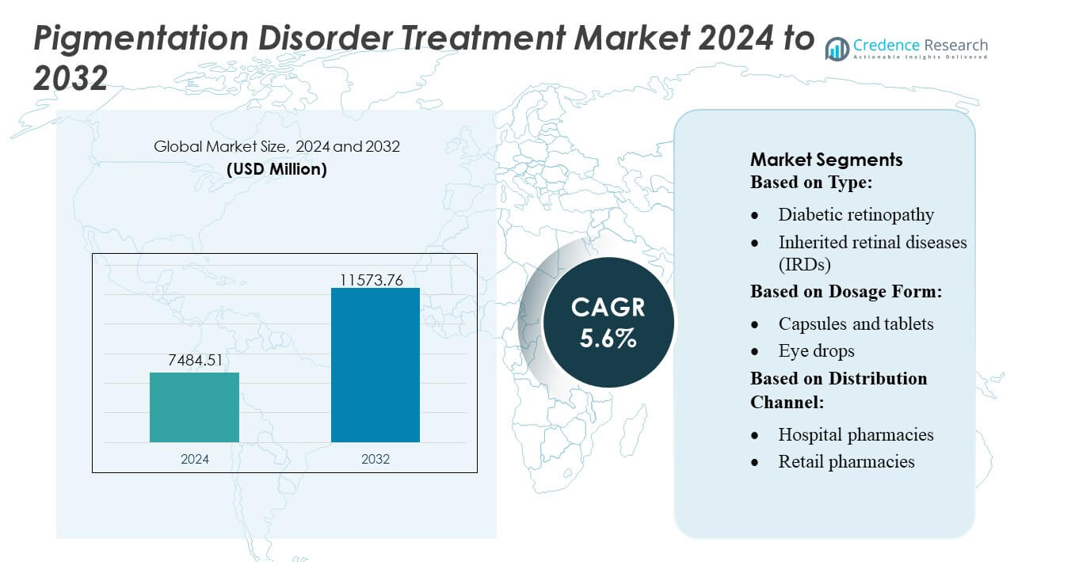
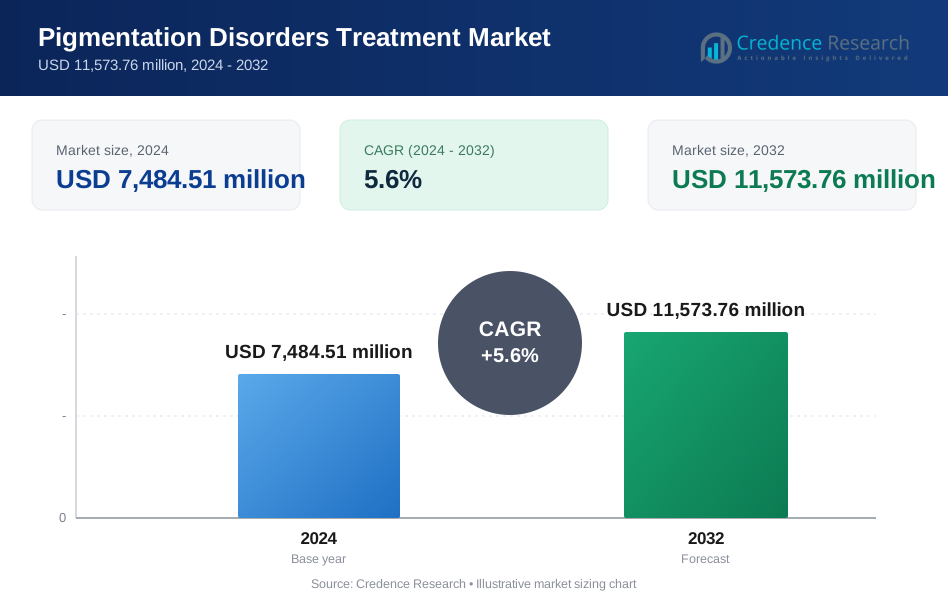
Pigmentation Disorder Treatment Market size was valued USD 7484.51 million in 2024 and is anticipated to reach USD 11573.76 million by 2032, at a CAGR of 5.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pigmentation Disorder Treatment Market Size 2024 | USD 7484.51 million |
| Pigmentation Disorder Treatment Market, CAGR | 5.6% |
| Pigmentation Disorder Treatment Market Size 2032 | USD 11573.76 million |
The Pigmentation Disorder Treatment Market is shaped by a mix of global pharmaceutical manufacturers, dermatology-focused innovators, and aesthetic device companies that continue to expand advanced topical formulations, laser platforms, and combination therapy protocols. Industry leaders strengthen competitiveness through investments in melanogenesis-inhibiting actives, biologic-based approaches, and digital skin-analysis technologies that enhance diagnostic precision and treatment personalization. The market benefits from strong innovation pipelines, expanding dermatology networks, and rising consumer preference for minimally invasive solutions. North America remains the leading region with an exact 40% market share, supported by high treatment adoption, robust clinical infrastructure, and early integration of advanced pigmentation management technologies.
Market Insights
- The Pigmentation Disorder Treatment Market was valued at USD 7,484.51 million in 2024 and is projected to reach USD 11,573.76 million by 2032, registering a CAGR of 5.6% during the forecast period.
- Market growth is driven by rising cases of melasma, vitiligo, and post-inflammatory hyperpigmentation, alongside strong adoption of advanced lasers, energy-based devices, and prescription-strength topical depigmenting agents.
- Key trends include growing demand for personalized treatment protocols, expanding use of AI-enabled skin analysis tools, and increasing adoption of combination therapies integrating topical agents with laser and phototherapy modalities.
- The competitive landscape intensifies as pharmaceutical innovators and aesthetic device manufacturers invest in melanogenesis inhibitors, biologic candidates, and nanotechnology-based formulations to improve safety and long-term results.
- North America holds an exact 40% market share, while Asia-Pacific emerges as the fastest-growing region; topical depigmenting agents remain the dominant segment supported by high consumer preference and broad OTC availability.
Market Segmentation Analysis:
By Type
The Pigmentation Disorder Treatment Market is dominated by wet macular degeneration, accounting for the largest share due to its rapid progression and the strong clinical adoption of anti-VEGF therapies that significantly reduce vision loss risk. High patient volumes, frequent dosing requirements, and continuous advancements in intravitreal biologics strengthen its lead. Dry macular degeneration follows as the second major segment, driven by rising geriatric prevalence and expanding use of antioxidant-based regimens. Growth across diabetic retinopathy and diabetic macular edema accelerates as early screening improves, while inherited retinal diseases and retinal vein occlusion represent emerging therapeutic areas supported by gene therapy innovations.
- For instance, Pfizer’s marketed anti‑VEGF aptamer Macugen (pegaptanib sodium) demonstrated in a Phase 3 study for diabetic macular edema (DME) that 37% of patients gained two lines (10 letters) of vision on the ETDRS chart at 54 weeks compared with 20% in the sham group.
By Dosage Form
Injections hold the dominant share in the Pigmentation Disorder Treatment Market, supported by their critical role in anti-VEGF delivery for wet age-related macular degeneration and diabetic retinal diseases. Their superior therapeutic precision, sustained efficacy, and physician preference for intravitreal administration reinforce market leadership. Eye drops represent a growing segment, driven by increased adoption for early-stage dry macular degeneration and supportive symptom management. Capsules, gels, ointments, and eye solutions contribute steady demand across mild-to-moderate conditions, while ongoing R&D in sustained-release injectables and implantable devices advances long-term treatment adherence.
- For instance, JNJ-81201887 (formerly “AAVCAGsCD59”), a one‑time intravitreal injection for patients with advanced dry age‑related macular degeneration (AMD) with geographic atrophy (GA), completed a Phase 1 open‑label dose‑escalation study (n = 17) in which all three doses met safety endpoints over a two‑year follow-up.
By Distribution Channel
Hospital pharmacies lead the market with the highest share, underpinned by the concentration of intravitreal injection procedures and specialist-led treatments performed in hospital settings. Their access to advanced biologics, controlled storage environments, and reimbursement alignment strengthens dominance. Retail pharmacies show consistent growth due to rising prescriptions for maintenance therapies and supportive care products. Online pharmacies gain momentum as digital fulfillment expands and chronic retinal disease patients increasingly prefer home-delivery models. Collectively, these channels support broad accessibility, but hospital pharmacies remain the primary hub for high-value ophthalmic therapeutics.
Key Growth Drivers
Rising Global Burden of Melasma, Vitiligo, and Post-Inflammatory Hyperpigmentation
The market expands as the prevalence of melasma, vitiligo, and post-inflammatory hyperpigmentation rises across diverse demographics. High UV exposure, hormonal fluctuations, pollution, and increased incidence of inflammatory skin disorders drive expanding patient volumes. Growing awareness of dermatological care and earlier diagnosis supports higher treatment adoption. Increased spending on cosmetic dermatology and the availability of advanced formulations, including targeted depigmenting agents and melanocyte-stimulating inhibitors, accelerates therapy uptake. The expanding pool of dermatology clinics and medical spas further strengthens global demand.
- For instance, AbbVie’s oral JAK inhibitor Upadacitinib (RINVOQ®) achieved T‑VASI 50 (≥ 50% reduction in total-body depigmented area) and F‑VASI 75 (≥ 75% reduction in facial depigmented area) at week 48 versus placebo in non‑segmental vitiligo (NSV) patients.
Advancements in Laser and Energy-Based Treatment Technologies
Rapid innovation in energy-based systems strengthens market growth as dermatologists increasingly adopt Q-switched lasers, picosecond lasers, fractional lasers, and IPL platforms for precise melanin targeting. These systems improve pigment clearance, minimize downtime, and reduce recurrence risk, enhancing treatment satisfaction. Manufacturers continue refining wavelength combinations, pulse-duration control, and cooling mechanisms to deliver safer outcomes for different skin types. Broader availability of portable laser devices and hybrid systems also expands procedural accessibility across developed and emerging markets, accelerating procedural volumes.
- For instance, Lundbeck is actively presenting pipeline data from mid-stage programs including the Phase II AMULET trial and a 12-month open-label extension of the Phase 1b/2a PACIFIC tria.
Growing Adoption of Combination Therapy Protocols
Demand rises as dermatologists shift toward multimodal treatment strategies integrating topical agents, chemical peels, energy-based devices, and phototherapy to achieve superior clinical outcomes. Combination protocols enhance pigment reduction, improve treatment durability, and reduce relapse rates, especially for stubborn conditions. Expanding clinical evidence supporting synergistic effects of ingredients such as hydroquinone, retinoids, azelaic acid, kojic acid, and tranexamic acid fuels adoption. The increasing development of dermatologist-supervised regimens, personalized treatment plans, and long-term maintenance therapies further boosts overall market expansion.
Key Trends & Opportunities
Shift Toward Personalized and Skin-Type-Specific Treatments
Manufacturers and dermatologists increasingly prioritize personalized therapies tailored to Fitzpatrick skin types, genetic markers, and pigment distribution patterns. The trend accelerates as AI-enabled skin analysis tools, digital imaging platforms, and mobile-based diagnostic applications support precise evaluation of pigmentation severity and treatment response. These personalized insights enable optimized dosing, targeted modality selection, and reduced side-effect profiles. Expanding R&D in genomic-based pigmentation pathways and melanin biosynthesis inhibitors presents significant long-term opportunities for individualized care models.
- For instance, Glenmark Pharmaceuticals manufactures and markets a Luliconazole 1% cream under the brand name Lulican. While clinical studies have demonstrated the efficacy of Luliconazole 1% cream for treating dermatophytosis.
Expansion of Cosmeceutical and Prescription-Strength Topical Innovations
The surge in premium cosmeceuticals and dermatologist-approved formulations creates strong growth opportunities. Companies invest heavily in stabilized actives, nano-delivery systems, peptide-based ingredients, and antioxidant complexes to improve skin penetration and efficacy. Hybrid products that blend cosmetic appeal with therapeutic performance gain traction among consumers seeking non-invasive solutions. Growing demand for clean-label, clinically tested, and multifunctional pigmentation-correcting products across retail and online channels further enlarges the addressable market for topical treatment innovations.
- For instance, Bayer AG refined its OTC antifungal offering by relaunching the Canesten range in India in May 2022. The relaunch introduced the cream in a 30 g tube and a dusting-powder in 50 g and 100 g SKUs.
Rising Demand for Non-Invasive and At-Home Treatment Devices
The market witnesses increasing popularity of at-home LED therapy tools, microcurrent devices, and handheld pigment-correcting gadgets that offer convenience and affordability. Advancements in light-based wearable patches, blue-light and red-light platforms, and photobiomodulation solutions open new revenue opportunities. Demand strengthens as consumers seek long-term maintenance solutions after clinical treatments. Manufacturers explore smartphone-connected devices and AI-guided home protocols, creating a new segment within consumer dermatology and expanding access to pigmentation management.
Key Challenges
High Relapse Rates and Limited Long-Term Treatment Durability
A major challenge involves high recurrence rates associated with melasma and post-inflammatory hyperpigmentation, even after successful treatment. Environmental triggers, UV exposure, hormonal factors, and chronic inflammation lead to inconsistent long-term outcomes. Many therapies require extended maintenance regimens, which increases patient burden and reduces compliance. Limited availability of curative treatments and variability in therapeutic response across skin types further complicate disease management. These factors constrain overall clinical success and impact patient satisfaction levels.
Risk of Adverse Effects and Treatment-Induced Complications
Safety concerns remain a critical barrier as certain topical agents and laser modalities may cause irritation, rebound hyperpigmentation, or hypopigmentation, especially in darker skin tones. Hydroquinone-associated sensitivity, procedural downtime, and potential post-treatment inflammation deter some patients from long-term use. Inadequate practitioner expertise or inappropriate device settings can exacerbate pigmentation issues. Regulatory scrutiny on depigmenting agents and uneven global access to dermatology specialists further limit the widespread adoption of advanced therapies.
Regional Analysis
North America
North America leads the Pigmentation Disorder Treatment Market with an estimated 38–40% share, driven by high awareness of dermatological health, strong adoption of advanced laser systems, and widespread availability of specialized dermatology clinics. The region benefits from robust healthcare spending, early use of innovative topical formulations, and growing patient preference for cosmetic dermatology procedures. Extensive insurance coverage for select medical treatments, coupled with expanding medical spa networks, strengthens accessibility. The rising prevalence of melasma and post-inflammatory hyperpigmentation, especially among diverse ethnic groups, continues to accelerate treatment demand across clinical and consumer channels.
Europe
Europe holds approximately 27–29% of the global market, supported by a mature dermatology infrastructure and strong demand for non-invasive treatment options. The region benefits from a high concentration of dermatologists, strict regulatory standards for topical depigmenting agents, and increasing adoption of combination therapy protocols. Growing consumer interest in premium cosmeceuticals and aesthetic procedures boosts uptake in Germany, France, Italy, and the U.K. Increased UV exposure due to climatic shifts and rising pigmentation concerns among aging populations further expand treatment volumes. Government-backed skin health initiatives also enhance early diagnosis and long-term management.
Asia-Pacific
Asia-Pacific accounts for roughly 23–25% of the market, emerging as the fastest-growing region due to high melasma prevalence and strong cultural preference for skin-brightening solutions. Expanding urbanization, pollution exposure, and higher UV index levels contribute to rising pigmentation disorders. The region experiences rapid uptake of advanced lasers, Korean aesthetic innovations, and prescription-strength depigmenting topicals. Growing middle-class spending and the proliferation of dermatology chains in China, India, Japan, and South Korea strengthen market penetration. Increasing digital skin-diagnosis tools and e-commerce-driven sales of cosmeceuticals further accelerate market growth.
Latin America
Latin America captures about 7–8% of global share, driven by rising cases of melasma stemming from high UV exposure and hormonal influences. Brazil and Mexico lead market demand due to strong aesthetic procedure adoption and growing availability of dermatology clinics specializing in pigment correction. The region benefits from expanding medical tourism and increasing consumer interest in affordable laser treatments and combination protocols. However, uneven access to advanced dermatology technologies and limited reimbursement frameworks affect penetration rates. Growing awareness of skin health and rising adoption of dermatologist-supervised regimens support steady regional expansion.
Middle East & Africa
The Middle East & Africa region holds approximately 5–6% market share, supported by high pigmentation concerns associated with intense sun exposure and higher Fitzpatrick skin types. Demand grows as consumers increasingly adopt laser-based procedures, topical depigmenting agents, and maintenance therapies tailored for darker skin tones. The UAE, Saudi Arabia, and South Africa represent key growth centers due to expanding aesthetic clinics and rising medical tourism. However, limited dermatologist availability in several African countries and high treatment costs constrain broader adoption. Growing investments in skincare retail and advanced dermatology services gradually strengthen market presence.
Market Segmentations:
By Type:
- Diabetic retinopathy
- Inherited retinal diseases (IRDs)
By Dosage Form:
- Capsules and tablets
- Eye drops
By Distribution Channel:
- Hospital pharmacies
- Retail pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Pigmentation Disorder Treatment Market features an increasingly competitive environment shaped by leading pharmaceutical and dermatology-focused innovators such as Sanofi, Pfizer Inc., AstraZeneca, GSK plc, Johnson & Johnson Services, Inc., AbbVie Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, and H. Lundbeck A/S. the Pigmentation Disorder Treatment Market continues to evolve as pharmaceutical innovators, dermatology specialists, and aesthetic technology manufacturers intensify efforts to deliver more effective and longer-lasting solutions. Companies focus on expanding portfolios across topical depigmenting agents, biologics, laser platforms, and combination therapy protocols that target multiple pigmentation pathways. Advancements in picosecond lasers, nanotechnology-based delivery systems, and clinically validated cosmeceuticals strengthen differentiation in a crowded market. Strategic collaborations with dermatology clinics, medical spas, and digital skin-analysis platforms enhance patient access and treatment personalization. Growing emphasis on safety, relapse prevention, and skin-type-specific formulations continues to shape competitive strategies and accelerate product innovation across global markets.
Key Player Analysis
- Sanofi
- Pfizer Inc.
- AstraZeneca
- GSK plc
- Johnson & Johnson Services, Inc.
- AbbVie Inc.
- Merck & Co., Inc.
- Bristol-Myers Squibb Company
- Eli Lilly and Company
- Lundbeck A/S
Recent Developments
- In February 2025, Bayer announced that Health Canada has approved Eylea HD (aflibercept injection, 8mg), a pre-filled syringe with OcuClick integrated dosing system for the treatment of nAMD and diabetic macular oedema (DME) in Canada.
- In January 2025, Johnson & Johnson announced the U.S. Food and Drug Administration (FDA) approval of a supplemental New Drug Application (sNDA) for SPRAVATO® (esketamine), making it the first and only monotherapy (standalone treatment) for adults with treatment-resistant depression in the U.S.
- In December 2024, the FDA approved Eli Lilly’s Zepbound (tirzepatide) for moderate to severe obstructive sleep apnea in adults with obesity, marking a significant advancement in treatment options in the U.S.
- In July 2024, Genentech, a part of the Roche Group, gained FDA clearance for the Vabysmo (faricimab-svoa) 6.0 mg single dose prefilled syringe (PFS) for wet AMD, DME and RVO associated macular edema. This action enhanced convenience in treatment and broadened access, reaffirming Roche's dedication towards innovation in ocular disease therapeutic development
Report Coverage
The research report offers an in-depth analysis based on Type, Dosage Form, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see rising adoption of personalized pigmentation therapies designed around skin-type classification and digital diagnostic insights.
- Demand for advanced laser and energy-based systems will grow as clinics prioritize faster recovery and more predictable outcomes.
- Topical innovations will expand with nano-formulations, stabilized actives, and multifunctional ingredients offering stronger efficacy.
- Combination therapy protocols will become standard as clinicians integrate topical agents, devices, and maintenance regimens.
- AI-driven skin imaging and remote monitoring tools will enhance treatment planning and progress tracking.
- Consumer interest in premium cosmeceuticals and medically backed skincare will strengthen retail and online sales channels.
- Growth in aesthetic clinics and medical spas across emerging markets will accelerate global penetration.
- Development of biologics targeting inflammatory and autoimmune pigmentation pathways will broaden therapeutic options.
- At-home light therapy and device-based maintenance solutions will gain traction among long-term users.
- Regulatory focus on ingredient safety and clinical validation will push manufacturers toward higher-quality, evidence-based formulations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Pigmentation Disorders
Increasing cases of melasma, vitiligo, and post-inflammatory hyperpigmentation across diverse populations are expanding the patient pool and driving demand for effective treatment options.
Advancements in Laser and Energy-Based Technologies
Rapid innovation in Q-switched, picosecond, and fractional lasers, as well as IPL platforms, is enabling more precise, safer, and faster pigment correction, boosting adoption among dermatology clinics and consumers.
Growth in Personalized and Combination Therapy Protocols
The shift toward individualized treatment plans, integrating topical agents, energy-based devices, and phototherapy, is improving clinical outcomes and reducing relapse rates, fueling market expansion.
Expansion of Cosmeceutical and Prescription-Strength Topicals
Investment in stabilized actives, nano-delivery systems, and multifunctional ingredients is leading to more effective and safer topical formulations, increasing consumer and clinician preference for non-invasive solutions.
Increasing Access to Dermatology Services and Digital Skin Analysis
The proliferation of dermatology clinics, medical spas, and AI-enabled skin analysis tools is enhancing early diagnosis, treatment personalization, and patient engagement, supporting higher treatment uptake globally.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Pigmentation Disorders Treatment market?
At what Compound Annual Growth Rate is the Pigmentation Disorder Treatment Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Pigmentation Disorders Treatment market?
What are the key segments within the Pigmentation Disorders Treatment market?
What are some challenges faced by the Pigmentation Disorders Treatment market?
Who are the major players in the Pigmentation Disorders Treatment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Melasma
- 1.2.2 Vitiligo
- 1.2.3 Post-Inflammatory Hyperpigmentation
- 1.2.4 Diabetic Retinopathy
- 1.2.5 Inherited Retinal Diseases
- 1.3 By Dosage Form
- 1.3.1 Topical Agents (Creams, Gels, Ointments)
- 1.3.2 Injections
- 1.3.3 Eye Drops
- 1.3.4 Capsules and Tablets
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,484.51 million → 2032: USD 11,573.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pigmentation Disorders Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pigmentation Disorders Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pigmentation Disorders Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pigmentation Disorders Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pigmentation Disorders Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pigmentation Disorders Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pigmentation Disorders Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pigmentation Disorders Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,484.51 million → 2032: USD 11,573.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pigmentation Disorders Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Melasma
- 12.3.7.2 Vitiligo
- 12.3.7.3 Post-Inflammatory Hyperpigmentation
- 12.3.7.4 Diabetic Retinopathy
- 12.3.7.5 Inherited Retinal Diseases
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Dosage Form - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Topical Agents (Creams, Gels, Ointments)
- 12.4.7.2 Injections
- 12.4.7.3 Eye Drops
- 12.4.7.4 Capsules and Tablets
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pigmentation Disorders Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Pigmentation Disorders Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Pigmentation Disorders Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Sanofi
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer Inc.
- 17.4 AstraZeneca
- 17.5 GSK plc
- 17.6 Johnson & Johnson Services, Inc.
- 17.7 AbbVie Inc.
- 17.8 Merck & Co., Inc.
- 17.9 Bristol-Myers Squibb Company
- 17.10 Eli Lilly and Company
- 17.11 Lundbeck A/S
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

