
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
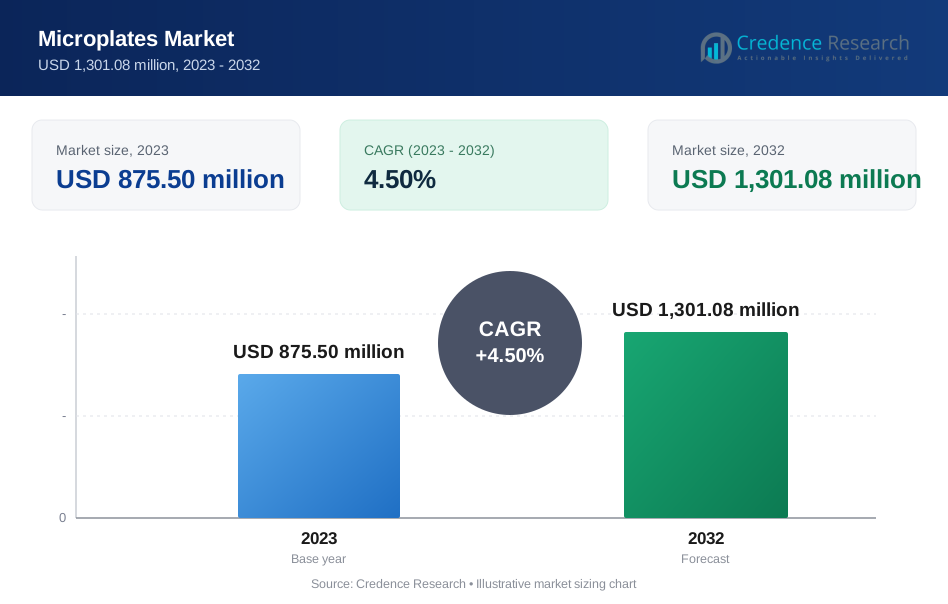
| Global Microplates Market Size 2023 | USD 875.50 million |
| Global Microplates Market, CAGR | 4.50% |
| Global Microplates Market Size 2032 | USD 1,301.08 million |
Market Overview
The Global Microplates Market is projected to grow from USD 875.50 million in 2023 to an estimated USD 1,301.08 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.50% from 2024 to 2032. This growth is driven by the increasing adoption of microplates in drug discovery, diagnostics, and research laboratories due to their efficiency in handling large sample volumes and improving throughput.
Market drivers include the rising demand for personalized medicine, which necessitates extensive research and development activities, thereby boosting the need for microplates. Additionally, the growing prevalence of chronic diseases and the subsequent increase in diagnostic tests are fueling market growth. Trends in the market also point to the increasing use of microplates in genomics and proteomics research, which is expected to further propel market demand.
Geographically, North America holds a dominant share of the global microplates market, driven by a strong presence of pharmaceutical companies and research institutions. Europe follows closely, supported by significant investments in life sciences research. The Asia-Pacific region is anticipated to witness the fastest growth during the forecast period, attributed to increasing healthcare investments and the expansion of research facilities in countries like China and India. Key players in the market include Thermo Fisher Scientific, Corning Incorporated, PerkinElmer, Inc., and Greiner Bio-One International GmbH.
Market Drivers
Rising Demand for High-Throughput Screening (HTS) in Drug Discovery and Development
The global microplates market is experiencing significant growth driven by the increasing demand for high-throughput screening in drug discovery and development. HTS has become a crucial technology in pharmaceutical research, enabling rapid testing of numerous compounds for potential drug candidates. Microplates serve as essential platforms for conducting multiple simultaneous assays, both biochemical and cell-based. For instance, a survey conducted by the Pharmaceutical Research and Manufacturers of America (PhRMA) revealed that member companies invested over $91 billion in research and development in 2020, with a substantial portion dedicated to HTS technologies. The rising prevalence of chronic diseases has further intensified the need for novel therapeutic agents, propelling the demand for microplates. Advancements in microplate technology, such as the development of higher-density plates, have enhanced HTS efficiency and accuracy. Additionally, the integration of automation in HTS processes has boosted microplate adoption, as evidenced by data from the Society for Laboratory Automation and Screening (SLAS) showing a 30% increase in automated HTS systems usage over the past five years.
Growing Adoption of Personalized Medicine
The increasing adoption of personalized medicine is a key driver of the global microplates market. This tailored approach to healthcare requires extensive research and development of targeted therapies, leading to a surge in demand for microplates in research laboratories. According to a report by the Personalized Medicine Coalition, the number of personalized medicines in development has more than doubled since 2016, with over 25% of new molecular entities approved by the FDA in 2019 classified as personalized medicines. Microplates play a crucial role in personalized medicine research, particularly in genomics, proteomics, and cell biology, where large-scale screening of genetic and molecular data is essential. The National Institutes of Health (NIH) has reported a significant increase in funding for precision medicine initiatives, with annual investments exceeding $1 billion in recent years. This trend has led to an increased focus on companion diagnostics, which often involve the use of microplates for testing and validation. As healthcare providers and researchers continue to explore personalized treatment options, the demand for microplates is expected to rise substantially.
Increasing Prevalence of Chronic Diseases and the Need for Diagnostic Testing
The global burden of chronic diseases is driving the growth of the microplates market through increased demand for diagnostic testing. According to the World Health Organization (WHO), chronic diseases are responsible for 71% of all deaths globally, emphasizing the critical need for early detection and monitoring. Microplates are essential in diagnostic laboratories for various assays, including ELISA, PCR, and fluorescence assays. The Centers for Disease Control and Prevention (CDC) reports that over 7 million laboratory tests are performed daily in the United States alone, with a significant portion utilizing microplate-based technologies. The COVID-19 pandemic has further highlighted the importance of diagnostic testing, with microplates being extensively used in serological and molecular assays for virus detection. Data from the American Clinical Laboratory Association shows that U.S. laboratories were performing over 2 million COVID-19 tests per day at the peak of the pandemic, many of which utilized microplate-based methods. This increased emphasis on diagnostic testing is expected to continue driving the microplates market growth as the healthcare industry focuses on early and accurate diagnosis of various conditions.
Technological Advancements in Microplate Design and Functionality
Technological advancements in microplate design and functionality are playing a pivotal role in driving the global microplates market. Innovations such as the development of automated microplate handling systems, microplate readers, and advanced coatings have significantly improved the performance and versatility of microplates. Automated microplate handlers, for instance, allow for the seamless integration of microplates into automated workflows, reducing the risk of human error and increasing throughput. Advanced microplate readers equipped with multiple detection modes, such as absorbance, fluorescence, and luminescence, have enhanced the capability of microplates in various applications, including drug discovery, genomics, and diagnostics. Furthermore, the introduction of specialized coatings, such as hydrophobic and hydrophilic coatings, has expanded the range of assays that can be performed on microplates, improving assay sensitivity and specificity. These technological advancements are not only enhancing the efficiency of research and diagnostic processes but also driving the adoption of microplates across various industries, including pharmaceuticals, biotechnology, and clinical diagnostics. As manufacturers continue to innovate and develop next-generation microplates with improved features, the market is expected to witness sustained growth.
Market Trends
Advancements in Microplate Technology and Automation Integration
One of the most prominent trends in the global microplates market is the continuous advancement in microplate technology, coupled with the integration of automation in laboratory workflows. Surveys of laboratory managers indicate a strong preference for higher-density microplates, with 384-well and 1536-well formats gaining popularity due to their ability to increase assay throughput and improve reagent efficiency. For instance, data from a recent industry report shows that high-density microplates are experiencing rapid adoption in drug discovery applications. The trend towards automation is equally significant, with many laboratories reporting increased investment in automated microplate handlers, dispensers, and washers. Government surveys of research institutions highlight the growing use of integrated microplate systems that combine multiple detection modes. This shift towards automation is driven by the need to enhance productivity and reduce manual errors. Data from equipment manufacturers reveals a substantial increase in sales of automated microplate systems over the past few years, reflecting the industry's move towards more efficient and streamlined laboratory processes.
Growing Focus on Eco-Friendly and Sustainable Microplate Materials
Another significant trend in the global microplates market is the increasing emphasis on eco-friendly and sustainable materials. Industry surveys show a rising awareness among laboratory professionals about the environmental impact of plastic microplates. For instance, a recent poll of life science researchers indicated that a majority are actively seeking alternatives to traditional plastic microplates. In response, several leading manufacturers have reported increased research and development efforts focused on biodegradable and recyclable microplate materials. Government environmental agencies have noted a growing number of initiatives aimed at reducing laboratory plastic waste, with microplates being a key target. Data from material suppliers shows an uptick in the production of plant-based polymers suitable for microplate manufacturing. Additionally, market research indicates a rising demand for reusable microplates, with several institutions reporting significant reductions in waste after implementing reusable options. This trend aligns with broader sustainability goals in the scientific community, as evidenced by the increasing number of publications and conference presentations focused on green laboratory practices.
Market Restraints and Challenges
High Costs and Limited Accessibility of Advanced Microplates
One of the primary restraints in the global microplates market is the high cost associated with advanced microplates and their related technologies. While technological advancements have significantly enhanced the capabilities of microplates, these innovations often come at a premium price. High-density microplates, such as 384-well and 1536-well formats, along with automated microplate handling systems, require substantial financial investment. This can be a significant barrier for smaller research laboratories, academic institutions, and healthcare facilities with limited budgets. For instance, a survey conducted by a leading life sciences research organization found that cost was the primary factor limiting the adoption of advanced microplate technologies in academic settings. Moreover, the cost of maintenance and operation of automated systems adds to the financial burden, making it challenging for smaller entities to adopt these advanced technologies. The limited accessibility to these high-cost products in developing regions further exacerbates this challenge, as many laboratories in these areas may not have the necessary resources to invest in such technologies. Government data from emerging economies indicates a significant disparity in the availability of advanced microplate technologies between urban research centers and rural laboratories.
Complexity of Assay Standardization and Validation
Another significant challenge in the global microplates market is the complexity associated with the standardization and validation of assays conducted using microplates. As microplate technology continues to evolve, the diversity of available formats, coatings, and detection methods has increased, leading to challenges in ensuring consistency and reproducibility across different laboratories and applications. A recent industry report highlighted that over half of the surveyed laboratories reported difficulties in standardizing microplate-based assays across different research teams. The lack of standardized protocols for microplate-based assays can result in variability in assay outcomes, making it difficult to compare results across different studies or laboratories. This challenge is particularly pronounced in high-throughput screening and diagnostic applications, where the accuracy and reliability of results are critical. For example, a government-sponsored study in the pharmaceutical sector revealed that inconsistencies in microplate assay results were a major factor in delays during drug discovery processes. Additionally, the need for specialized expertise to optimize and validate microplate assays can limit their adoption, particularly in settings with limited technical resources. A survey of small to medium-sized biotech companies indicated that a shortage of skilled personnel was a key barrier to implementing advanced microplate technologies.
Market Segmentation Analysis
By Type
The global microplates market is segmented by type into 96-well, 384-well, and 1536-well formats. The 96-well microplates dominate the market due to their widespread use in various applications, particularly in small to medium-scale laboratories. The 384-well and 1536-well microplates are gaining traction, especially in high-throughput screening (HTS) applications, as they allow for higher assay throughput and greater efficiency in drug discovery processes. The shift towards more complex and larger assays is driving the demand for these high-density microplates. For instance, a survey conducted by the National Institutes of Health (NIH) found that over 70% of academic research laboratories primarily use 96-well microplates for their experiments, while pharmaceutical companies reported a growing adoption of 384-well and 1536-well formats for drug screening purposes. Additionally, data from the Biotechnology Innovation Organization (BIO) indicates that the use of high-density microplates in drug discovery has led to a 30% increase in the number of compounds screened per day in large pharmaceutical companies.
By Application
The market is further segmented by application, including cell culture, screening and UV/VIS spectroscopy, immunology, storage, and others. Screening and UV/VIS spectroscopy hold a significant share in the market due to their critical role in pharmaceutical research and diagnostic testing. Cell culture applications are also prominent, driven by the increasing focus on personalized medicine and stem cell research. The immunology segment is expected to grow, supported by the rising demand for diagnostic tests and vaccine development. Storage applications, particularly in biobanking and sample management, are also contributing to market growth. For instance, a report by the American Society for Clinical Pathology (ASCP) revealed that the use of microplates in clinical diagnostics has increased by 25% over the past five years, with immunology-based tests showing the highest growth rate. Furthermore, data from the International Society for Biological and Environmental Repositories (ISBER) indicates that the adoption of microplates for biospecimen storage in biobanks has doubled in the last decade, highlighting the growing importance of microplates in sample management and preservation.
Segments
Based on type
- 96 Well
- 384 Well
- 1536 Well
Based on application
- Cell Culture
- Screening and UV/VIS Spectroscopy
- Immunology
- Storage
- Others
Based on end user
- Pharma & Biotech Companies
- Academic & Research
- CROs
- Others
Based on material
- Polystyrene
- Polypropylene
- Polycarbonate
- Cyclo-olefins
- Others
Based on pigmentation
- Black
- White
- Clear
Based on region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
Europe (28%):
Europe accounts for about 28% of the global microplates market. The region's market is driven by strong governmental support for research and development, particularly in countries like Germany, the United Kingdom, and France. For instance, according to Eurostat, R&D expenditure in the EU reached €311 billion in 2020, with Germany alone accounting for 31% of this total. Europe is a hub for biotechnology and pharmaceutical industries, with a focus on innovation and advanced healthcare solutions. The increasing adoption of microplate technology in genomics, proteomics, and diagnostics, coupled with stringent regulatory standards, supports the market's expansion in this region. Additionally, Europe's aging population and the corresponding rise in chronic disease prevalence are fueling the demand for diagnostic testing, thereby increasing the use of microplates
Asia pacific (25%):
The Asia-Pacific region is emerging as the fastest-growing market, with a market share of approximately 25%. This rapid growth is driven by increasing healthcare investments, expanding pharmaceutical and biotechnology sectors, and the rising demand for advanced diagnostic tools. For instance, countries like China, Japan, and India are at the forefront of this growth, with significant investments in research and development, especially in the areas of personalized medicine and high-throughput screening. The region's large and growing population, coupled with an increasing burden of chronic diseases, is also contributing to the heightened demand for microplates. Additionally, the growing number of contract research organizations (CROs) and the expansion of research facilities are further propelling market growth in Asia-Pacific.
Key players
- Greiner Bio-One International GmbH
- Corning Incorporated
- Thermo Fisher Scientific
- Eppendorf AG
- PerkinElmer Inc.
- Becton, Dickinson and Company
- QIAGEN N.V.
- VWR (Avantor)
- SPL Life Sciences
Competitive Analysis
The global microplates market is characterized by intense competition among key players, each offering a diverse range of products tailored to various applications in research, diagnostics, and drug discovery. Greiner Bio-One International GmbH, Corning Incorporated, and Thermo Fisher Scientific are market leaders, renowned for their innovative microplate technologies and extensive global distribution networks. Eppendorf AG and PerkinElmer Inc. also hold significant market positions, leveraging their strong R&D capabilities and comprehensive product portfolios. Becton, Dickinson and Company and QIAGEN N.V. contribute to the market's competitive landscape with their focus on high-quality products and integration with automated systems. VWR (Avantor) and SPL Life Sciences are gaining traction by offering cost-effective solutions and expanding their presence in emerging markets. The market's competitive dynamics are driven by continuous innovation, strategic partnerships, and a focus on meeting the evolving needs of end-users across various sectors.
Recent Developments
- In April 2024, Thermo Fisher Scientific reported its first quarter 2024 financial results, highlighting strong commercial execution and operational discipline. While no specific microplate products were mentioned, the company continues to focus on innovation and growth in life sciences.
- In January 2024, Eppendorf launched several new products, including the epMotion automated liquid handling system with a new design. This system is compatible with microplates and enhances laboratory workflows.
- In August 2024, BD reported its third quarter fiscal 2024 financial results. The company announced a definitive agreement to acquire Edwards Lifesciences' Critical Care Product Group for $4.2 billion, which may impact their product portfolio including microplateInrelated offerings.
- In April 2024, QIAGEN strengthened its portfolio for cancer research, showcasing latest product launches at the AACR Annual Meeting 2024. While specific microplate products were not mentioned, this development may include innovations related to microplate technologies.
- In March 2022, Greiner BioInOne founded Tracie Healthcare Solutions, a startInup focused on digitizing the entire preanalytical sample process, which may have implications for microplateInbased workflows.
Market Concentration and Characteristics
The Global Microplates Market is moderately concentrated, with a few key players dominating the market, including Greiner BioInOne International GmbH, Corning Incorporated, and Thermo Fisher Scientific. These companies hold significant market shares due to their strong brand recognition, extensive product portfolios, and global distribution networks. The market is characterized by high barriers to entry, driven by the need for advanced manufacturing capabilities, significant R&D investment, and compliance with stringent regulatory standards. Additionally, the market exhibits a strong focus on innovation, with companies continuously developing new technologies and applications to meet the evolving demands of the pharmaceutical, biotechnology, and diagnostics sectors. Despite the presence of leading players, the market also includes smaller firms and regional players that compete by offering specialized or costIneffective solutions, contributing to a dynamic competitive landscape.
Report Coverage
The research report offers an inIndepth analysis based on type, application, end user, material, pigmentation and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for microplates is expected to rise as pharmaceutical companies increasingly rely on highInthroughput screening (HTS) in drug discovery, driving market growth
- With the growing emphasis on personalized medicine, microplates will play a crucial role in genomics and proteomics research, further expanding their application scope.
- Ongoing innovations, such as automation integration and higher well densities, will enhance the efficiency and versatility of microplates, fueling market expansion.
- The rising prevalence of chronic diseases will lead to greater adoption of microplates in diagnostic laboratories, particularly for immunoassays and molecular diagnostics.
- AsiaInPacific and Latin America are expected to witness significant growth due to increasing healthcare investments and expanding research capabilities in these regions.
- As sustainability becomes a priority, manufacturers will increasingly develop microplates using biodegradable and recyclable materials, catering to the growing demand for ecoInfriendly solutions.
- The academic and research sectors will continue to adopt microplates for various applications, driven by increased funding for life sciences research and education.
- The integration of AI with microplateInbased assays is anticipated to improve data analysis and decisionInmaking, enhancing the overall efficiency of research processes.
- Strategic partnerships and collaborations among leading companies will drive innovation and expand the global reach of microplates, strengthening market dynamics.
- Microplates are expected to find new applications in fields such as environmental testing and food safety, broadening their market potential and fostering longInterm growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Global Microplates Market?
What is the major growth driving factors for global Microplate market?
Which regions dominate the Global Microplates Market?
Who are the leading players in the Global Microplates Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microplates Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microplates Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 875.50 million → 2032: USD 1,301.08 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microplates Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microplates Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microplates Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microplates Market Drivers
- 3.3 Microplates Market Restraints & Challenges
- 3.4 Microplates Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microplates Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microplates Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microplates category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microplates Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Microplates Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Microplates market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microplates Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microplates Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Microplates Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microplates (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Microplates Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microplates Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Microplates Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microplates Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microplates Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microplates Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microplates Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microplates Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microplates Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
