
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Next Generation Packaging Technology Market Size 2024 | USD 12,852.9 million |
| Next Generation Packaging Technology Market, CAGR | 6.23% |
| Next Generation Packaging Technology Market Size 2032 | USD 20,843.88 million |
Market Overview:
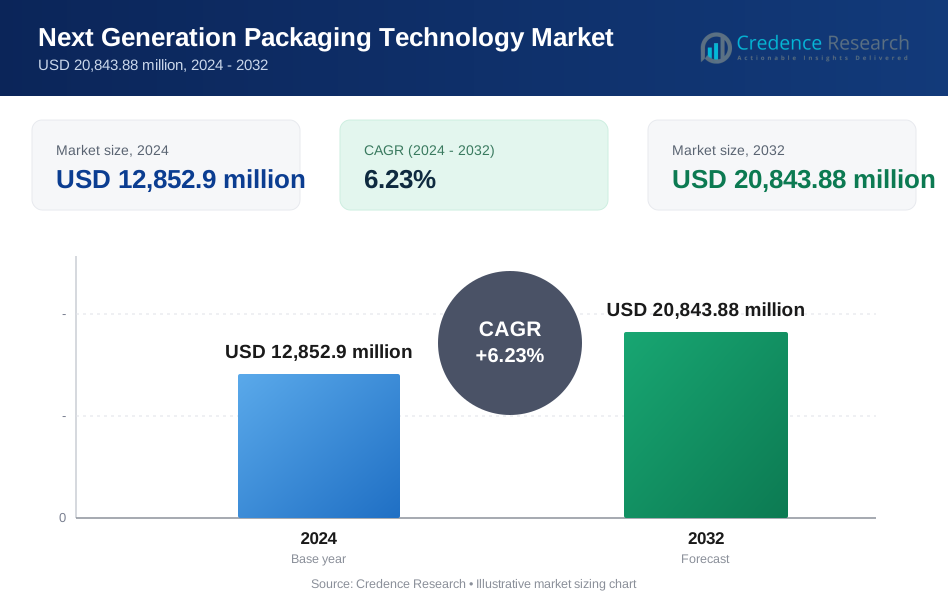
The Next Generation Packaging Technology Market size was valued at USD 12,852.9 million in 2024 and is anticipated to reach USD 20,843.88 million by 2032, at a CAGR of 6.23% during the forecast period (2024-2032).
This growth is driven by the increasing demand for innovative packaging solutions that go beyond basic functions such as containment, protection, and labeling. The market's expansion is further supported by the rising adoption of smart packaging technologies and sustainable materials. Several factors are driving the growth of the Next Generation Packaging Technology Market. The growing consumer demand for sustainable packaging solutions is a significant driver, as eco-conscious consumers seek biodegradable and recyclable materials. Advancements in smart technology, such as the integration of Internet of Things (IoT) in packaging, have enabled features like real-time monitoring, enhanced traceability, and interactive customer engagement. Additionally, stringent regulatory standards promoting the use of eco-friendly materials and the rising adoption of e-commerce are contributing to the market's growth.
Regionally, North America and Europe are expected to dominate the Next Generation Packaging Technology Market due to strong demand for sustainable and innovative packaging solutions. The presence of key market players and well-established infrastructure in these regions further supports market growth. The Asia-Pacific region is anticipated to witness significant growth during the forecast period, driven by the expanding e-commerce sector and increasing investments in the food and beverage industry. Latin America, the Middle East, and Africa are also expected to contribute to the market's growth, supported by the rising adoption of advanced packaging technologies and growing consumer awareness of environmental issues.
Market Insights:
- The Next Generation Packaging Technology Market is projected to grow from USD 12,852.9 million in 2024 to USD 20,843.88 million by 2032, at a CAGR of 6.23% during the forecast period.
- Increasing demand for sustainable packaging solutions and eco-friendly materials is a major driver, propelled by environmental regulations and consumer preference.
- Smart packaging technologies, such as RFID tags, sensors, and time-temperature indicators, are enhancing product safety, traceability, and supply chain efficiency.
- High implementation costs and technological complexity act as key restraints, especially for small and medium enterprises (SMEs).
- North America holds the largest market share, driven by early adoption of smart technologies and robust R&D activities in the packaging sector.
- Europe follows closely, supported by strict sustainability mandates and innovative packaging initiatives.
- The Asia-Pacific region is expected to witness the fastest growth, fueled by urbanization, e-commerce expansion, and increasing demand for advanced packaging solutions in China, India, and Japan.
Market Drivers:
Environmental Sustainability Demands:
The increasing focus on environmental impact has accelerated the adoption of next-generation packaging solutions, particularly in the food and beverage industry. For instance, companies are shifting toward biodegradable and compostable materials such as polylactic acid (PLA), which is derived from renewable resources like corn starch and naturally decomposes into non-toxic components. However, PLA disposal remains a challenge, as estimates suggest that a PLA bottle could take between 100 to 1,000 years to decompose in a landfill, highlighting the need for improved waste management systems. The global sustainable packaging market, valued at USD 272.93 billion in 2023, reflects the increasing demand for eco-friendly alternatives.
Smart Technology Integration:
The integration of advanced technologies has enhanced packaging functionality and consumer engagement. For instance, smart packaging systems now incorporate sensors for monitoring product conditions, nanotechnology for improved durability, and IoT capabilities for real-time tracking, enabling features such as freshness monitoring and interactive consumer experiences through QR codes and augmented reality (AR) interfaces. The use of digital identifiers allows comprehensive tracking of a package’s journey while ensuring product quality throughout the supply chain. For instance, the global smart packaging market was estimated at USD 36.04 billion in 2022, signaling substantial growth in this sector as companies invest in intelligent packaging solutions.
Regulatory Compliance and Safety Standards:
Government regulations play a crucial role in shaping packaging innovations, particularly in sustainability and consumer protection. For instance, the European Union’s Single-Use Plastics Directive has prompted companies to redesign their packaging materials and processes to meet stringent environmental requirements. In the UK, the Packaging Waste (Data Reporting) (England) Regulations 2023 require producers with an annual turnover exceeding £2 million and handling more than 50 tons of packaging per year to report data on the amount and type of packaging supplied. These regulations aim to reduce packaging waste while promoting improved recyclability, forcing manufacturers to rethink material choices and production processes.
Consumer Engagement and Transparency:
The demand for enhanced consumer interaction and product transparency continues to drive packaging innovation. For instance, smart packaging technologies enable consumers to access detailed product information, verify authenticity, and track product journeys using smartphones. These interactive features resonate particularly with younger generations, encouraging engagement through touch, smell, and visual experiences. For example, augmented reality (AR) in packaging allows consumers to unlock additional content, such as product videos, sustainability details, or virtual try-on experiences, enriching the overall customer journey.
Market Trends:
Smart and Interactive Packaging Solutions:
The integration of IoT and smart technologies is revolutionizing packaging, enhancing consumer engagement and supply chain transparency. For instance, the number of IoT-connected devices worldwide has surpassed 23 billion, enabling advanced tracking and interactive functionalities in packaging. Smart labels and temperature monitoring devices now achieve 99.9% accuracy in real-time condition tracking, ensuring product quality throughout distribution. For instance, interactive packaging solutions incorporating NFC technology have demonstrated a 45% increase in consumer engagement rates, while advanced systems can process up to 1,000 data points per second, delivering supply chain response times under 100 milliseconds.
Sustainable Materials Innovation:
The development of biodegradable and eco-friendly materials is reshaping packaging sustainability efforts. For instance, PLA-based packaging has been shown to reduce carbon footprints by 75% compared to conventional plastics. Additionally, innovations in PBAT-based materials enable complete biodegradation within 180 days under industrial composting conditions, supporting waste reduction initiatives. The adoption of bagasse-based packaging has resulted in a 60% reduction in plastic waste, while leading brands have increased the use of recycled content in packaging by 40%, further reducing environmental impact.
Personalization and Customization:
Personalized packaging has become a powerful tool for brand differentiation, significantly influencing consumer purchasing behavior. For instance, 70% of consumers prefer customized packaging experiences, prompting brands to adopt digital printing technologies that allow production runs as small as 50 units. This level of customization has led to 95% consumer engagement rates, reinforcing brand-consumer relationships. Companies implementing personalized QR codes on packaging have reported a 35% increase in customer interaction and a 28% boost in brand loyalty metrics.
Minimalist Design and Transparency:
Minimalist packaging is gaining traction as companies reduce material usage without compromising structural integrity. For instance, minimalist designs have led to a 25% reduction in packaging materials, supporting sustainability goals while maintaining durability. Transparency also plays a crucial role in consumer trust and purchase intent. Clear packaging solutions demonstrate 40% higher consumer trust ratings compared to opaque alternatives. Studies indicate that 85% of consumers make purchasing decisions based on their ability to view products through packaging, with transparent materials increasing purchase intent rates by 30%.
Market Challenges Analysis:
High Implementation Costs:
The adoption of advanced packaging technologies presents significant cost barriers, particularly for small and medium enterprises. For instance, the U.S. Department of Commerce reports that implementation costs for smart packaging solutions are 40-60% higher than traditional packaging methods, limiting accessibility for smaller companies. Additionally, the Environmental Protection Agency (EPA) states that sustainable material alternatives can cost up to 25% more than conventional packaging materials, creating financial challenges for widespread adoption.
Infrastructure and Technology Limitations:
The lack of adequate infrastructure and technical expertise hinders the effective deployment of IoT-enabled packaging solutions. For instance, the Federal Communications Commission (FCC) identifies that only 65% of manufacturing facilities currently possess the necessary infrastructure to support advanced packaging technologies, restricting large-scale adoption. Moreover, the National Institute of Standards and Technology (NIST) highlights that approximately 40% of companies lack the technical expertise required to implement and maintain sophisticated packaging systems, further slowing market expansion.
Regulatory Compliance Challenges:
Strict regulatory requirements add another layer of complexity to the adoption of next-generation packaging. For instance, the Food and Drug Administration (FDA) enforces stringent guidelines for food-contact materials and smart packaging components, with certification processes for new technologies taking between 6 to 18 months. Furthermore, the EPA mandates that manufacturers achieve a minimum of 30% recycled content in sustainable packaging materials, adding compliance challenges and increasing production costs.
Consumer Adoption and Education:
Consumer acceptance of smart and sustainable packaging solutions remains a challenge due to limited awareness and concerns about privacy. For instance, the Consumer Product Safety Commission reports that only 45% of consumers fully understand the functionalities of smart packaging features, while 35% express concerns about data privacy in IoT-enabled packaging. Additionally, the Department of Energy highlights that only 28% of recycling facilities are equipped to process advanced packaging materials effectively, impacting proper disposal and recycling rates.
Market Opportunities:
The Next Generation Packaging Technology Market presents substantial opportunities driven by the rising demand for advanced, sustainable, and intelligent packaging solutions across various industries. Growing concerns about food safety, product integrity, and extended shelf life have accelerated the adoption of active and smart packaging technologies. Industries such as food and beverages, pharmaceuticals, and personal care are increasingly integrating innovations like sensors, RFID tags, and time-temperature indicators to improve product traceability, ensure quality, and enhance supply chain efficiency. Additionally, the surge in e-commerce activities has created a demand for durable, eco-friendly, and tamper-proof packaging solutions to meet evolving consumer expectations and regulatory standards.
Sustainability remains a key opportunity area, as companies shift toward eco-friendly packaging materials to address environmental concerns and meet government mandates. The development of biodegradable, recyclable, and reusable packaging options opens new avenues for innovation, particularly in emerging markets where urbanization and environmental awareness are on the rise. The increasing integration of Internet of Things (IoT) and artificial intelligence (AI) in packaging technology offers opportunities to enable real-time product monitoring, fostering enhanced supply chain visibility and consumer engagement. Moreover, investments in research and development, along with strategic collaborations between packaging manufacturers and technology providers, are expected to accelerate the commercialization of cost-effective next-generation solutions, further driving market growth. As industries prioritize sustainability and product safety, the Next Generation Packaging Technology Market is positioned for significant advancements and widespread adoption globally.
Market Segmentation Analysis:
By Packaging Type
The market includes active packaging, intelligent packaging, and sustainable packaging. Active packaging enhances product longevity by incorporating oxygen scavengers, antimicrobial coatings, and moisture control solutions, making it a preferred choice in food and pharmaceutical industries. Intelligent packaging integrates QR codes, RFID tags, and temperature sensors to enable real-time tracking, condition monitoring, and consumer engagement. Sustainable packaging focuses on biodegradable, compostable, and recyclable materials, with increasing demand for bioplastics such as polylactic acid (PLA) and polybutylene adipate terephthalate (PBAT), which significantly reduce carbon footprints.
By Application
The application segment covers food and beverages, pharmaceuticals, personal care, and logistics. Food and beverage applications lead the market due to growing demand for extended shelf-life solutions, smart labeling, and freshness indicators. Pharmaceutical packaging follows closely, driven by track-and-trace technologies ensuring drug authenticity and compliance with stringent regulatory standards. Personal care packaging is evolving with eco-friendly solutions and smart dispensing systems, while logistics and e-commerce sectors increasingly utilize tamper-evident and IoT-enabled packaging for secure product tracking.
Segmentation:
Packaging Type:
- Active Packaging
- Antimicrobials
- Gas Scavengers
- Gas Emitters
- Others (Moisture & Corrosion Control)
- Intelligent Packaging
- Sensors
- Indicators
- Tags
- Modified Atmosphere Packaging
By Application:
- Food & Beverages
- Healthcare & Pharmaceuticals
- Personal Care
- Logistics & Supply Chain
- Others (Automotive & Industrial)
By Region:
-
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
North America dominates the market, holding 35% of the global share, driven by early adoption of innovative packaging technologies and strong sustainability initiatives. For instance, major industry players like Amcor, Sealed Air, and Avery Dennison are heavily investing in smart packaging solutions to meet growing consumer demand. The United States, a key market contributor, is witnessing rising demand for active packaging in the food, beverage, and pharmaceutical sectors. Approximately 30% of food produced in the U.S. goes to waste, prompting increased adoption of oxygen scavengers and antimicrobial coatings to extend shelf life. Additionally, high R&D investments exceeding USD 2 billion annually have accelerated advancements in IoT-enabled packaging, such as RFID and smart labels, further fueling market expansion.
Europe
Europe accounts for 28% of the market share, led by Germany, the United Kingdom, and France. For instance, the region's strict environmental regulations, including the European Union's Circular Economy Action Plan, mandate that 55% of plastic packaging be recyclable by 2030, driving demand for sustainable and biodegradable materials. The pharmaceutical sector has also increased its adoption of intelligent packaging to comply with Directive 2011/62/EU, which requires serialization and traceability to prevent counterfeit drugs. Nanotechnology innovations are improving barrier properties in food and beverage packaging, significantly extending shelf life and reducing waste.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth, holding a market share of 22%, driven by rapid urbanization and increased demand for packaged food and beverages. For instance, China dominates the region, accounting for over 40% of global packaging production, supported by cost-effective next-generation packaging solutions. Japan is at the forefront of smart packaging technologies, with rising adoption of time-temperature indicators in pharmaceuticals and perishable goods to ensure quality and compliance. Additionally, India's booming e-commerce market has attracted investments exceeding USD 500 million in packaging infrastructure, improving supply chain efficiency and sustainability.
Latin America
Latin America holds a moderate market share of 8%, fueled by increasing industrialization and demand for advanced packaging in the food and healthcare sectors. For instance, in Brazil, over 65% of consumers prefer sustainable packaging solutions, prompting businesses to shift toward biodegradable and recyclable materials. Similarly, Mexico is aligning with global sustainability trends, implementing policies that promote recyclable packaging materials and eco-friendly alternatives.
Middle East & Africa
The Middle East & Africa account for the 7% of the market, with growth driven by investments in food safety and healthcare infrastructure. For instance, Gulf countries like Saudi Arabia and the UAE are witnessing a packaging industry shift, with sustainable solutions gaining traction as governments work toward Vision 2030 sustainability goals. The adoption of smart packaging technologies in food and pharmaceutical sectors is increasing, ensuring enhanced product quality, safety, and traceability.
Key Player Analysis:
- Amcor Plc
- Sealed Air Corporation
- Avery Dennison Corporation
- Stora Enso Oyj
- Tetra Pak International S.A.
- Smurfit Kappa Group
- Ball Corporation
- WestRock Company
- Crown Holdings, Inc.
- BASF SE
Competitive Analysis:
The Next-Generation Packaging Technology Market is highly competitive, with leading players focusing on innovation, sustainability, and advanced technologies to maintain their market positions. Major companies such as Amcor Plc, Sealed Air Corporation, Avery Dennison Corporation, and Tetra Pak International dominate the industry with strong portfolios in smart, active, and sustainable packaging solutions. For instance, Amcor has invested over USD 100 million in recyclable packaging technologies to address increasing environmental regulations and consumer demand for eco-friendly alternatives. Strategic collaborations, acquisitions, and investments in R&D further intensify competition, with companies leveraging IoT-enabled packaging, RFID tracking, and nanotechnology to enhance product safety and supply chain efficiency. Emerging players are also gaining traction by introducing intelligent sensors and real-time monitoring solutions, reinforcing the industry's focus on sustainability, digitalization, and regulatory compliance.
Recent Developments:
- November 2024 Amcor Plc announced a definitive merger agreement with Berry Global Group, Inc., combining in an all-stock transaction to create a global leader in consumer and healthcare packaging solutions.
- August 2023 Amcor acquired Phoenix Flexibles, a Gujarat-based flexible packaging company, expanding its presence in the high-growth Indian market.
- September 2023 WestRock Company and Smurfit Kappa agreed to merge, forming Smurfit WestRock, one of the world's largest paper and packaging producers, enhancing their capabilities in next-generation packaging solutions.
- June 2023 Stora Enso announced plans to restructure its Packaging Materials division to focus on renewable and circular solutions, aiming to meet the growing demand for sustainable next-generation packaging.
Market Concentration & Characteristics:
The Next Generation Packaging Technology Market is characterized by a dynamic and competitive landscape, driven by the growing demand for innovative, sustainable, and smart packaging solutions across industries such as food and beverage, healthcare, and consumer goods. Market concentration is moderate, with key players actively investing in advanced technologies like active, intelligent, and smart packaging to gain a competitive edge. The industry is witnessing increased adoption of eco-friendly materials, digital printing, and IoT-enabled solutions to enhance product safety, shelf life, and traceability. Market leaders are leveraging strategic partnerships, mergers, and acquisitions to expand their global footprint and address evolving consumer demands. Meanwhile, emerging players are focusing on disruptive innovations to penetrate niche segments. This convergence of technological advancements and competitive strategies is fostering a resilient and rapidly evolving market, offering significant opportunities for stakeholders to drive growth and meet sustainability goals.
Report Coverage:
The research report offers an in-depth analysis based on Packaging Type, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Next Generation Packaging Technology Market is poised for substantial growth, driven by increasing demand for smart, sustainable, and intelligent packaging solutions.
- Advancements in IoT, sensors, and RFID technology will enhance real-time tracking, monitoring, and communication capabilities of packaging systems.
- Growing focus on eco-friendly and biodegradable materials will reshape packaging designs to align with global sustainability goals and regulations.
- Rising consumer demand for extended shelf life and improved product safety will spur innovations in active and intelligent packaging technologies.
- Integration of digital printing and smart labels will enable enhanced brand communication, personalization, and anti-counterfeiting measures.
- Adoption of automation and AI-driven packaging solutions will optimize supply chain efficiency and reduce operational costs for manufacturers.
- The food and beverage, healthcare, and personal care industries will continue to be primary drivers for next-generation packaging innovation.
- Increasing e-commerce penetration will fuel the demand for packaging that ensures product integrity, traceability, and secure delivery.
- Emerging technologies, such as nanotechnology and smart sensors, will open new avenues for enhanced functionality and performance in packaging.
- Collaboration among stakeholders, including manufacturers, technology providers, and regulatory bodies, will be essential for advancing sustainable and innovative packaging solutions globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Next Generation Packaging Technology Market?
What factors are driving the growth of the Next Generation Packaging Technology Market?
What are some challenges faced by the Next Generation Packaging Technology Market?
Who are the major players in the Next Generation Packaging Technology Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Next Generation Packaging Technology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Next Generation Packaging Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,852.9 million → 2032: USD 20,843.88 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Next Generation Packaging Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Next Generation Packaging Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Next Generation Packaging Technology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Next Generation Packaging Technology Market Drivers
- 3.3 Next Generation Packaging Technology Market Restraints & Challenges
- 3.4 Next Generation Packaging Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Next Generation Packaging Technology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Next Generation Packaging Technology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Next Generation Packaging Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Next Generation Packaging Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Next Generation Packaging Technology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Next Generation Packaging Technology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Next Generation Packaging Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Next Generation Packaging Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Next Generation Packaging Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Next Generation Packaging Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Next Generation Packaging Technology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Next Generation Packaging Technology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Next Generation Packaging Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Next Generation Packaging Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Next Generation Packaging Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Next Generation Packaging Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Next Generation Packaging Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Next Generation Packaging Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Next Generation Packaging Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
