
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Next-Generation Titrators market Size 2024 | USD 3,870.6 million |
| Next-Generation Titrators market, CAGR | 6% |
| Next-Generation Titrators market Size 2032 | USD 6,169.14 million |
Market Overview:
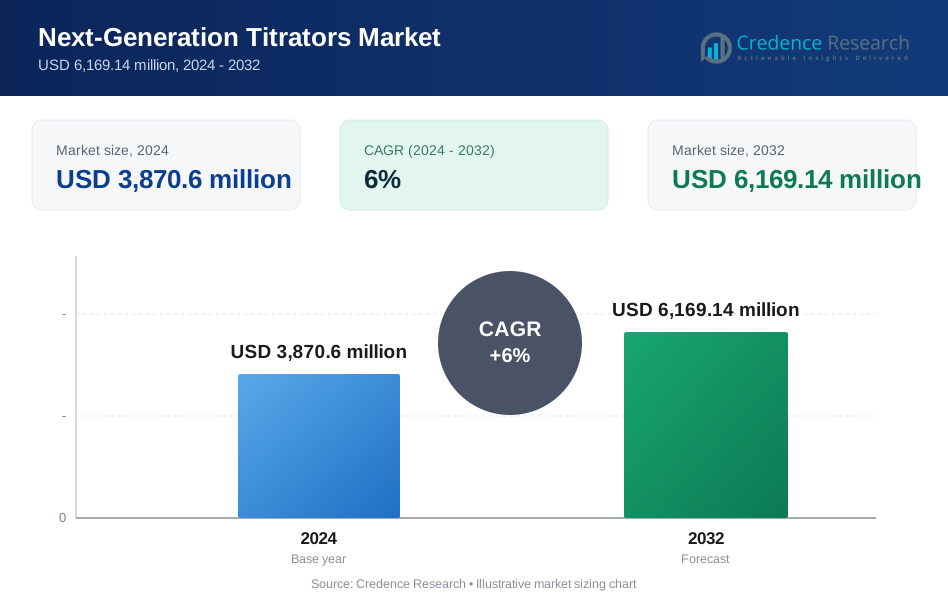
The Next-Generation Titrators market is projected to grow from USD 3,870.6 million in 2024 to USD 6,169.14 million by 2032, reflecting a compound annual growth rate (CAGR) of 6%.
The Next-Generation Titrators market is driven by advancements in laboratory automation, increasing demand for precise and efficient chemical analysis, and the growing emphasis on research and development in industries like pharmaceuticals, chemicals, and food & beverages. The rising need for high-quality analytical instruments that ensure accurate results and enhance productivity is boosting market growth. Additionally, the trend toward miniaturization of titrators and integration with digital technologies, such as cloud-based data storage and artificial intelligence for real-time analysis, is revolutionizing the industry. The development of titrators with enhanced features, such as improved user interfaces, automatic calibration, and multi-method capabilities, is also fueling market expansion. As industries focus on improving operational efficiency and meeting regulatory requirements, these innovations play a crucial role in driving demand for next-generation titrators. With a heightened focus on sustainability, the adoption of eco-friendly titration solutions further aligns with the market's evolving trends.
The Next-Generation Titrators market is witnessing significant growth across various regions. North America, holding around 40% of the market share in 2024, leads due to strong R&D infrastructure and regulatory standards, with key players like Mettler-Toledo and Thermo Fisher Scientific driving advancements. Europe, with a 30% share, follows closely, driven by industries focusing on quality control and sustainability, where companies like Metrohm AG and Hanna Instruments play a major role. The Asia Pacific region, accounting for 20% of the market, is experiencing rapid growth, particularly in China, India, and Japan, with key players like Xylem Inc. and Hach Company expanding their presence. The Rest of the World, including Latin America, the Middle East, and Africa, holds a smaller share but is gradually adopting next-generation titration systems, creating opportunities for market players in these regions.
Market Insights:
- The Next-Generation Titrators market is projected to grow from USD 3,870.6 million in 2024 to USD 6,169.14 million by 2032, reflecting a CAGR of 6%.
- Advancements in laboratory automation are driving market growth, enabling higher accuracy, precision, and efficiency in chemical analysis.
- Increasing demand for precise analytical instruments in industries such as pharmaceuticals, chemicals, and food & beverages is fueling market expansion.
- Integration of digital technologies, including AI, cloud computing, and IoT, is enhancing titrators' capabilities, allowing real-time analysis and improved decision-making.
- Growing emphasis on sustainability is leading to the development of eco-friendly titration solutions that minimize waste, reduce energy consumption, and use sustainable materials.
- North America is expected to hold the largest market share of 40% in 2024, driven by strong R&D infrastructure and regulatory standards.
- Asia Pacific is forecasted to experience the highest growth rate, with a 20% market share in 2024, fueled by industrialization and increasing automation in laboratories.
Market Drivers:
Advancements in Laboratory Automation:
The growing demand for laboratory automation is a significant driver of the Next-Generation Titrators market. Automation streamlines the titration process, allowing laboratories to handle higher sample volumes while maintaining quality results. As industries such as pharmaceuticals, chemicals, and food & beverages increasingly rely on automation to improve efficiency and throughput, the demand for advanced titration instruments continues to rise.
Increasing Demand for Precise Analytical Instruments:
Next-Generation Titrators are increasingly sought after due to their ability to deliver precise and reliable results. For instance, Hanna Instruments introduced a new generation of titrators with a 50% smaller footprint, allowing for easier integration in modern laboratories while maintaining high accuracy. As industries focus on stringent quality control, regulatory compliance, and high-performance standards, the need for advanced titration solutions has expanded. This demand for precision in analytical instrumentation drives the market's growth.
Integration of Digital Technologies:
The integration of digital technologies such as artificial intelligence (AI), cloud computing, and IoT is significantly influencing the Next-Generation Titrators market. These technologies enable real-time data analysis, remote monitoring, and enhanced decision-making capabilities. Cloud-based solutions allow seamless data storage and sharing, making it easier for laboratories to access and analyze historical data, thus enhancing overall productivity and research outcomes.
Focus on Sustainability and Eco-friendly Solutions:
Sustainability is an increasingly important driver in the Next-Generation Titrators market. With growing environmental concerns and the push for greener solutions, manufacturers are focusing on such innovations. These innovations align with global efforts to adopt environmentally responsible practices and contribute to the market's expansion, as industries seek to balance performance with environmental impact.
Market Trends:
Miniaturization of Titrators:
One of the key trends in the Next-Generation Titrators market is the miniaturization of titration instruments. This trend is driven by the increasing demand for portable and space-efficient laboratory equipment, particularly in research and development environments where space and budget constraints are common. Miniaturized titrators offer greater flexibility, allowing users to conduct multiple tests without sacrificing functionality, making them highly desirable in both academic and commercial laboratories.
Enhanced User Interfaces and Automation:
Another prominent trend is the development of titrators with enhanced user interfaces and greater automation capabilities. Automation features, such as automatic titration and data recording, further reduce the potential for human error and improve efficiency. For instance, SI Analytics' TitroLine® 7000 boasts a high visibility full color graphic display, viewable from extreme angles, and offers three USB. These innovations cater to the growing need for laboratories to operate at higher throughput with consistent accuracy and minimal manual intervention.
Integration with Cloud-based Solutions:
The integration of titration systems with cloud-based platforms is a growing trend in the market. This capability enhances collaboration among research teams and ensures that data is securely stored and accessible for future reference. The cloud integration trend is particularly valuable for large-scale laboratories and industries with multiple locations, allowing for streamlined operations and better data management.
Shift Toward Eco-friendly Solutions:
There is a noticeable shift toward more eco-friendly titration solutions in the market. This trend is in response to both regulatory requirements and growing environmental concerns, with industries aiming to reduce their carbon footprint while maintaining high analytical standards. For instance, Ayas Renewables specializes in converting agricultural waste, specifically glycerin, into high-value renewable propylene glycol (PG). The emphasis on sustainability is shaping the future of titration technology and driving innovation in the field.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs:
One of the primary challenges in the Next-Generation Titrators market is the high initial investment and maintenance costs associated with advanced titration systems. While these instruments offer significant advantages in terms of precision, automation, and data integration, their purchase price can be prohibitive, particularly for small to mid-sized laboratories and organizations. Additionally, ongoing maintenance costs, including calibration, software updates, and replacement of parts, can further strain budgets. For instance, Metrohm offers preventive maintenance performed by certified service engineers to prevent instrument failure and protect against costly repairs, recommending this service at least once a year, which adds to the operational costs. These expenses may limit the accessibility of next-generation titrators to only large corporations or well-funded research institutions, thereby hindering market penetration in certain regions or sectors. The challenge of balancing performance with affordability remains a key concern for both manufacturers and end-users, especially as demand for more cost-effective solutions grows. For many smaller laboratories, especially those in developing markets, the costs associated with adoption and upkeep can prove to be significant barriers, affecting the overall growth potential of the market in these areas.
Technological Complexity and Training Requirements:
As the capabilities of Next-Generation Titrators increase, so does their technological complexity, creating a challenge in terms of user adaptation and training. While these advanced systems offer numerous benefits, such as automation and AI-driven analysis, they require skilled operators who are well-versed in both the software and hardware components. Laboratories and organizations may face difficulties in finding qualified personnel capable of effectively utilizing these sophisticated instruments. Moreover, the need for continuous training and updates to stay current with software advancements adds to the operational burden. As a result, organizations must invest in training programs, which can be time-consuming and costly. Additionally, there is the challenge of integrating new titration technology with existing laboratory systems and workflows, requiring potential upgrades to infrastructure and posing a barrier to smooth adoption. These factors can delay the widespread adoption of next-generation titrators in certain industries, particularly where budget constraints or workforce limitations exist.
Market Opportunities:
The Next-Generation Titrators market presents significant opportunities driven by the ongoing advancements in automation and digital technologies. As industries increasingly prioritize efficiency and precision, there is a growing demand for titration systems that integrate automation and real-time data analytics. These solutions not only reduce human error but also improve productivity by enabling high-throughput testing and seamless data management. The potential to incorporate artificial intelligence (AI) for self-calibration and automated analysis further expands the market opportunities, as these technologies enhance accuracy and decision-making in laboratories. Additionally, the rise of cloud-based solutions for data storage and sharing offers laboratories the ability to collaborate more effectively and streamline operations, opening avenues for innovation and growth in both commercial and academic sectors.
Furthermore, there is a strong opportunity for the Next-Generation Titrators market to capitalize on the global shift towards sustainability. As industries continue to face increasing regulatory pressure to reduce environmental impacts, the demand for eco-friendly and energy-efficient titration solutions is expected to rise. Manufacturers have the opportunity to develop titration systems that minimize waste, optimize chemical usage, and reduce energy consumption. This aligns with the broader trend of green technologies and sustainability goals in various industries, such as pharmaceuticals, food & beverages, and environmental testing. The market's potential to provide innovative, eco-conscious solutions that meet regulatory standards while improving performance positions it for continued growth and adoption across a wide range of sectors.
Market Segmentation Analysis:
By Product Type
The Next-Generation Titrators market can be segmented by product type into manual titrators, automatic titrators, and advanced titrators with integrated automation and AI features. Automatic titrators are expected to dominate the market due to their precision, efficiency, and ability to handle high-throughput testing. Advanced titrators, which offer automated processes and real-time data analysis, are seeing growing demand, particularly in research-intensive industries.
By Application
The market is further segmented by application, with key industries including pharmaceuticals, chemicals, food & beverages, and environmental testing. The pharmaceutical sector holds a significant share due to the need for accurate and reliable titration for drug formulation and quality control. Chemical manufacturers and environmental testing facilities also represent major application areas, driven by regulatory requirements and the need for precise chemical analysis in product development and sustainability practices.
Segments:
Based on Product Type:
- Potentiometric Titrators
- Karl Fischer Titrators
- Coulometric Titrators
- Others
Based on Application
- Pharmaceuticals
- Food and Beverage
- Environmental Testing
- Chemical
- Others
Based on End-User
- Laboratories
- Research Institutes
- Industrial
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America is poised to dominate the Next-Generation Titrators market, holding an estimated market share of 40% in 2024. The region benefits from robust research and development activities, particularly in the United States and Canada, which are leaders in pharmaceutical, chemical, and environmental industries. The demand for highly precise and automated titration systems is driven by stringent regulatory standards and the growing focus on improving laboratory efficiency. Additionally, the increasing use of AI-driven titrators for real-time data analysis and automated processes across various sectors like pharmaceuticals, food & beverages, and environmental testing further supports North America's market leadership. The region’s commitment to sustainability and the development of eco-friendly titration solutions also contribute to market expansion.
Europe:
Europe is a significant player in the Next-Generation Titrators market, accounting for 30% of the market share in 2024. Key markets such as Germany, the United Kingdom, and France are seeing increased adoption of advanced titration systems due to the thriving pharmaceutical, chemical, and food industries. The European market is characterized by a strong emphasis on quality control, regulatory compliance, and environmental sustainability. As laboratories seek to meet stringent regulatory standards and improve operational efficiency, the demand for automated titrators that offer high precision and reduced human error continues to rise. Additionally, Europe’s increasing push toward eco-friendly solutions has influenced the development of more sustainable titration technologies.
Asia Pacific:
Asia Pacific is forecasted to experience the highest growth rate in the Next-Generation Titrators market, with an estimated market share of 20% in 2024. This region, led by countries like China, India, and Japan, is undergoing rapid industrialization, particularly in the pharmaceutical, food & beverages, and chemical sectors. Growing research and development activities, coupled with the rising need for automation and precision in laboratories, are fueling the demand for advanced titration systems. As industries in Asia Pacific seek to enhance productivity and ensure compliance with international standards, the adoption of next-generation titrators is accelerating. Additionally, the increasing focus on sustainability in manufacturing processes further drives the demand for energy-efficient and eco-friendly titration solutions.
Rest of the World:
The Rest of the World, comprising Latin America, the Middle East, and Africa, holds a smaller share of 10% in 2024. However, these regions are showing growing interest in Next-Generation Titrators as industrialization and investments in research infrastructure continue to rise. In markets such as Brazil, Saudi Arabia, and South Africa, there is a growing demand for accurate and efficient titration systems in the chemical, food, and pharmaceutical sectors. As these regions increasingly prioritize sustainability and regulatory compliance, the adoption of advanced titration technologies is expected to gradually increase over the coming years, contributing to the overall market growth.
Key Player Analysis:
- Eppendorf AG
- Hanna Instruments, Inc.
- Xylem Inc.
- Metrohm AG
- Hach Company
- KEM (Kyoto Electronics Manufacturing Co., Ltd.)
- Mettler-Toledo International Inc.
- DKK-TOA Corporation
- Analytik Jena AG
- Thermo Fisher Scientific Inc.
- Hiranuma Sangyo Co., Ltd.
Competitive Analysis:
The Next-Generation Titrators market is highly competitive, with leading players such as Mettler-Toledo International Inc., Metrohm AG, Hanna Instruments, Inc., Thermo Fisher Scientific Inc., Xylem Inc., Hach Company, DKK-TOA Corporation, KEM (Kyoto Electronics Manufacturing Co., Ltd.), Analytik Jena AG, Eppendorf AG, and Hiranuma Sangyo Co., Ltd. These companies are focusing on technological innovations, product diversification, and strategic collaborations to maintain their market position. Mettler-Toledo and Metrohm, for example, have heavily invested in automation and AI-driven titrators, while Thermo Fisher and Hanna Instruments emphasize advanced user interfaces and integration with cloud-based platforms. Additionally, companies are responding to market demand for eco-friendly solutions, with several firms launching titrators designed to reduce chemical waste and energy consumption. Intense competition is further fueled by the growing adoption of titration technology in emerging markets, as companies strive to expand their presence globally.
Recent Developments:
- In 2025, KEM develops and manufactures analytical instruments, including Automatic Potentiometric Titrators and Karl Fischer Moisture Titrators.
- In October 2024, Mettler Toledo launched the EVA Volumetric Karl Fischer Titrator, designed for efficient and precise water content determination.
Market Concentration & Characteristics:
The Next-Generation Titrators market exhibits moderate concentration, with a mix of established global players and emerging regional companies. Leading manufacturers, such as Mettler-Toledo, Metrohm AG, and Thermo Fisher Scientific, dominate the market by offering advanced, automated titration systems with cutting-edge features like AI integration and real-time data analysis. These companies have significant market share due to their strong R&D capabilities, extensive distribution networks, and established brand recognition. However, the market also features a range of smaller players focused on niche applications or region-specific demands. As technological advancements continue, market dynamics are evolving, with companies increasingly investing in innovations like eco-friendly solutions and enhanced user interfaces to gain a competitive edge. This shift is leading to a diversification in product offerings, addressing the rising demand for precise, efficient, and sustainable titration technologies across various industries.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Next-Generation Titrators market is expected to experience consistent growth, driven by increasing demand for precision and automation in laboratories.
- Advancements in artificial intelligence and machine learning will continue to enhance titrator functionalities, enabling real-time analysis and self-calibration.
- Increased focus on sustainability will lead to the development of eco-friendly titrators with reduced energy consumption and waste.
- The pharmaceutical industry will remain a key driver, with growing requirements for accurate chemical analysis and regulatory compliance.
- The integration of digital technologies, such as cloud computing and IoT, will further streamline titration processes and improve data management.
- The market will see rising adoption in emerging economies due to rapid industrialization and investments in research and development.
- Miniaturization of titrators will create opportunities for compact and portable solutions, expanding their use in field-based applications.
- Smaller laboratories and institutions will benefit from cost-effective titrators, as manufacturers aim to make advanced systems more affordable.
- The demand for multi-method titrators, capable of handling diverse testing requirements, will increase across various sectors.
- Continuous innovations and technological improvements will ensure that next-generation titrators remain at the forefront of laboratory automation and efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Next-Generation Titrators market?
What factors are driving the growth of the Next-Generation Titrators market?
What are the key segments within the Next-Generation Titrators market?
Who are the major players in the Next-Generation Titrators market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Next-Generation Titrators Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Next-Generation Titrators Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,870.6 million → 2032: USD 6,169.14 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Next-Generation Titrators Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Next-Generation Titrators Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Next-Generation Titrators Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Next-Generation Titrators Market Drivers
- 3.3 Next-Generation Titrators Market Restraints & Challenges
- 3.4 Next-Generation Titrators Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Next-Generation Titrators Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Next-Generation Titrators Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Next-Generation Titrators category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Next-Generation Titrators Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Next-Generation Titrators Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Next-Generation Titrators market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Next-Generation Titrators Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Next-Generation Titrators Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Next-Generation Titrators Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Next-Generation Titrators (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Next-Generation Titrators Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Next-Generation Titrators Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Next-Generation Titrators Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Next-Generation Titrators Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Next-Generation Titrators Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Next-Generation Titrators Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Next-Generation Titrators Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Next-Generation Titrators Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Next-Generation Titrators Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
