
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Cartilage Repair Regeneration Market Size 2024 | USD 2,762.03 million |
| North America Cartilage Repair Regeneration Market , CAGR | 5.53% |
| North America Cartilage Repair Regeneration Market Size 2032 | USD 4,248.70 million |
Market Overview
The North America Cartilage Repair Regeneration Market is projected to grow from USD 2,762.03 million in 2024 to an estimated USD 4,248.70 million by 2032, with a compound annual growth rate (CAGR) of 5.53% from 2025 to 2032. This growth is driven by increasing demand for advanced regenerative treatments and the rising prevalence of joint-related diseases, particularly osteoarthritis.
Key drivers of this market include technological advancements in regenerative therapies such as stem cell-based treatments and tissue engineering. The growing awareness of minimally invasive procedures and the development of biologically enhanced therapies further contribute to market expansion. Additionally, rising healthcare expenditures and improved access to treatment options in both the United States and Canada are fueling the demand for cartilage repair and regeneration therapies.
Geographically, the United States holds the largest share of the North American market, due to the presence of a well-established healthcare infrastructure and high healthcare spending. Canada also plays a significant role, supported by increasing government initiatives to promote advanced medical treatments. Leading players in the market include major companies such as Zimmer Biomet, Johnson & Johnson, Stryker Corporation, and Medtronic, all of which are focusing on innovation and strategic collaborations to enhance their market presence.
Market Insights
- The North America Cartilage Repair Regeneration Market is projected to grow from USD 2,762.03 million in 2024 to USD 4,248.70 million by 2032, driven by a 5.53% CAGR.
- The Global Cartilage Repair Regeneration Market reached USD 5,599.25 million in 2024 and will grow at a 5.58 % CAGR to USD 8,648.13 million by 2032.
- Advancements in stem cell-based therapies, tissue engineering, and growing demand for minimally invasive procedures are major market drivers.
- Increasing prevalence of osteoarthritis and other joint diseases, particularly among the aging population, is fueling market demand.
- Continuous innovation in regenerative treatments, including biologically enhanced therapies, is expanding treatment options.
- High treatment costs and regulatory challenges in adopting new technologies may limit market growth.
- The U.S. holds the largest market share, owing to its well-established healthcare infrastructure and high healthcare spending.
- Canada plays a significant role in market growth, supported by government initiatives promoting advanced medical treatments.
Report Scope
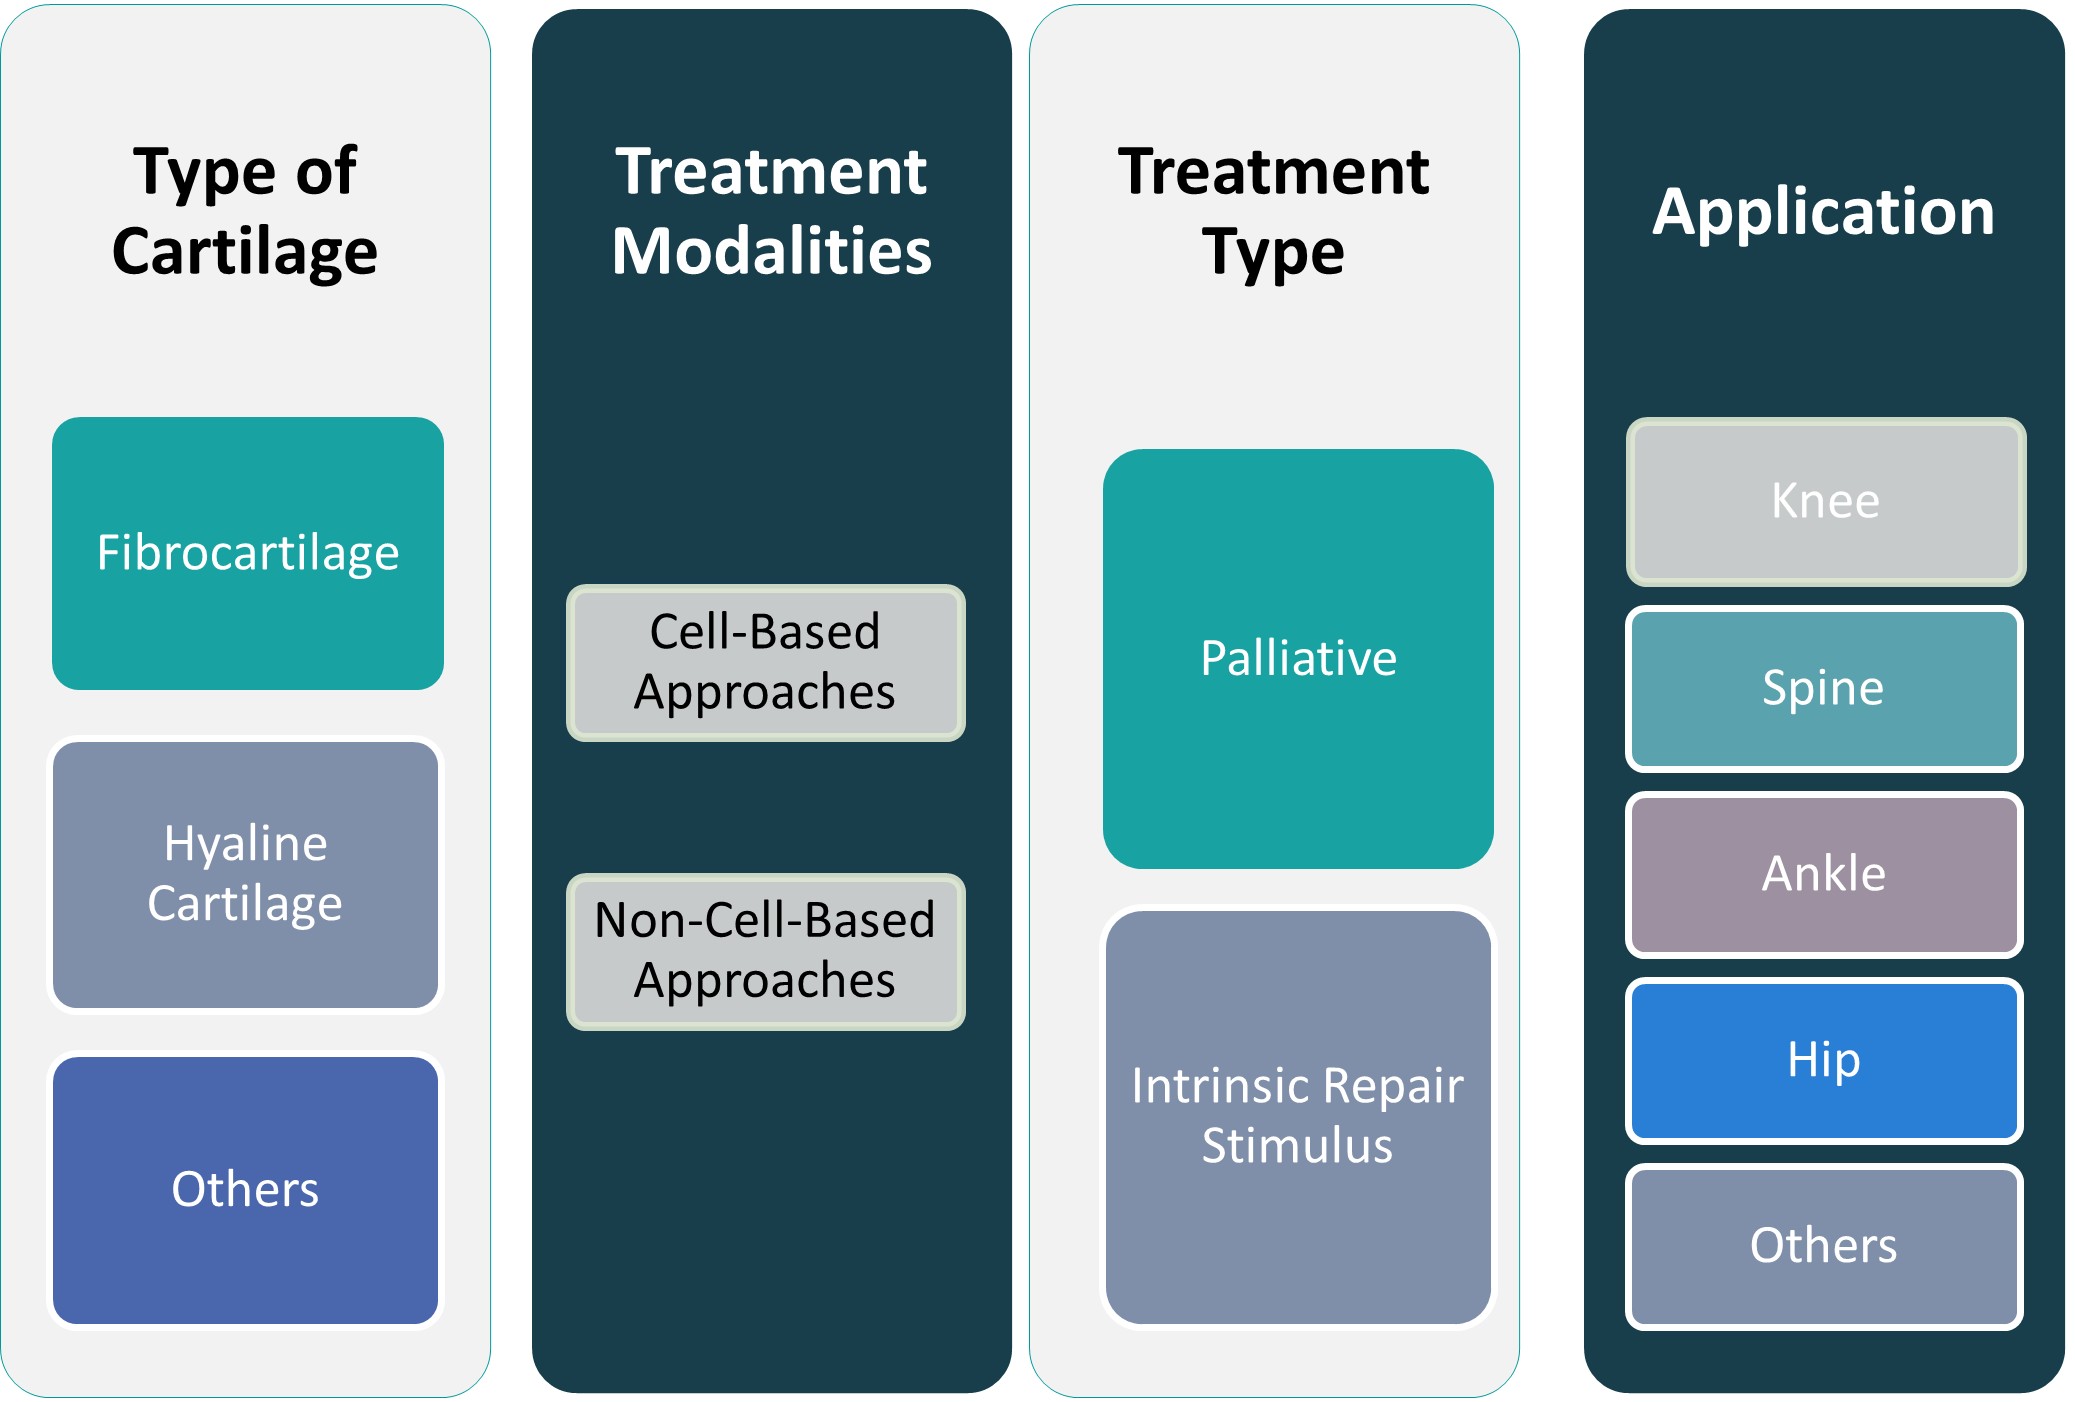
This report segments the North America Cartilage Repair Regeneration Market as follows:
Market Drivers
Growing Prevalence of Osteoarthritis and Joint Disorders
The increasing incidence of osteoarthritis and other joint-related disorders in North America is a key driver for the growth of the North America Cartilage Repair Regeneration Market. The aging population in both the United States and Canada is particularly susceptible to joint degradation, resulting in a higher demand for cartilage repair solutions. The rising burden of these conditions has prompted greater attention to alternative treatments, including regenerative therapies. This growing health concern boosts the adoption of cartilage repair technologies and contributes to market expansion.
- For instance, North America recorded over 2,152,900 cartilage-related disorder cases in 2023, highlighting the rising demand for effective repair therapies.
Technological Advancements in Cartilage Repair Treatments
Advancements in cartilage repair and regeneration technologies are driving market growth. Innovative solutions, such as stem cell-based therapies, tissue engineering, and biologically enhanced treatments, offer significant improvements over traditional surgical methods. These developments provide patients with more effective and less invasive options, contributing to a shift in treatment preferences. The continuous research and innovation in regenerative medicine are creating new avenues for market growth, positioning North America as a hub for cutting-edge medical treatments.
- For instance, North America has seen a significant rise in the adoption of advanced cartilage repair techniques, with regenerative medicine and biologically enhanced treatments diving innovation in the field.
Rising Healthcare Expenditures and Access to Treatment
Increased healthcare spending in North America has contributed to the growth of the cartilage repair market. Governments and private sectors alike are investing in advanced medical technologies and regenerative treatments to improve patient outcomes. The expansion of insurance coverage and better access to healthcare services have made these treatments more available to a larger patient base. As more people seek medical interventions for cartilage-related issues, the North America Cartilage Repair Regeneration Market is set to grow further.
Focus on Minimally Invasive and Patient-Centric Procedures
The demand for minimally invasive procedures is another crucial driver of the North America Cartilage Repair Regeneration Market. Patients increasingly seek treatments that offer quicker recovery times, reduced risks, and minimal scarring. The rise of outpatient and same-day procedures aligns with this trend, as these therapies offer less downtime compared to traditional surgeries. This shift toward patient-centric treatments is boosting the adoption of cartilage repair solutions that focus on improving the overall patient experience while achieving effective outcomes.
Market Trends
Increasing Adoption of Stem Cell and Regenerative Therapies
One of the key trends in the North America Cartilage Repair Regeneration Market is the growing adoption of stem cell and regenerative therapies. These cutting-edge treatments provide promising alternatives to traditional cartilage repair surgeries by promoting tissue regeneration and minimizing the need for invasive procedures. Stem cell-based therapies, along with advancements in tissue engineering, are increasingly seen as effective solutions for cartilage damage, offering patients improved healing potential and long-term benefits. These treatments are gaining traction in clinical settings, particularly for patients with advanced joint degeneration who seek less invasive options to restore functionality and reduce pain.
- For instance, in 2024, over 9,200 stem cell-based cartilage repair procedures were performed in North America, highlighting the increasing adoption of regenerative therapies
Rising Demand for Personalized and Customized Treatments
The demand for personalized and customized cartilage repair solutions is a significant trend within the North America Cartilage Repair Regeneration Market. With advancements in biotechnology, treatments are becoming more tailored to individual patient needs, considering factors such as genetic makeup, severity of cartilage damage, and overall health. Personalized approaches ensure higher success rates and better patient outcomes by optimizing treatment plans to target specific tissue repair needs. This trend reflects a broader shift towards patient-centered care, where treatments are designed to address unique health concerns, offering more effective and durable solutions for cartilage regeneration.
- For instance, as of 2025, more than 4,500 patients in North America have undergone personalized cartilage repair treatments using advanced biomaterials, demonstrating the growing demand for customized therapies
Market Challenges
High Production Costs and Limited Availability of Raw Materials
One of the significant challenges facing the Gluten Free Flour Market is the high production costs associated with gluten-free flour. The sourcing of gluten-free grains, such as rice, corn, and sorghum, often requires more specialized processing methods and facilities, leading to increased expenses. These higher costs can be passed on to consumers, making gluten-free products more expensive compared to their gluten-containing counterparts. Furthermore, there is a limited availability of high-quality gluten-free raw materials, which can hinder production capabilities and limit supply. This scarcity can lead to fluctuations in pricing and availability, affecting market stability.
- For instance, the cost of gluten-free flour production can be 1.5 to 2 times higher than traditional wheat flour, due to specialized processing and raw material sourcing requirements
Consumer Awareness and Perception Issues
Despite the growing demand for gluten-free products, consumer awareness remains a challenge for the Gluten Free Flour Market. Many consumers still lack a comprehensive understanding of the health benefits and uses of gluten-free flour, especially outside of celiac disease and gluten sensitivity groups. There is also the challenge of overcoming consumer perceptions that gluten-free products are less flavorful or have inferior texture compared to traditional flour-based products. These perceptions can hinder the widespread adoption of gluten-free flour in mainstream cooking and baking, limiting its potential market growth.
Market Opportunities
Expansion of Clinical Applications and Treatment Options
The North America Cartilage Repair Regeneration Market presents opportunities for expanding clinical applications across various patient demographics. With the growing prevalence of joint-related disorders, there is a significant opportunity to develop new treatments that address a wider range of conditions, including early-stage cartilage damage and more complex, degenerative diseases. Expanding the use of regenerative therapies into different treatment areas can improve patient outcomes and enhance the market's reach. As research continues, these therapies have the potential to offer more versatile solutions for various cartilage-related conditions, thus broadening their applicability
Strategic Collaborations and Partnerships
Strategic collaborations between research institutions, healthcare providers, and industry leaders represent another valuable opportunity in the North America Cartilage Repair Regeneration Market. Partnerships focused on clinical trials, technology advancements, and distribution channels can accelerate the development of innovative cartilage repair treatments. By leveraging the expertise and resources of key players in the healthcare and biotechnology sectors, companies can expand their product offerings and gain a competitive edge. These collaborations can also facilitate faster market entry for new products and therapies, addressing unmet needs within the cartilage repair space.
Market Segmentation Analysis
By Type of Cartilage
The North America Cartilage Repair Regeneration Market is segmented by the type of cartilage, including fibrocartilage, hyaline cartilage, and others. Fibrocartilage is commonly found in joint areas such as the knee and spine, while hyaline cartilage plays a key role in smooth joint movement. Hyaline cartilage repair is often more challenging due to its limited regenerative capacity, leading to increased demand for advanced regenerative treatments. The market for fibrocartilage repair is also growing, driven by its application in knee and spine treatments.
By Treatment Modalities
This market is also segmented by treatment modalities, specifically cell-based and non-cell-based approaches. Cell-based approaches, such as stem cell therapies, are gaining prominence due to their ability to regenerate cartilage and provide long-term benefits. Non-cell-based approaches, such as biomaterials and scaffolds, are also widely used for cartilage repair. Both approaches contribute to market growth by offering effective solutions for cartilage regeneration, catering to various patient needs and treatment preferences.
Segments
Based on Type of Cartilage
- Fibrocartilage
- Hyaline Cartilage
- Others
Based on Treatment Modalities
- Cell-Based Approaches
- Non-Cell-Based Approaches
Based on Treatment Type
- Palliative
- Intrinsic Repair Stimulus
Based on Application
- Knee
- Spine
- Ankle
- Hip
- Others
Based on Region
- United States
- Canada
Regional Analysis
United States: The Leading Market in Cartilage Repair
The United States plays a dominant role in the North America Cartilage Repair Regeneration Market, driven by its advanced healthcare infrastructure and high healthcare spending. The country has a large population suffering from osteoarthritis and other joint-related disorders, which drives the demand for effective cartilage repair treatments. The adoption of innovative therapies, including stem cell-based and tissue-engineering approaches, is high, as patients seek minimally invasive and long-lasting solutions. The U.S. also benefits from substantial investments in research and development, leading to the introduction of new technologies and treatment options. Additionally, strong collaborations between private companies, academic institutions, and healthcare providers foster continued market expansion in the U.S.
Canada: Rising Demand for Advanced Cartilage Repair Solutions
Canada contributes significantly to the North America Cartilage Repair Regeneration Market, with growing awareness of regenerative therapies and their benefits. The country’s healthcare system provides widespread access to advanced medical treatments, including cartilage repair solutions. With an aging population and an increasing incidence of musculoskeletal disorders, the demand for effective cartilage repair methods is on the rise. Canadian healthcare providers are increasingly adopting cutting-edge regenerative techniques, such as cell-based therapies, to treat cartilage damage. Moreover, the Canadian government’s support for healthcare innovations further accelerates the adoption of new technologies in the cartilage repair space.
Market Trends Across North America
Across North America, there is a clear trend toward the adoption of minimally invasive and personalized treatment options for cartilage repair. Both the U.S. and Canada are experiencing a shift toward biologically-based therapies, such as stem cell treatments and tissue regeneration techniques, which provide patients with better outcomes and reduced recovery times. This trend is complemented by an increasing focus on patient-centric care, where treatments are tailored to individual needs, thereby improving success rates and overall satisfaction. The growing preference for these advanced therapies, coupled with significant healthcare investments, positions North America as a leading market for cartilage repair regeneration solutions.
Key players
- Zimmer Biomet Holdings Inc.
- Stryker Corporation
- Collagen Solutions
- Arthrex Inc.
- Anika Therapeutics Inc.
Competitive Analysis
The North America Cartilage Repair Regeneration Market is highly competitive, with key players focusing on innovative treatments and advanced technologies. Zimmer Biomet Holdings Inc. and Stryker Corporation are leaders in the market, known for their extensive product portfolios that include joint repair devices and regenerative therapies. These companies continue to invest in research and development to enhance their offerings, ensuring a competitive edge in cartilage repair solutions. Collagen Solutions and Anika Therapeutics Inc. provide niche products that focus on biologically-driven cartilage repair, tapping into the growing demand for regenerative treatments. Arthrex Inc. has made significant strides in providing minimally invasive surgical solutions for cartilage repair, further intensifying the competition. The market is driven by ongoing product innovations, strategic partnerships, and mergers, allowing these players to strengthen their positions in the region and expand their customer base
Recent Developments
- In April 2024, Zimmer Biomet and Arthrogenics entered a partnership to co-develop next-generation biologic medicines for cartilage repair, aiming to leverage Arthrogenics’ cell-therapy expertise alongside Zimmer Biomet’s orthopedic portfolio.
- In February 2024, the U.S. FDA granted 510(k) clearance for Zimmer Biomet’s ROSA Shoulder System, the first robotic-assisted solution cleared for total and reverse shoulder arthroplasty, signaling enhanced precision in joint restoration procedures.
- In June 2024, Askel Healthcare Ltd presented first clinical-trial results of its COPLA knee cartilage implant at the 9th Joint Preservation Congress in Warsaw, demonstrating early safety and functional gains in focal cartilage repair
- On September 17, 2024, Sparta Biomedical announced treatment of the first patients with its Ormi™ partial-knee resurfacing device, a biomimetic implant designed to restore cartilage function and slow osteoarthritis progression.
- On December 18, 2024, Mesoblast’s Ryoncil (remestemcel-L) received U.S. FDA approval as the first mesenchymal stromal cell therapy for pediatric steroid-refractory acute graft-versus-host disease, paving the way for broader MSC applications-including potential off-label exploration in cartilage repair contexts.
- On May 8, 2025, Smith + Nephew published 4-year follow-up data showing that patients treated with its CARTIHEAL™ AGILI-C™ implant experienced an 87% lower risk of eventual knee arthroplasty or osteotomy, underscoring long-term implant durability and functional improvement.
- In February 2025, Mesoblast reported financial and operational results confirming advancement of its proprietary mesenchymal-cell platform; the report noted ongoing preparation for pivotal trials in orthopedic indications, including chronic low back pain and osteoarthritis models.
Market Concentration and Characteristics
The North America Cartilage Repair Regeneration Market is moderately concentrated, with a few key players holding substantial market shares. Major companies like Zimmer Biomet Holdings Inc., Stryker Corporation, and Arthrex Inc. dominate the market due to their established product lines, extensive distribution networks, and ongoing investments in research and development. The market is characterized by high innovation, with a focus on stem cell-based therapies, tissue engineering, and biologically enhanced treatments. As new technologies emerge, smaller companies specializing in niche areas, such as Collagen Solutions and Anika Therapeutics Inc., have the opportunity to gain traction by offering specialized solutions. Competitive dynamics are shaped by the continuous development of minimally invasive procedures, personalized treatment options, and partnerships between healthcare providers and manufacturers, further enhancing the market’s potential for growth and diversification.
Report Coverage
The research report offers an in-depth analysis based on Type of Cartilage, Treatment Modalities, Treatment Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As research advances, stem cell-based treatments will continue to gain popularity, providing regenerative solutions with long-term benefits for cartilage repair.
- Ongoing innovations in tissue engineering, 3D printing, and biologically enhanced therapies will significantly improve the effectiveness of cartilage repair treatments.
- Patients’ preference for treatments with shorter recovery times and reduced risks will drive the growth of minimally invasive cartilage repair options in the region.
- The expanding elderly population in North America will create greater demand for cartilage repair solutions due to the increased prevalence of joint-related disorders, especially osteoarthritis.
- Improved insurance coverage for regenerative therapies will make cartilage repair treatments more accessible to a broader patient base, supporting market growth.
- Personalized medicine approaches tailored to individual patient needs will gain traction, ensuring more effective and targeted cartilage repair solutions.
- The shift toward outpatient care will encourage the adoption of less invasive, cost-effective, and faster recovery treatments, benefiting the overall market.
- Ongoing investments in healthcare innovations by both government and private companies will continue to drive the development and commercialization of advanced cartilage repair technologies.
- Collaborations between key players, research institutions, and healthcare providers will foster the development of new treatments and expand the market footprint of established companies.
- Growing awareness among patients and healthcare professionals regarding the benefits of regenerative therapies will increase demand for cartilage repair solutions across North America.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Prevalence of Osteoarthritis and Joint Disorders
The increasing incidence of osteoarthritis and other joint-related disorders, especially among the aging population in North America, is driving demand for advanced cartilage repair and regeneration solutions. This trend is leading to higher adoption of both established and innovative therapies.
Technological Advancements in Regenerative Therapies
Continuous innovation in stem cell-based treatments, tissue engineering, and biologically enhanced therapies is expanding the range and effectiveness of cartilage repair options. These advancements provide less invasive, more durable solutions, attracting both patients and healthcare providers.
Rising Healthcare Expenditures and Improved Access
Increased healthcare spending and broader insurance coverage in the U.S. and Canada are making advanced cartilage repair treatments more accessible. This financial support encourages adoption of new technologies and expands the patient base for regenerative therapies.
Shift Toward Minimally Invasive and Patient-Centric Procedures
Patients and clinicians are increasingly favoring minimally invasive procedures that offer faster recovery, reduced risk, and improved outcomes. This shift is accelerating the uptake of innovative cartilage repair techniques and driving market growth.
Expansion of Personalized and Customized Treatments
Advances in biotechnology are enabling more personalized cartilage repair solutions tailored to individual patient needs, improving success rates and patient satisfaction. This trend is fostering greater demand for customized regenerative therapies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the North America Cartilage Repair Regeneration Market in 2023 and 2032?
What are the key drivers of growth in the North America Cartilage Repair Regeneration Market?
What are the leading technologies in the North America Cartilage Repair Regeneration Market?
Who are the key players in the North America Cartilage Repair Regeneration Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Knee
- 1.2.2 Spine
- 1.2.3 Ankle
- 1.2.4 Hip
- 1.2.5 Others
- 1.3 By Type of Cartilage
- 1.3.1 Fibrocartilage
- 1.3.2 Hyaline Cartilage
- 1.3.3 Others
- 1.4 By Treatment Modalities
- 1.4.1 Cell-Based Approaches
- 1.4.2 Non-Cell-Based Approaches
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,762.03 million → 2032: USD 4,248.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Cartilage Repair Regeneration Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Cartilage Repair Regeneration Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Cartilage Repair Regeneration Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Cartilage Repair Regeneration Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Cartilage Repair Regeneration Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Cartilage Repair Regeneration Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Cartilage Repair Regeneration Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Cartilage Repair Regeneration Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,762.03 million → 2032: USD 4,248.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Cartilage Repair Regeneration Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Knee
- 12.3.7.2 Spine
- 12.3.7.3 Ankle
- 12.3.7.4 Hip
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type of Cartilage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fibrocartilage
- 12.4.7.2 Hyaline Cartilage
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment Modalities - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cell-Based Approaches
- 12.5.7.2 Non-Cell-Based Approaches
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Cartilage Repair Regeneration End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Cartilage Repair Regeneration Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Cartilage Repair Regeneration Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Cartilage Repair Regeneration Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Zimmer Biomet Holdings Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stryker Corporation
- 18.4 Arthrex Inc.
- 18.5 Anika Therapeutics Inc.
- 18.6 Collagen Solutions
- 18.7 Medtronic
- 18.8 Smith & Nephew
- 18.9 DePuy Synthes (Johnson & Johnson)
- 18.10 Vericel Corporation
- 18.11 Askel Healthcare Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

