
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Pancreatic Fistula Treatment Market Size 2024 | USD 2,495 million |
| Pancreatic Fistula Treatment Market, CAGR | 5.5% |
| Pancreatic Fistula Treatment Market Size 2032 | USD 3,829.04 million |
Market Overview
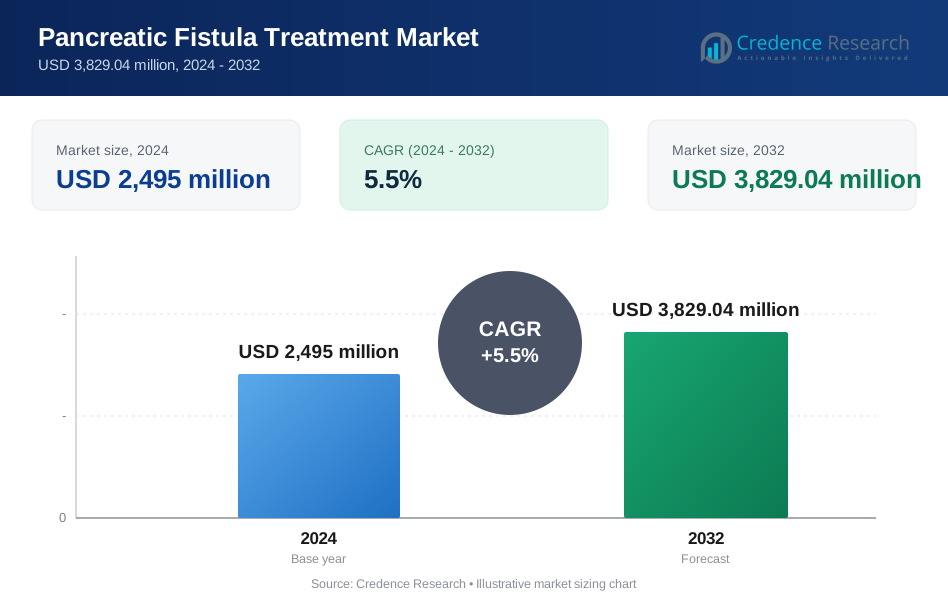
The Pancreatic Fistula Treatment market is expected to grow from USD 2,495 million in 2024 to USD 3,829.04 million by 2032, with a compound annual growth rate (CAGR) of 5.5%.
The Pancreatic Fistula Treatment market is driven by the rising incidence of pancreatic diseases and surgical procedures, leading to an increased need for effective management solutions. Advancements in minimally invasive surgical techniques and improved diagnostic tools enhance treatment efficacy and patient outcomes. Additionally, growing awareness of pancreatic health and the availability of innovative therapies are propelling market growth. Trends such as the development of biologics and personalized medicine further contribute to this landscape, providing tailored treatment options that address specific patient needs, thus fostering a more efficient and effective approach to managing pancreatic fistulas.
The pancreatic fistula treatment market shows varied growth across regions, with North America holding a significant share due to advanced healthcare infrastructure, high prevalence of pancreatic diseases, and strong adoption of minimally invasive surgeries. In Europe, rising healthcare investments and a growing elderly population are driving demand, particularly in countries like Germany and the UK. Key players contributing to market expansion include Becton Dickinson & Company, Medtronic plc, Novartis AG, and Olympus Corporation, who focus on developing advanced surgical and diagnostic solutions, meeting the rising need for innovative and efficient pancreatic fistula treatments across different geographies.
Market Drivers
Increasing Incidence of Pancreatitis
The rising prevalence of pancreatitis, both acute and chronic, significantly drives the demand for pancreatic fistula treatments. For instance, a study on the global burden of pancreatitis reported approximately 6.12 million prevalent cases and 1.64 million incident cases in 2017. Pancreatitis is a critical risk factor for the formation of pancreatic fistulas, as inflammation of the pancreas can compromise its structural integrity. With lifestyle factors and increasing rates of obesity contributing to the higher incidence of pancreatitis, there is a growing need for effective treatment options. As healthcare providers recognize the link between pancreatitis and pancreatic fistulas, the urgency for innovative solutions in management intensifies.
Advancements in Surgical Procedures
The complexity of pancreatic surgeries, particularly those related to pancreatic cancer and severe pancreatitis, poses a risk for developing pancreatic fistulas. However, advancements in surgical techniques, including minimally invasive procedures, are contributing to market growth. For example, robotic pancreatic surgery has shown significant improvements in perioperative and postoperative outcomes, enhancing the safety and effectiveness of surgical interventions. These innovations not only enhance the safety and effectiveness of surgical interventions but also reduce recovery times and complications associated with traditional surgeries. As the surgical landscape evolves, the demand for specialized treatments for pancreatic fistulas rises, driving further development in this market.
Aging Population and Unmet Medical Needs
The aging population is increasingly susceptible to age-related diseases, including pancreatitis and pancreatic cancer, which heightens the risk of pancreatic fistulas. This demographic shift underscores the need for effective treatment options tailored to older patients. Additionally, despite technological advancements, there remains a significant unmet need for minimally invasive and effective treatments for pancreatic fistulas. This gap drives ongoing research and innovation in the field, as healthcare providers seek better solutions for managing this challenging condition.
Growing Awareness and Technological Advancements
Growing awareness among healthcare providers and patients regarding pancreatic fistulas and their complications facilitates earlier diagnosis and timely treatment. Coupled with advancements in diagnostic tools, such as imaging modalities and endoscopic techniques, this awareness propels the market forward. Enhanced diagnostic capabilities enable more precise identification and management of pancreatic fistulas, leading to improved patient outcomes and fostering innovation in therapeutic interventions. As healthcare expenditure continues to rise, the market for pancreatic fistula treatment is expected to experience sustained growth, despite potential challenges such as high treatment costs and management complexities.
Market Trends
Increasing Prevalence of Pancreatitis
The rising incidence of both acute and chronic pancreatitis significantly drives the growth of the pancreatic fistula treatment market. As pancreatitis is a substantial risk factor for developing pancreatic fistulas, its increasing prevalence directly correlates with the need for effective treatment options. Factors such as lifestyle changes, increased alcohol consumption, and a diet high in fat contribute to the surge in pancreatitis cases, particularly in the aging population. Additionally, as surgical interventions for pancreatic diseases become more complex, there is a higher likelihood of complications, including pancreatic fistula formation. This creates an urgent need for advancements in treatment strategies, encouraging both healthcare providers and researchers to focus on innovative solutions.
Advancements in Technology and Awareness
Technological advancements play a crucial role in the market's evolution, with new diagnostic tools and therapeutic interventions emerging to improve patient outcomes. For example, a case report on pancreaticopleural fistula emphasized the importance of early diagnosis and intervention to manage complications effectively. Innovations such as endoscopic techniques and minimally invasive surgeries enhance the ability to diagnose and treat pancreatic fistulas effectively. Moreover, growing awareness among healthcare professionals and patients regarding pancreatic fistulas and their potential complications leads to earlier diagnoses and timely treatments, which can significantly improve patient prognoses. Despite these advancements, there remains a significant unmet medical need for effective and minimally invasive treatments. This gap drives ongoing research and development in the field, pushing the boundaries of current medical practices and opening avenues for novel therapeutic approaches. Collectively, these trends indicate a robust market trajectory, highlighting the importance of both technological innovation and increased awareness in addressing the challenges associated with pancreatic fistula treatment.
Market Challenges Analysis
High Treatment Costs and Adverse Effects
The treatment of pancreatic fistulas poses significant challenges, primarily due to high treatment costs associated with complex cases. For instance, a cost-benefit analysis of Hemopatch® used after pancreaticoduodenectomy showed substantial savings of $11,109 per patient compared to standard care, highlighting the financial burden of traditional treatments. These costs can escalate, particularly for patients requiring multiple interventions or prolonged hospital stays, placing a substantial financial burden on both individuals and healthcare systems. The economic impact extends beyond direct treatment expenses, as complications from pancreatic fistulas often lead to extended recovery times and additional medical resources. Furthermore, many treatment options, including surgical and endoscopic procedures, carry inherent risks and potential adverse effects. These complications can complicate the management of pancreatic fistulas, necessitating further interventions and contributing to the overall financial strain on patients. This situation creates a pressing need for more cost-effective treatment options that can reduce the burden on healthcare systems while improving patient outcomes.
Complexity of Management and Lack of Standardization
The management of pancreatic fistulas is inherently complex, requiring a multidisciplinary approach that often involves various specialists, including surgeons, gastroenterologists, and interventional radiologists. This coordination of care can be challenging, as each specialist may have different approaches and philosophies regarding treatment. Additionally, the lack of universally accepted guidelines for managing pancreatic fistulas results in significant variations in treatment approaches and outcomes across different healthcare settings. This inconsistency can lead to confusion among healthcare providers and patients alike, further complicating care management. The high morbidity and mortality rates associated with untreated or poorly managed pancreatic fistulas underscore the critical need for standardized treatment protocols. Moreover, while minimally invasive therapies show promise in improving patient outcomes, their limited availability remains a hurdle. Continued development and wider adoption of these techniques are essential to enhance the effectiveness of pancreatic fistula treatment and improve overall patient care.
Market Segmentation Analysis:
By Type:
The pancreatic fistula treatment market can be segmented by type, primarily including drugs and surgical devices. Drug-based treatments encompass various pharmacological agents aimed at managing symptoms and complications associated with pancreatic fistulas, such as somatostatin analogs and other anti-secretory drugs. These drugs play a significant role in reducing pancreatic fluid secretions, which aids in minimizing fistula output and promoting healing. Meanwhile, surgical devices are essential for direct intervention, including drainage and repair procedures for fistula management. Advancements in minimally invasive surgical devices, such as endoscopic techniques, are bolstering the demand within this segment. The increasing preference for non-invasive and minimally invasive treatments is also driving market growth, as these methods aim to reduce hospital stays and recovery time. Overall, both drug and surgical device segments are expected to see steady growth as new therapies and technologies become available, driven by the need for effective and comprehensive solutions to manage complex pancreatic fistulas.
By Application:
Pancreatic fistula treatment is also segmented by application, encompassing hospitals, clinics, ambulatory surgical centers, and other healthcare settings. Hospitals remain the leading segment due to their capacity to handle complex cases requiring multidisciplinary approaches, often involving surgeons, gastroenterologists, and radiologists. Hospitals are equipped with specialized surgical devices and have the infrastructure necessary to manage pancreatic fistulas comprehensively. Clinics are significant contributors to early-stage diagnosis and less severe cases, offering supportive drug therapy and post-operative care. Ambulatory surgical centers are gaining traction due to their role in providing minimally invasive procedures, often at lower costs and with reduced recovery times, appealing to patients seeking faster recovery. Other healthcare settings, including specialty centers, contribute to market growth as they address the increasing demand for specialized pancreatic fistula treatment. The rising prevalence of pancreatic disorders and the demand for accessible and cost-effective treatment solutions are expected to drive growth across these application segments.
Segments:
Based on Type:
- Drugs
- Surgical Devices
Based on Application:
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a prominent position in the pancreatic fistula treatment market, accounting for approximately 35% of the global market share. This dominance is due to advanced healthcare infrastructure, increased healthcare spending, and the high prevalence of pancreatic diseases. The United States drives the region’s share, with substantial contributions from specialized healthcare facilities and a high adoption rate of advanced medical devices. Innovations in minimally invasive procedures and a well-established reimbursement framework further enhance growth in North America. Additionally, high awareness of pancreatic health and complications promotes early diagnosis and effective management, securing North America’s leading market position, which is expected to continue as R&D efforts advance.
Asia-Pacific
The Asia-Pacific region is emerging rapidly in the pancreatic fistula treatment market, currently holding around 25% of the global market share. Key growth drivers include increasing healthcare investments and rising awareness of pancreatic health issues, especially in countries like China and India. A large patient population, coupled with expanding access to healthcare services, supports the rising demand for effective fistula treatments. With improved healthcare infrastructure and government initiatives aimed at broadening healthcare access, Asia-Pacific is poised for significant growth. The region benefits from both public and private investments in advanced treatment facilities, and as healthcare standards and patient awareness improve, the Asia-Pacific market share is expected to grow steadily.
Key Player Analysis
- Becton Dickinson & Company
- Novartis AG
- Olympus Corporation
- Medtronic plc
- Baxter International, Inc.
- Fresenius Kabi AG
- CONMED Corporation
- Ethicon USA, LLC
- Braun Melsungen AG
- Cook Medical, Inc.
Competitive Analysis
The competitive landscape of the pancreatic fistula treatment market is marked by continuous innovation and strategic partnerships among leading players, such as Cook Medical, Inc., CONMED Corporation, Fresenius Kabi AG, B. Braun Melsungen AG, Becton Dickinson & Company, Baxter International, Inc., Ethicon USA, LLC, Medtronic plc, Novartis AG, and Olympus Corporation. These companies focus on advancing minimally invasive surgical solutions and diagnostic tools, aiming to address the complexities of pancreatic fistula management and improve patient outcomes. Product innovation, targeted R&D investments, and a strong emphasis on geographic expansion characterize their strategies, as they seek to capture market share in regions with high demand. Collaborations with healthcare providers and research institutions further support their efforts to develop effective and safer treatment options, aligning with evolving healthcare needs. As a result, competition in this market is intensifying, with an ongoing commitment to technological advancement and enhanced treatment accessibility.
Recent Developments
- In May 2022, CONMED Corporation announced a definitive agreement to acquire privately-held In2Bones Global, Inc. for cash consideration of $145 million at closing and up to an additional $110 million in growth-based earnout payments over a four-year period. In2Bones is a global developer, manufacturer and distributor of medical devices for the treatment of disorders and injuries of the upper (hand, wrist, elbow) and lower (foot and ankle) extremities.
- In March 2022, Fresenius Kabi AG announced the acquisition of a 55% stake in mAbxience Holding S.L. The purchase price would be a combination of €495 million upfront payment and milestone payments. mAbxience is a leading international biopharmaceutical company, focused on the rapidly developing biosimilars market.
- In February 2022, Cook Medical, Inc signed a letter of intent with Cooper Companies to sell the entirety of Cook’s Reproductive Health business within the MedSurg division. Cooper Companies, a publicly held healthcare company, is focused on women’s health and fertility solutions and provides innovative products and services.
Market Concentration & Characteristics
The pancreatic fistula treatment market exhibits a moderate to high level of concentration, with a few leading players holding significant market shares, owing to their strong product portfolios, extensive distribution networks, and continuous innovation in treatment solutions. Dominated by companies such as Cook Medical, CONMED Corporation, and Medtronic plc, the market is characterized by a mix of advanced surgical devices, pharmaceuticals, and minimally invasive technologies aimed at managing pancreatic fistulas effectively. The presence of established players allows for robust R&D activities, especially in the development of new endoscopic procedures and pharmacological therapies. However, barriers to entry remain high due to stringent regulatory requirements, high costs associated with R&D, and the complexity of the condition, which demands specialized solutions. Despite these barriers, the market is witnessing an influx of niche players focusing on innovative, minimally invasive treatments, highlighting a trend towards greater competition and specialized therapeutic options in the years to come.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The pancreatic fistula treatment market is expected to see steady growth due to increasing incidences of pancreatic diseases, especially among the aging population.
- Advancements in minimally invasive surgical techniques will drive the adoption of innovative therapies, enhancing patient outcomes and recovery times.
- Pharmaceutical companies are likely to invest in developing targeted drugs that effectively manage pancreatic fistulas, addressing a significant unmet need.
- Diagnostic improvements, including more accurate imaging and lab tests, will facilitate early detection and improved treatment pathways.
- Growing awareness among healthcare professionals about pancreatic fistula complications will promote timely intervention and standardized treatment protocols.
- Rising healthcare expenditure in emerging economies will expand access to advanced treatment options, driving market growth.
- Companies are expected to focus on expanding their presence in high-growth regions to capitalize on increasing healthcare infrastructure and demand.
- The ongoing push for cost-effective treatment options will encourage innovation in affordable solutions and reimbursement frameworks.
- Research and development activities will continue to focus on safer and less invasive techniques to reduce complications associated with current treatments.
- Despite challenges, the demand for effective pancreatic fistula treatments is expected to grow, supported by an aging population and rising incidence of pancreatic conditions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Incidence of Pancreatitis
The rising prevalence of both acute and chronic pancreatitis, which are major risk factors for pancreatic fistula formation, is driving demand for effective treatment solutions. Lifestyle changes, obesity, and aging populations are contributing to higher rates of pancreatitis globally.
Advancements in Surgical Procedures
Innovations in minimally invasive and robotic surgical techniques are improving patient outcomes and reducing complications, making pancreatic fistula treatments safer and more effective. These advancements are expanding the adoption of surgical interventions for complex pancreatic conditions.
Aging Population and Unmet Medical Needs
The growing elderly population is more susceptible to pancreatic diseases and complications like fistulas, increasing the need for tailored and effective treatments. Persistent gaps in minimally invasive and efficient therapies are spurring ongoing research and product development.
Growing Awareness and Technological Advancements
Enhanced awareness among healthcare providers and patients, coupled with improved diagnostic tools such as advanced imaging and endoscopic techniques, is leading to earlier detection and more precise management of pancreatic fistulas, supporting market growth.
Healthcare Infrastructure Expansion in Emerging Markets
Rising healthcare investments and improved access to advanced medical facilities in regions like Asia Pacific and Latin America are enabling more patients to receive timely and effective pancreatic fistula treatments, further fueling market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Pancreatic Fistula Treatment Market?
What factors are driving the growth of the Pancreatic Fistula Treatment market?
What are the key segments within the Pancreatic Fistula Treatment market?
What are some challenges faced by the Pancreatic Fistula Treatment market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Drugs
- 1.2.2 Surgical Devices
- 1.3 By Application
- 1.3.1 Hospitals
- 1.3.2 Clinics
- 1.3.3 Ambulatory Surgical Centers
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,495 million → 2032: USD 3,829.04 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pancreatic Fistula Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pancreatic Fistula Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pancreatic Fistula Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pancreatic Fistula Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pancreatic Fistula Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pancreatic Fistula Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pancreatic Fistula Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pancreatic Fistula Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,495 million → 2032: USD 3,829.04 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pancreatic Fistula Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drugs
- 12.3.7.2 Surgical Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Clinics
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pancreatic Fistula Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Pancreatic Fistula Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Pancreatic Fistula Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Pancreatic Fistula Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Becton Dickinson & Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic plc
- 18.4 Novartis AG
- 18.5 Olympus Corporation
- 18.6 Baxter International, Inc.
- 18.7 Fresenius Kabi AG
- 18.8 CONMED Corporation
- 18.9 Ethicon USA, LLC
- 18.10 Braun Melsungen AG
- 18.11 Cook Medical, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

