
Mobile Peer-To-Peer (P2P) Money Transfer Market Overview:
The Mobile Peer-To-Peer (P2P) Money Transfer market size was valued at USD 1,230.00 million in 2018, grew to USD 2,216.11 million in 2024, and is anticipated to reach USD 8,529.20 million by 2032, at a CAGR of 18.51% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobile Peer-To-Peer (P2P) Money Transfer Market Size 2024 | USD 2,216.11 Million |
| Mobile Peer-To-Peer (P2P) Money Transfer Market, CAGR | 18.51% |
| Mobile Peer-To-Peer (P2P) Money Transfer Market Size 2032 | USD 8,529.20 Million |
The Mobile Peer-To-Peer (P2P) Money Transfer market is led by key players including PayPal (Venmo), Block, Inc. (Cash App), Zelle, Google Pay, Apple Pay, Alipay, WeChat Pay, Wise, and Revolut. These companies dominate through strong digital ecosystems, seamless user interfaces, and expanding global footprints. PayPal, Cash App, and Zelle hold major influence in North America, while Alipay and WeChat Pay lead in Asia Pacific. Wise and Revolut are prominent in cross-border payments, especially in Europe. In 2024, North America accounted for 35.8% of the global market share, followed by Asia Pacific at 30.0%, driven by mobile-first users and advanced fintech platforms. Strategic partnerships, user trust, and integration across banking and e-commerce ecosystems reinforce leadership positions.

Mobile Peer-To-Peer (P2P) Money Transfer Market Insights
- The market grew from USD 1,230.00 million in 2018 to USD 2,216.11 million in 2024 and will reach USD 8,529.20 million by 2032, at 18.51% CAGR.
- Strong growth comes from rising smartphone use, cashless payments, and financial inclusion programs. Users prefer fast, low-cost mobile transfers for daily needs. Remote payment drives adoption due to app-based convenience and wide acceptance. This segment holds over 70% share, supported by wallets and bank apps.
- Key trends include super-app integration, QR-based payments, and cross-border P2P transfers. Platforms embed payments into retail, travel, and mobility services. Retail remains the largest application segment, holding over 45% share due to mobile commerce growth.
- Competition is intense, led by global and regional fintech platforms. Firms compete on user experience, security, rewards, and ecosystem partnerships. Continuous innovation in fraud control and instant settlement strengthens positioning.
- Regionally, North America leads with 35.8% share, followed by Asia Pacific at 30.0% and Europe at 21.5%. Asia Pacific shows the fastest growth, driven by mobile-first economies.
Mobile Peer-To-Peer (P2P) Money Transfer Market Segmentation Analysis:
By Type
Remote payment dominates the Mobile Peer-To-Peer (P2P) Money Transfer market, accounting for over 70% of the revenue share in 2024. This segment's growth is driven by the widespread use of mobile banking apps, wallets, and QR-based payment platforms. Consumers prefer remote options for utility payments, online shopping, and bill splitting due to their speed and convenience. The rise in internet penetration and mobile-first financial ecosystems across emerging markets has accelerated remote payment adoption. Proximity payment is steadily growing, supported by near-field communication (NFC), Bluetooth, and QR code technology. This segment is gaining traction in urban areas for in-store purchases, event transactions, and micro-retail settlements. Younger demographics, especially Gen Z and millennials, favor contactless methods for daily purchases. Retailers and transport providers are deploying mobile POS systems, encouraging instant P2P settlements. Enhanced security features and tap-to-pay capabilities further increase adoption at physical touchpoints.
- For instance, Zelle connected 151 million consumer and small business accounts in 2024, enabling near-instant transfers linked to bank apps.
By Application
The retail segment leads the Mobile Peer-To-Peer (P2P) Money Transfer market, capturing more than 45% of the revenue share in 2024. Growing mobile commerce, buy-now-pay-later services, and in-app payment integration fuel this dominance. Both small merchants and large chains now accept mobile P2P payments to cut processing costs and serve cashless consumers. Loyalty program integration and instant cashback features also strengthen this payment method's retail appeal. The shift toward mobile-first shopping experiences across platforms continues to support this trend. The travel and hospitality segment shows strong adoption, driven by on-the-go payment needs and contactless service models. Tour operators, booking apps, and hotels increasingly support mobile P2P for transactions like reservations, tipping, and peer-split travel expenses. Drivers, logistics partners, and customers prefer real-time fund transfers via mobile apps for convenience and transparency.
- For instance, Square’s platform served 4 million active sellers worldwide through its POS systems that support mobile payment acceptance.
Mobile Peer-To-Peer (P2P) Money Transfer Market Key Growth Drivers
Rapid Smartphone and Mobile Internet Penetration
Rising smartphone adoption remains a core growth driver for the Mobile Peer-To-Peer (P2P) Money Transfer market. Affordable devices and low-cost data plans expand access to mobile payment apps. Users increasingly rely on smartphones for daily financial tasks. Mobile-first users prefer instant transfers over cash or bank visits. This shift is strong in emerging economies with young populations. Digital wallets and banking apps come pre-installed on many devices. Easy onboarding and simple interfaces lower adoption barriers. Social media and messaging app integration also boosts usage. Peer payments now align with daily communication habits. This environment supports frequent, low-value transactions. As smartphone reach expands, the addressable user base continues to grow. The result is sustained volume growth across personal and micro-merchant transactions.
- For instance, Google Pay crossed 150 million active users in India and supports billions of transactions annually through smartphones integrated with UPI-enabled devices.
Shift Toward Cashless and Contactless Payments
Governments and financial institutions promote cashless ecosystems worldwide. Policy support accelerates digital payment acceptance across sectors. Consumers value speed, safety, and traceability over cash handling. The Mobile Peer-To-Peer (P2P) Money Transfer market benefits from this behavioral change. Pandemic-era habits normalized contactless transactions. Merchants now encourage mobile payments for cost efficiency. Urban transport, retail, and services increasingly accept P2P payments. Reduced reliance on physical infrastructure improves scalability. Digital receipts and instant confirmation build trust. Users gain better expense tracking and budgeting control. These advantages strengthen repeat usage. Cashless initiatives also support financial inclusion goals. This transition continues to drive long-term market expansion.
- For instance, Visa reported 212.6 billion payment transactions processed globally in 2023 an 11% increase over the previous year reflecting strong growth in contactless and mobile-based transfers across retail and services.
Financial Inclusion and Fintech Ecosystem Expansion
Financial inclusion initiatives strongly support P2P money transfer adoption. Millions of users remain underbanked or unbanked globally. Mobile P2P platforms provide basic financial access without traditional accounts. Simple KYC processes enable faster onboarding. Fintech firms partner with telecom operators to reach remote users. Agent networks support cash-in and cash-out services. This model builds trust in underserved regions. The Mobile Peer-To-Peer (P2P) Money Transfer market gains volume from everyday use cases. Peer remittances, bill sharing, and micro-payments drive activity. Governments use mobile transfers for subsidies and welfare payouts. These programs increase user familiarity. Over time, users adopt broader digital financial services.
Mobile Peer-To-Peer (P2P) Money Transfer Market Key Trend & Opportunities
Integration with Super Apps and Digital Ecosystems
Super apps reshape payment behavior by combining multiple services. Payments integrate with shopping, mobility, and social platforms. The Mobile Peer-To-Peer (P2P) Money Transfer market benefits from embedded usage. Users send money without switching applications. This convenience increases transaction frequency. Platforms gain access to behavioral data for personalization. Loyalty rewards and in-app credits encourage retention. Ecosystem integration reduces customer acquisition costs. Merchants benefit from seamless checkout experiences. This trend creates opportunities for cross-selling financial products. Credit, insurance, and savings tools follow payment adoption. Strong ecosystem lock-in supports long-term revenue growth.
- For instance, WeChat Pay supports over 1 billion monthly active users and enables P2P transfers directly inside chat, shopping, and service mini-
Growth of Cross-Border and Remittance Use Cases
Cross-border P2P transfers represent a growing opportunity. Migrant workers seek faster and cheaper remittance options. Mobile platforms reduce transfer time and fees. Currency conversion tools improve transparency. The Mobile Peer-To-Peer (P2P) Money Transfer market expands beyond domestic use. Regional payment corridors gain traction. Partnerships with banks and FX providers enhance reach. Compliance improvements build user confidence. Small-value international transfers grow rapidly. Digital identity verification supports global scalability. This trend positions P2P platforms as alternatives to traditional remittance channels.
Mobile Peer-To-Peer (P2P) Money Transfer Market Key Challenges
Data Security, Fraud, and Privacy Concerns
Security risks remain a major challenge for P2P platforms. Rising transaction volumes attract fraud attempts. Phishing, account takeovers, and social engineering cause losses. Users expect strong protection for personal data. Any breach damages platform trust quickly. The Mobile Peer-To-Peer (P2P) Money Transfer market faces strict compliance needs. Regulatory scrutiny increases operating complexity. Platforms must invest heavily in encryption and monitoring tools. Balancing security with user convenience is difficult. Multi-factor authentication can slow transactions. Educating users adds operational cost. Failure to manage risk impacts adoption and retention.
Regulatory Fragmentation and Compliance Complexity
Regulatory frameworks vary widely across regions. Licensing, KYC, and AML rules differ by market. This fragmentation limits rapid geographic expansion. The Mobile Peer-To-Peer (P2P) Money Transfer market must adapt locally. Compliance increases operational costs for providers. Smaller players face entry barriers. Frequent policy changes create uncertainty. Cross-border services face added scrutiny. Delays in approvals slow product launches. Platforms must balance innovation with regulation. Managing compliance across multiple jurisdictions remains a persistent challenge.

Mobile Peer-To-Peer (P2P) Money Transfer Market Regional Analysis
North America
North America held the largest share of the Mobile Peer-To-Peer (P2P) Money Transfer market in 2024, accounting for 35.8% of global revenue. The market grew from USD 445.26 million in 2018 to USD 792.47 million in 2024, and is projected to reach USD 3,045.79 million by 2032, expanding at a CAGR of 18.5%. Growth is driven by widespread smartphone penetration, high digital banking adoption, and strong fintech presence. The U.S. and Canada dominate the regional landscape with advanced regulatory support and mature consumer behavior favoring instant and secure mobile transactions.
Asia Pacific
Asia Pacific is the fastest-growing region in the Mobile Peer-To-Peer (P2P) Money Transfer market, expanding at a CAGR of 19.8%. The market rose from USD 355.47 million in 2018 to USD 664.49 million in 2024, and is expected to reach USD 2,783.08 million by 2032, securing a 30.0% global share. Rapid urbanization, mobile-first financial ecosystems, and strong governmental digitalization programs across China, India, and Southeast Asia fuel this momentum. Peer payment adoption is high among youth and small businesses, with platforms like Alipay, Paytm, and GCash leading the region’s transformation.
Europe
Europe accounted for 21.5% of the global Mobile Peer-To-Peer (P2P) Money Transfer market in 2024. The market expanded from USD 276.75 million in 2018 to USD 475.96 million in 2024, and is forecast to reach USD 1,712.26 million by 2032, growing at a CAGR of 17.5%. Strong regulatory backing for open banking and PSD2 compliance enables secure and seamless mobile payments. The region’s mature digital infrastructure and emphasis on data privacy enhance user confidence. Countries like the UK, Germany, and the Nordics lead adoption, driven by e-wallet growth and increasing contactless habits.
Latin America
Latin America contributed 6.2% to the global Mobile Peer-To-Peer (P2P) Money Transfer market in 2024. The market value grew from USD 76.26 million in 2018 to USD 136.05 million in 2024, with projections reaching USD 485.06 million by 2032 at a CAGR of 17.4%. Growing mobile connectivity, rising remittance needs, and a large underbanked population support strong regional uptake. Fintech startups in Brazil, Mexico, and Colombia offer P2P platforms that bypass traditional banking. Government-led financial inclusion programs also enhance mobile money access across urban and rural areas.
Middle East
The Middle East captured 3.2% of the Mobile Peer-To-Peer (P2P) Money Transfer market in 2024. Valued at USD 41.82 million in 2018, the market reached USD 70.01 million in 2024 and is expected to hit USD 239.72 million by 2032, growing at a CAGR of 16.8%. GCC countries, particularly the UAE and Saudi Arabia, lead adoption through digital-first banking, expat remittance demand, and government-backed fintech strategies. Mobile wallet usage is rising in everyday transactions, aided by QR-based payments, local payment apps, and smart city initiatives.
Africa
Africa held 3.5% of the global Mobile Peer-To-Peer (P2P) Money Transfer market in 2024, with notable growth from USD 34.44 million in 2018 to USD 77.13 million in 2024. The market is forecast to reach USD 263.29 million by 2032, growing at a CAGR of 16.4%. Mobile money services like M-Pesa drive financial inclusion across Kenya, Nigeria, and Ghana. The region’s low banking penetration and high mobile ownership create fertile ground for P2P solutions. Telecom-backed platforms enable easy cash transfers even in remote areas, supporting rural connectivity and digital economic activity.
Mobile Peer-To-Peer (P2P) Money Transfer Market Segmentations:
By Type
- Remote Payment
- Proximity Payment
By Application
- Retail
- Travel and Hospitality
- Transportation and Logistics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Mobile Peer-To-Peer (P2P) Money Transfer Market Competitive Landscape
The Mobile Peer-To-Peer (P2P) Money Transfer market is highly competitive, led by major fintech and tech-driven payment platforms. Companies such as PayPal (Venmo), Block, Inc. (Cash App), and Zelle dominate the U.S. market, offering seamless integrations with bank accounts and mobile interfaces. Google Pay, Apple Pay, and Samsung Pay drive competition through device-level integration and ecosystem lock-in. In Asia, Alipay and WeChat Pay lead the market with advanced QR and super-app-based services. European players like Revolut and Wise focus on cross-border and low-fee transfers. Competitors prioritize user acquisition through cashback, real-time transactions, and security upgrades. Partnerships with banks, telecom operators, and merchants fuel expansion across regions. Innovation in biometric verification, AI-driven fraud detection, and blockchain-backed transfer rails supports ongoing differentiation. As digital wallets converge with lifestyle apps, firms compete not only on transaction speed and cost but also on user experience and ecosystem strength.
Key Player Analysis
- PayPal (Venmo)
- Block, Inc. (Cash App)
- Zelle
- Google Pay
- Apple Pay
- Samsung Pay
- Alipay
- WeChat Pay (Tencent)
- Wise (formerly TransferWise)
- Revolut
Recent Developments
- In May 2025, X in partnership with visa announced to launch a payment feature that is embedded in the social media platform called X Money. The payments feature is designed allow peer-to-peer (P2P) payments using a debit card and instantly transfer funds to its bank account.
- In January 2025, Meta owned WhatsApp made its P2P feature available for all Indian users.
- In 2025, Samsung Electronics America unveiled Samsung Wallet's new Tap to Transfer feature designed to make peer-to-peer (P2P) payments quick.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Mobile P2P platforms will see sustained growth from rising digital payment adoption.
- Smartphone penetration will continue expanding the active user base globally.
- Remote payment usage will remain dominant due to app-based convenience.
- Retail and everyday consumer payments will drive transaction volume growth.
- Cross-border P2P transfers will gain importance for remittances and travel use.
- Super-app integration will increase transaction frequency and user engagement.
- Security upgrades will focus on fraud prevention and data protection.
- Partnerships with banks, merchants, and telecom operators will expand reach.
- Emerging markets will record faster adoption due to financial inclusion efforts.
- Regulatory clarity will support long-term stability and market maturity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mobile P2P Money Transfer market?
What factors are driving the growth of the Mobile P2P Money Transfer market?
What are the key segments within the Mobile P2P Money Transfer market?
What are some challenges faced by the Mobile P2P Money Transfer market?
Who are the major players in the Mobile P2P Money Transfer market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mobile Peer-To-Peer (P2P) Money Transfer Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mobile Peer-To-Peer (P2P) Money Transfer Market Snapshot
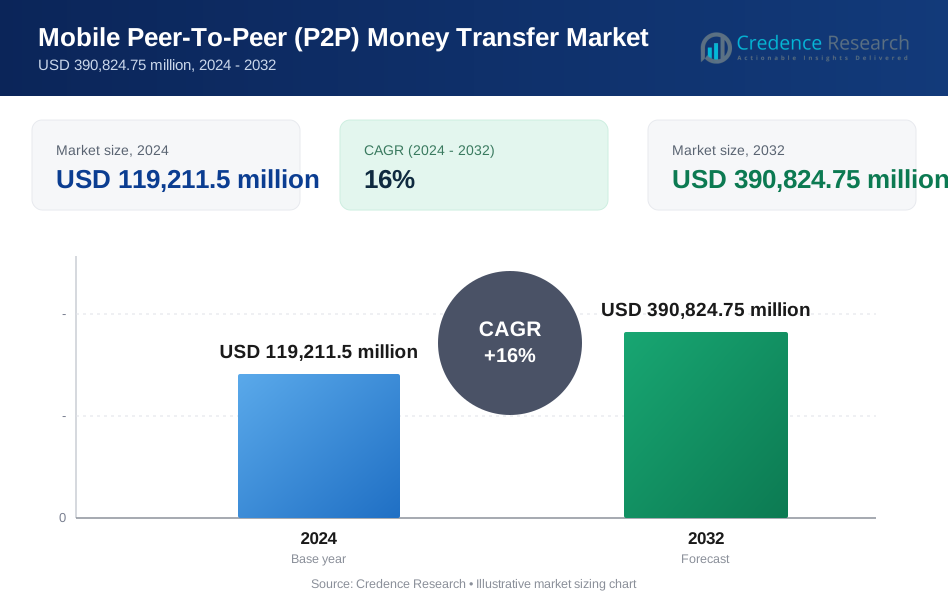
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 119,211.5 million → 2032: USD 390,824.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mobile Peer-To-Peer (P2P) Money Transfer Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mobile Peer-To-Peer (P2P) Money Transfer Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mobile Peer-To-Peer (P2P) Money Transfer Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mobile Peer-To-Peer (P2P) Money Transfer Market Drivers
- 3.3 Mobile Peer-To-Peer (P2P) Money Transfer Market Restraints & Challenges
- 3.4 Mobile Peer-To-Peer (P2P) Money Transfer Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mobile Peer-To-Peer (P2P) Money Transfer Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mobile Peer-To-Peer (P2P) Money Transfer Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mobile Peer-To-Peer (P2P) Money Transfer category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mobile Peer-To-Peer (P2P) Money Transfer Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mobile Peer-To-Peer (P2P) Money Transfer Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mobile Peer-To-Peer (P2P) Money Transfer market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mobile Peer-To-Peer (P2P) Money Transfer Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mobile Peer-To-Peer (P2P) Money Transfer Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mobile Peer-To-Peer (P2P) Money Transfer Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mobile Peer-To-Peer (P2P) Money Transfer (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mobile Peer-To-Peer (P2P) Money Transfer Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mobile Peer-To-Peer (P2P) Money Transfer Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mobile Peer-To-Peer (P2P) Money Transfer Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mobile Peer-To-Peer (P2P) Money Transfer Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mobile Peer-To-Peer (P2P) Money Transfer Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mobile Peer-To-Peer (P2P) Money Transfer Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mobile Peer-To-Peer (P2P) Money Transfer Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mobile Peer-To-Peer (P2P) Money Transfer Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mobile Peer-To-Peer (P2P) Money Transfer Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
