
Market Overview
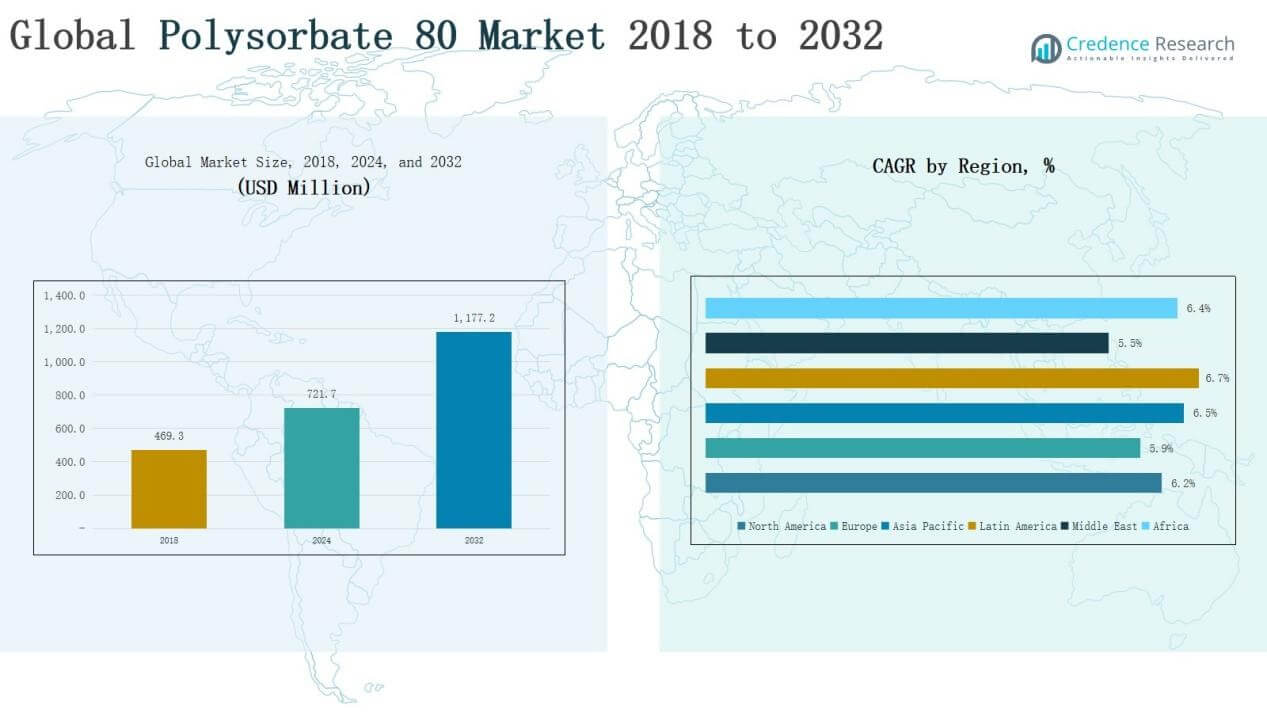
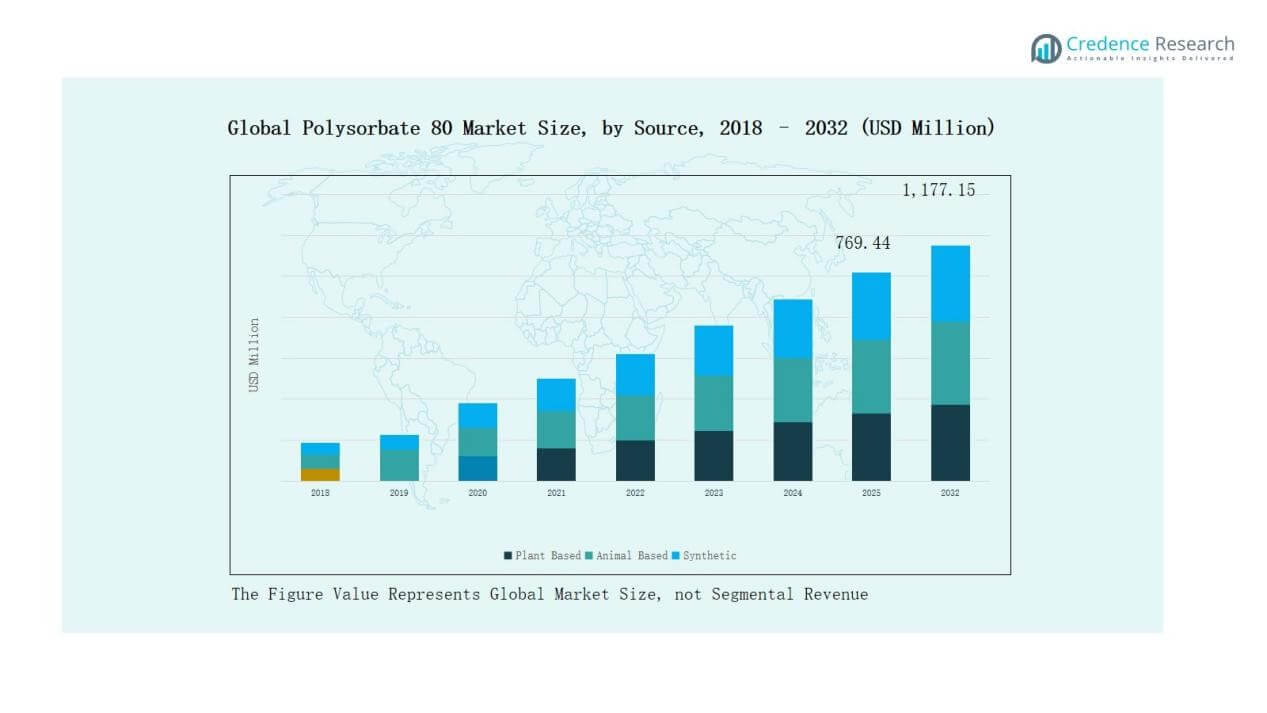
Global Polysorbate 80 Market size was valued at USD 469.3 million in 2018 to USD 721.7 million in 2024 and is anticipated to reach USD 1,177.2 million by 2032, at a CAGR of 6.26% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polysorbate 80 Market Size 2024 | USD 721.7 Million |
| Polysorbate 80 Market, CAGR | 6.26% |
| Polysorbate 80 Market Size 2032 | USD 1,177.2 Million |
The Global Polysorbate 80 Market is shaped by the presence of leading companies such as Lonza Group Limited, BASF Corporation, Croda International plc, Solenis, Avril Group, Reachin Chemical Co., Ltd., Lotion Crafter LLC, ERACHEM Comilog, Inc., and Compania Minera Aultan. These players compete through extensive product portfolios, strong distribution networks, and continuous innovation in plant-based and sustainable formulations to meet rising clean-label demand. Strategic initiatives such as mergers, acquisitions, and regional expansions further strengthen their market position. Geographically, Asia Pacific emerged as the leading region in 2024 with a 6.5% share, supported by large-scale pharmaceutical production, rising cosmetics consumption, and expanding food and beverage industries.
Market Insights
- The Global Polysorbate 80 Market grew from USD 469.3 million in 2018 to USD 721.7 million in 2024, and is projected to reach USD 1,177.2 million by 2032.
- Plant-based sources dominated with a 52% share in 2024, driven by rising demand for sustainable, natural, and safer formulations across pharmaceuticals, food, and cosmetics.
- The emulsifier functionality led with 41% share, supported by its extensive use in stabilizing bakery, dairy, and beverage products across global food and beverage industries.
- Pharmaceuticals emerged as the top application segment with 37% share, fueled by polysorbate 80’s critical role in biologics, vaccines, and injectable formulations.
- Asia Pacific led the market with a 6.5% share in 2024, supported by large-scale pharmaceutical manufacturing, rising cosmetics demand, and expanding processed food consumption.
Market Segment Insights
By Source
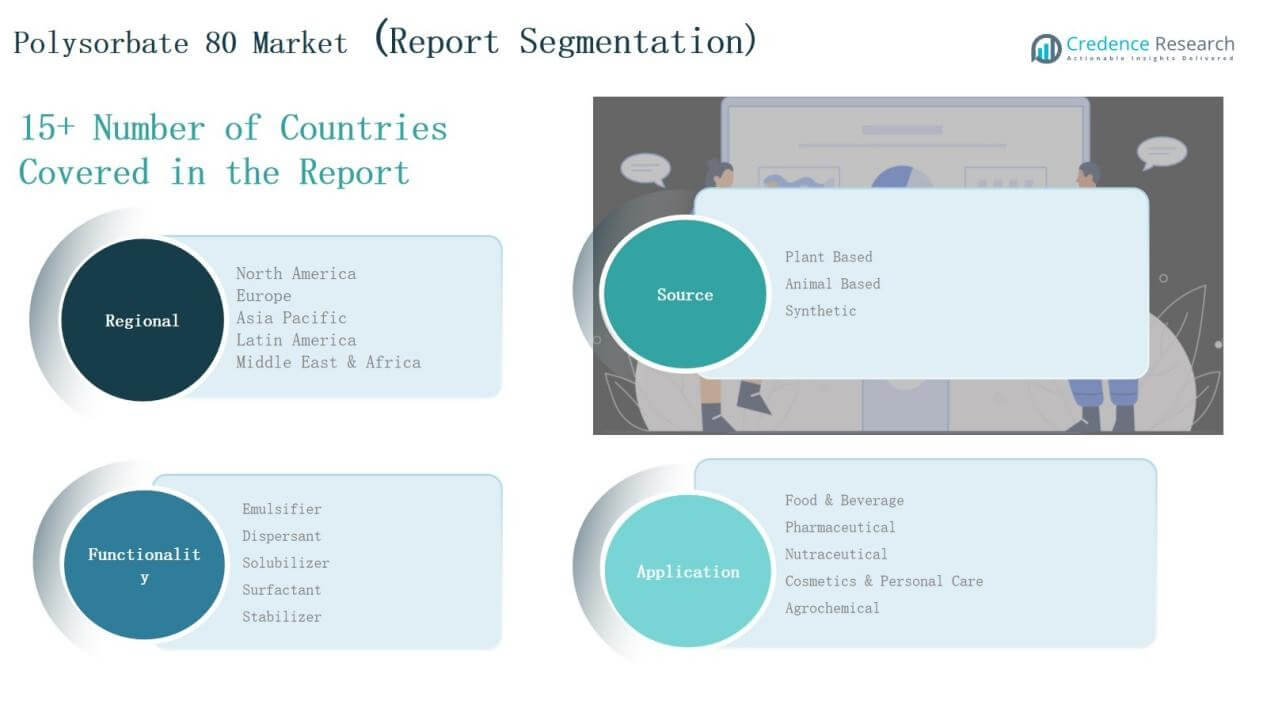
Plant-based polysorbate 80 dominated the market in 2024 with a 52% share, driven by rising demand for sustainable and natural ingredients in food, pharmaceuticals, and cosmetics. Consumers prefer plant-derived emulsifiers due to perceived safety and lower allergenic risks compared to animal-based sources. Animal-based polysorbate 80, holding 28% share, remains relevant in regions with established traditional processing, though it faces declining adoption amid ethical and regulatory concerns. Synthetic variants accounted for the remaining 20%, supported by cost efficiency and scalability in industrial applications, but they continue to face scrutiny due to increasing clean-label trends.
- For instance, Croda International launched its ECO Tween™ range in 2020, offering 100% bio-based polysorbates made from renewable plant feedstocks.
By Functionality
The emulsifier segment led the functionality category with a 41% share in 2024, reflecting polysorbate 80’s widespread use in stabilizing food and beverage formulations. Strong demand from bakery, dairy, and beverage industries underpins this dominance. The solubilizer function held 23% share, favored in pharmaceuticals and nutraceuticals to enhance bioavailability of active compounds. Surfactants contributed 15%, widely applied in cosmetics and personal care for effective cleansing and formulation stability. Dispersants and stabilizers captured 12% and 9% shares respectively, used in agrochemical suspensions and long-shelf-life formulations, ensuring broader but niche growth prospects.
- For insatcne, Mondelez International, a major chocolate and confectionery producer, uses other emulsifiers, such as polyglycerol polyricinoleate (PGPR) and lecithin, in its chocolate to maintain texture, reduce viscosity, and prevent fat bloom.
By Application
The pharmaceutical sector emerged as the leading application segment, capturing 37% share in 2024, driven by polysorbate 80’s critical role in injectable formulations, vaccines, and biologics. Food and beverage followed with 28% share, supported by its use as an emulsifier in processed foods, beverages, and confectionery. Cosmetics and personal care products held 19% share, leveraging polysorbate 80’s solubilizing and stabilizing properties in creams, lotions, and cleansers. Nutraceutical applications accounted for 10% share, boosted by growing demand for supplements with enhanced bioavailability. Agrochemicals represented 6% share, benefiting from polysorbate 80’s dispersing functions in pesticide and herbicide formulations.
Market Overview
Key Growth Drivers
Rising Pharmaceutical Demand
The pharmaceutical industry strongly drives polysorbate 80 demand, particularly in injectable formulations, biologics, and vaccines. Its role as a solubilizer and stabilizer makes it essential for enhancing drug delivery and maintaining product stability. Growing investments in biologics and monoclonal antibody therapies amplify its importance. The increasing prevalence of chronic diseases and rising vaccine demand globally further solidify polysorbate 80 as a critical excipient. Pharmaceutical firms increasingly depend on this emulsifier to meet regulatory standards and deliver effective, safe, and stable formulations.
- For instance, Amgen incorporates polysorbate 80 in formulations of biologics such as darbepoetin alfa (Aranesp®) and epoetin alfa (Epogen®, Procrit®), critical in treating anemia in cancer patients, enhancing stability and preventing protein aggregation.
Expansion in Food and Beverage Applications
Food and beverage manufacturers are increasingly adopting polysorbate 80 to improve product texture, stability, and shelf life. With consumer demand for processed and convenience foods rising, the need for reliable emulsifiers has expanded significantly. Its use in bakery, dairy, confectionery, and beverage applications ensures consistent product quality. Additionally, clean-label and natural product preferences boost demand for plant-based polysorbate 80. Global urbanization, lifestyle changes, and growing packaged food consumption continue to drive the segment, making polysorbate 80 integral to food innovation and formulation.
- For instance, in ice cream production, companies use polysorbate 80 at concentrations up to 0.5% to prevent ice crystal formation, resulting in a smoother texture and increased resistance to melting.
Growth in Cosmetics and Personal Care Industry
The cosmetics and personal care industry presents strong demand for polysorbate 80 as a solubilizer and surfactant. It enhances the formulation of creams, lotions, shampoos, and cleansers by improving texture, consistency, and stability. The rising consumer focus on skincare and grooming, especially in Asia-Pacific and Europe, supports the growth trajectory. Natural and plant-based variants are gaining traction among eco-conscious buyers, aligning with the shift toward sustainable personal care products. The rapid expansion of e-commerce channels further accelerates market penetration, increasing its global adoption across beauty and hygiene products.
Key Trends & Opportunities
Shift Toward Plant-Based and Sustainable Sources
One of the most notable trends is the growing preference for plant-based polysorbate 80, supported by clean-label initiatives and environmental sustainability goals. Consumers increasingly view plant-derived ingredients as safer and more ethical compared to animal-based sources. This trend opens opportunities for producers to innovate with natural alternatives that meet regulatory and consumer expectations. Companies adopting green chemistry processes and sustainable sourcing strategies are likely to gain a competitive advantage, as industries such as food, cosmetics, and nutraceuticals embrace environmentally conscious solutions.
- For instance, Vasudha Chemicals supplies high-quality, plant-derived polysorbate 80 meeting global safety standards such as FDA and EFSA, emphasizing sustainable sourcing for pharmaceuticals and cosmetics.
Rising Adoption in Biologics and Advanced Therapeutics
The global boom in biologics, monoclonal antibodies, and gene therapies provides new opportunities for polysorbate 80 in pharmaceutical applications. Its ability to stabilize complex molecules ensures longer shelf life and improved patient safety. As healthcare systems invest in advanced therapeutics, demand for high-purity excipients like polysorbate 80 grows. Expanding clinical trials and regulatory approvals further widen its scope. This trend positions polysorbate 80 as a strategic enabler of innovation in the pharmaceutical landscape, fueling steady growth in the long term.
- For instance, Sanofi-Aventis uses polysorbate 80 in its docetaxel injection (Taxotere®) to solubilize this chemotherapeutic agent, enhancing its stability and efficacy in cancer treatment.
Key Challenges
Regulatory Scrutiny and Safety Concerns
Polysorbate 80 faces growing regulatory scrutiny due to safety concerns associated with synthetic or animal-derived sources. Agencies in North America and Europe enforce strict compliance for pharmaceutical and food-grade use. Studies highlighting potential allergic reactions or toxicity risks create challenges for manufacturers. Meeting stringent safety and purity standards raises production costs and requires continuous monitoring. Regulatory delays or restrictions can affect product availability and market expansion, forcing companies to invest in compliance frameworks while balancing cost-effectiveness.
Price Volatility of Raw Materials
The production of polysorbate 80 depends on raw materials like sorbitol and oleic acid, which are subject to price fluctuations. Agricultural supply variations, geopolitical tensions, and energy costs directly influence availability and pricing. Manufacturers often face margin pressures due to rising input costs, making it challenging to sustain competitive pricing. Smaller producers are more vulnerable, as they have limited capacity to hedge against volatility. Long-term contracts and diversification of raw material sources are required to mitigate these cost-related challenges.
Competition from Alternative Ingredients
Alternative emulsifiers and solubilizers, including lecithin, mono- and diglycerides, and other bio-based surfactants, pose a competitive threat. These substitutes appeal to industries seeking clean-label, allergen-free, and cost-effective options. Continuous innovation in bio-based excipients may reduce dependency on polysorbate 80 in certain applications. Food, pharmaceutical, and cosmetic companies experimenting with alternative formulations create pressure on market share. To maintain relevance, polysorbate 80 suppliers must emphasize product performance, develop plant-based innovations, and differentiate through quality and regulatory compliance.
Regional Analysis
North America
North America held a 6.2% share of the global polysorbate 80 market in 2024, generating revenues of USD 197.21 million. Growth in this region is driven by the strong pharmaceutical industry, particularly the U.S., where polysorbate 80 is widely used in biologics, vaccines, and injectable formulations. Increasing demand from the food and beverage sector, supported by innovation in processed foods, also strengthens its presence. By 2032, revenues are projected to reach USD 320.19 million, with steady adoption across pharmaceuticals and nutraceuticals ensuring long-term growth.
Europe
Europe accounted for a 5.9% share in 2024, with revenues of USD 156.45 million. The market benefits from stringent regulatory frameworks that emphasize high-quality excipients in pharmaceuticals and clean-label ingredients in food and cosmetics. Countries such as Germany, France, and the UK remain major demand centers due to advanced healthcare systems and rising cosmetics consumption. By 2032, the European market is expected to generate USD 248.38 million, driven by growing biologics development, sustainable sourcing initiatives, and increasing consumer preference for natural-based ingredients.
Asia Pacific
Asia Pacific led the global polysorbate 80 market with a 6.5% share in 2024, valued at USD 254.45 million. Strong growth is driven by large-scale pharmaceutical production in China and India, coupled with rising cosmetics and personal care consumption across Southeast Asia, Japan, and South Korea. Expanding processed food demand also supports steady adoption. The region is projected to reach USD 422.48 million by 2032, maintaining its leadership position due to its cost-effective manufacturing base and rapidly growing end-use industries.
Latin America
Latin America represented a 6.7% share of the global market in 2024, generating revenues of USD 65.98 million. Brazil and Mexico are key contributors, driven by rising healthcare spending, growing pharmaceutical production, and expanding food processing industries. The cosmetics sector also plays a notable role, with increasing demand for affordable personal care solutions. By 2032, the regional market is forecasted to reach USD 111.24 million, supported by urbanization, rising disposable incomes, and investments in localized pharmaceutical and food manufacturing capabilities.
Middle East
The Middle East accounted for a 5.5% share in 2024, valued at USD 33.08 million. Growth is supported by increasing pharmaceutical imports, the expansion of local drug manufacturing, and demand for processed foods. GCC countries, particularly Saudi Arabia and the UAE, lead adoption due to their focus on healthcare modernization and food diversification. By 2032, revenues are projected to rise to USD 50.85 million, with opportunities emerging in cosmetics and personal care as consumer spending on premium beauty products grows across the region.
Africa
Africa captured a 6.4% share of the market in 2024, with revenues of USD 14.56 million. South Africa, Egypt, and Nigeria are the leading markets, driven by growing pharmaceutical demand and the expansion of consumer goods industries. Rising urbanization and an increasing population contribute to greater processed food consumption, fueling polysorbate 80 adoption. By 2032, the region is expected to achieve USD 24.01 million in revenues, supported by gradual healthcare improvements, expansion in nutraceuticals, and greater accessibility to global cosmetic and personal care brands.
Market Segmentations:
By Source
- Plant Based
- Animal Based
- Synthetic
By Functionality
- Emulsifier
- Dispersant
- Solubilizer
- Surfactant
- Stabilizer
By Application
- Food & Beverage
- Pharmaceutical
- Nutraceutical
- Cosmetics & Personal Care
- Agrochemical
By Region
North America
- U.S.
- Canada
- Mexico
Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
Latin America
- Brazil
- Argentina
- Rest of Latin America
Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The global polysorbate 80 market is moderately consolidated, with competition driven by established multinational corporations and regional players focusing on cost efficiency and innovation. Leading companies such as Lonza Group Limited, BASF Corporation, Croda International plc, Avril Group, and Solenis dominate through extensive product portfolios and strong global distribution networks. These players emphasize compliance with stringent regulatory standards, particularly for pharmaceutical and food-grade applications, which strengthens their competitive positioning. Strategic initiatives such as mergers, acquisitions, and partnerships are common, enabling firms to expand manufacturing capacities and penetrate high-growth regions, particularly Asia Pacific and Latin America. Smaller firms, including Reachin Chemical Co., Ltd. and Lotion Crafter LLC, compete by offering specialized solutions and flexible pricing to cater to niche applications in cosmetics and personal care. Continuous investment in plant-based sourcing, clean-label formulations, and sustainable manufacturing practices is emerging as a key differentiator, aligning with evolving consumer and industry preferences.
Key Players
- Lonza Group Limited
- Avril Group
- BASF Corporation
- Solenis
- Reachin Chemical Co., Ltd.
- Croda International plc
- Lotion Crafter LLC
- ERACHEM Comilog, Inc.
- Compania Minera Aultan
- A.B. De C.V.
- Other Key Players
Recent Developments
- In January 2024, Croda International launched a line of super-refined Polysorbate 80 and 20 variants aimed at biologics and gene therapies, offering ultra-low residual aldehydes and improved stability.
- In October 2024, Clariant launched its VitiPure Superior line including VitiPure O 80 Superior (Polysorbate 80) designed for colorless, ultra‑pure, parenteral formulations such as vaccines and biologics.
Report Coverage
The research report offers an in-depth analysis based on Source, Functionality, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand from pharmaceutical applications will continue to expand with rising biologics production.
- Food and beverage manufacturers will adopt plant-based variants to meet clean-label demand.
- Cosmetics and personal care products will drive growth with wider use in solubilizers.
- Asia Pacific will strengthen its position as the leading regional market.
- Europe will focus on sustainable sourcing and regulatory compliance in excipient use.
- North America will maintain steady growth through vaccine and injectable formulation demand.
- Latin America will benefit from urbanization and rising processed food consumption.
- Africa and the Middle East will gradually emerge as new growth frontiers.
- Companies will invest in innovation around bio-based and eco-friendly formulations.
- Strategic partnerships and acquisitions will shape competitive dynamics across key industries.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Biologics and Injectable Pharmaceuticals
Polysorbate 80 is a critical excipient in biologics, vaccines, and injectable drug formulations due to its solubilizing and stabilizing properties. The rapid growth of biologics and advanced therapeutics globally is driving increased demand for high-purity polysorbate 80, especially in regulated pharmaceutical markets.
Shift Toward Plant-Based and Sustainable Ingredients
Consumer and industry preference for plant-based, clean-label, and sustainable ingredients is fueling demand for plant-derived polysorbate 80. This trend is particularly strong in food, cosmetics, and nutraceutical applications, where natural and allergen-free formulations are prioritized.
Growth in Processed Food and Beverage Industries
The rising consumption of processed foods, beverages, and convenience products worldwide is boosting the need for reliable emulsifiers like polysorbate 80. Its ability to improve texture, stability, and shelf life makes it integral to food innovation and mass production.
Rising Demand in Cosmetics and Personal Care
Polysorbate 80 is widely used as a solubilizer and surfactant in creams, lotions, and cleansers. The expanding global cosmetics and personal care industry, especially in Asia Pacific and Europe, is increasing the adoption of polysorbate 80 for stable and high-performance formulations.
Regulatory Compliance and Quality Standards
Stringent regulatory requirements for excipients in pharmaceuticals and food products are driving demand for high-quality, ultra-pure polysorbate 80. Leading manufacturers are investing in advanced refining and compliance processes to meet global safety and purity standards, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Polysorbate 80 Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Polysorbate 80 Market projected to grow between 2025 and 2032?
Which Global Polysorbate 80 Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Polysorbate 80 Market?
Who are the leading companies in the Global Polysorbate 80 Market?
Which region commanded the largest share of the Global Polysorbate 80 Market market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Plant Based
- 1.2.2 Animal Based
- 1.2.3 Synthetic
- 1.3 By Application
- 1.3.1 Pharmaceutical
- 1.3.2 Food & Beverage
- 1.3.3 Cosmetics & Personal Care
- 1.3.4 Nutraceutical
- 1.3.5 Agrochemical
- 1.4 By Functionality
- 1.4.1 Emulsifier
- 1.4.2 Dispersant
- 1.4.3 Solubilizer
- 1.4.4 Surfactant
- 1.4.5 Stabilizer
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 721.7 million → 2032: USD 1,177.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polysorbate 80 Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polysorbate 80 Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polysorbate 80 Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polysorbate 80 Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polysorbate 80 Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polysorbate 80 Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polysorbate 80 Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polysorbate 80 Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 721.7 million → 2032: USD 1,177.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polysorbate 80 Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plant Based
- 12.3.7.2 Animal Based
- 12.3.7.3 Synthetic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pharmaceutical
- 12.4.7.2 Food & Beverage
- 12.4.7.3 Cosmetics & Personal Care
- 12.4.7.4 Nutraceutical
- 12.4.7.5 Agrochemical
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Functionality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Emulsifier
- 12.5.7.2 Dispersant
- 12.5.7.3 Solubilizer
- 12.5.7.4 Surfactant
- 12.5.7.5 Stabilizer
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polysorbate 80 End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polysorbate 80 Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polysorbate 80 Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polysorbate 80 Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lonza Group Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF Corporation
- 18.4 Croda International plc
- 18.5 Solenis
- 18.6 Avril Group
- 18.7 Reachin Chemical Co., Ltd.
- 18.8 Lotion Crafter LLC
- 18.9 ERACHEM Comilog, Inc.
- 18.10 Compania Minera Aultan
- 18.11 Clariant
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

